
Best Ways to Save Money
Payday hits, I feel that quick burst of relief, then the money seems to vanish in a couple of days. Between bills, random subscriptions, and the cost of basics, it’s easy to wonder where my cash went, especially when I’m trying to fund a side hustle at the same time.
This post lays out the best ways to save cash without turning life into a strict no-fun zone. I’m focusing on cash flow first, because keeping more of what I earn matters before I stress about fancy strategies. Then I’ll show how to build simple systems so the plan keeps working even when I’m busy.
You’ll get quick wins you can use today (small cuts that add up fast), plus longer-term habits that make saving feel normal. I’ll also tie it back to side-hustle life, so extra income doesn’t get swallowed by lifestyle creep.
If you’ve never set up a real budget, I’ll keep it practical, and I’ll point you to my master budget tips for 2026 success so you can plug these changes into a plan that’s easy to follow. My experience and expertise stems from a strong desire to help people find financial independence. I hope the tips you find here will encourage you.
Find your hidden cash leaks in one weekend
When money “just disappears,” it’s usually not one huge mistake. It’s a bunch of small leaks that quietly drain my checking account, especially when I’m juggling side-hustle income that can swing week to week.
This weekend reset is one of the simplest ways to save cash because it gives me fast clarity. I’m not trying to build a perfect budget here. I’m trying to see what’s real, pick a few fixes that matter, and set a tiny routine that keeps me on track.
Do a 60-minute money audit (no guilt, just facts)
I start by pulling the last 30 to 60 days of transactions from my bank account and every card I use. I export to CSV if I can, but even scrolling through the apps works. The point is to get everything in one place, then sort each line into three buckets: needs, wants, and “forgot I had that.”
To keep it quick, I don’t overthink categories. Rent is a need. Streaming is a want. A random app charge I don’t recognize goes into “forgot.” If I’m unsure, I circle it and move on.
Here’s the short checklist I run through while I scan:
- Recurring charges I didn’t choose on purpose (apps, memberships, “free trial” conversions)
- Late fees (credit cards, utilities, subscriptions)
- Overdrafts and minimum balance fees
- Delivery fees (service fees, tips, small orders that add up)
- Interest charges (credit cards, buy-now-pay-later)
- Impulse buys (checkout add-ons, “limited time” purchases)
If I need help building the habit, I like the straightforward approach in Lifehacker’s guide to auditing your spending. It’s a good reminder that this is about patterns, not perfection.
My rule: I name the problem in plain English (“I’m paying for convenience”) instead of blaming myself (“I’m bad with money”).
Next, I do a 7-day spending snapshot. For one week, I tag every purchase the moment it happens (Needs, Wants, Forgot). This catches the “death by a thousand swipes” stuff that a monthly view can hide, like snacks, rideshares, and quick online orders.
Use the “big three” test to choose what to cut first
After the audit and 7-day snapshot, I don’t try to fix everything. I pick the top three leaks, using what I call the big three test:
- Monthly cost: How much does it hit me every month (or average per month)?
- Ease to change: Can I cancel, swap, negotiate, or cap it fast?
- Miss factor: How much will I actually care in two weeks?
This ranking keeps me honest. A $9.99 subscription is easy to cancel, but it might not “move the needle.” Meanwhile, eating out three times a week can be a bigger leak, even if it doesn’t look like much per purchase.
A few common examples, and how I think about them:
- Subscriptions: Usually high ease, low miss factor. I cancel first and re-add later if I truly miss it.
- Eating out and delivery: Medium ease, medium miss factor. I set a weekly cap and pick one planned meal out.
- Rideshares: Medium ease. I batch errands or use public transit when it’s safe and realistic.
- High-interest debt: High cost. Sometimes the “cut” is stopping extra spending so I can pay more than minimums.
The main goal is quick wins. Momentum matters. When I get an easy $50 to $150 back in month one, I’m more likely to follow through on bigger changes.
More Ways to Save Cash Posts You May Be Interested In
Frugal Living & Budgeting Tips
How to Live Simply and Frugally
Living Simply and Frugally Tips
Ways to Live On a Small Budget
10 Master Budget Tips for Success
12 Old Style Money Saving Tips
12 Frugal Living Tips from the Great Depression
10 Extreme Frugal Living Success Tips
How to Get in the Habit of Saving
15 Ways of How to Budget on a Low Income
Everyday Money-Saving Methods
How to Save Money While Shopping Online
14 Ways to Get a Free Visa Gift Card
20 Ways of How to Save Money for a Baby
15 Ways of How to Save Money on Gas
How to Save 20K a Year (15 Ways)
How to Save for a Down Payment on a House
14 No Spend Challenge Ideas to Save More
Lifestyle Choices That Save Big
Is Living in a Hotel to Save Money Worth It
25 Top Ideas to Vacation On A Budget
Travel Budget Planning | 20 Ways to Save
How Much Does it Cost to Rent a Motor Home
Long-Term Saving & Financial Security
How to Invest 2 Million for Retirement
How to Store Money Without a Bank
Tech & Tools to Boost Your Savings
Apps Like Ibotta | 25 Options to Earn Cash Back
10 Ways to Obtain Free Cash Cards
Kikoff Review: How This Credit Building Tool Can Help
Policygenius Review | An Affordable Way to Get Life Insurance
Independence Finance | Personal Capital Review
Coins to Cash Near Me | 10 Top Places
How to Exchange Coins for Cash Near Me
Extreme & Creative Ways to Save Money
10 Tips for Extreme Frugal Living
What is a Penny a Day Doubled for 30 Days
Birthday Freebees | 25 Places to Visit
Free Camping Resources for Success
Money Management & Mindset
The Importance of a Cash Budget
How Does Robinhood Make Money?
Set a weekly money check-in that takes 10 minutes
A weekend audit is great, but the real savings show up when I keep the leaks from coming back. So I set a repeating calendar reminder for a weekly check-in (same day, same time). Ten minutes is enough if I stay focused.
My weekly routine looks like this:
- Review spending: I scan the last seven days and spot any “creep” categories.
- Confirm bills: I check what’s due before the next paycheck or side-hustle payout.
- Transfer savings: Even a small automatic move helps, because it forces me to adapt.
- Plan one low-cost fun thing: A movie night at home, a hike, a library visit, or coffee with a friend.
This is where side-hustle life gets easier. If I have a big week of income, I can send extra to savings or debt right away. If it’s a slow week, I can tighten spending fast without feeling surprised later.
When I want to tie these habits into a bigger earning goal, I map the savings to a target like “tools for my hustle” or “runway for uneven months,” and I keep ideas handy from my own list on how to make $1000 a month extra.
Make saving automatic so willpower isn’t the plan
One of the most reliable ways to save cash is to stop treating saving like a mood. I don’t want to wake up motivated, open my banking app, and make the “right” choice. I want the right choice to happen in the background.
Automation is how I get there. It turns saving into a default setting, even when side-hustle income is uneven. The goal is simple: move money to the right place first, then live on what’s left.
Pay yourself first with small transfers that grow over time
I start small on purpose, because small wins are repeatable. A giant transfer feels heroic, but it’s also easy to undo the next time something “comes up.” Consistency is what builds real momentum.
Here’s the ladder approach I use:
- Week 1: Set an automatic transfer of $10 to $25 per payday to savings (same day as payday, or the morning after).
- End of month: If I stayed on track (no overdrafts, bills paid), I increase it by $5 to $10 per payday.
- After a side-hustle payout: I add a small “bonus transfer,” even if it’s just $10. Then I raise the base transfer next month.
That’s it. No complicated math.
The reason this works is because my budget adjusts around the transfer. If I save first, I naturally get better at living on the remainder. Over time, those tiny moves create a buffer that catches the small emergencies (car battery, copay, a slow client week) before they turn into credit card debt.
If my transfer ever feels too tight, I don’t quit. I drop it to a level I can repeat, then I climb again.
Use separate accounts to protect your cash from impulse spending
When all my money sits in one checking account, every purchase feels possible. That’s a problem. I’d rather build a simple setup that puts friction between me and impulse spending.
My clean “three account” setup looks like this:
- Bills account: Rent, utilities, insurance, minimum debt payments, subscriptions I kept.
- Spending account: Groceries, gas, eating out, fun, random life stuff.
- Savings account: Goal savings (and I keep it separate from checking on purpose).
If I can, I add a fourth:
- Emergency fund: A separate savings account that I don’t touch for goals.
Then I route money like a set of train tracks:
- Direct deposit goes into the bills account (or I split it if my employer allows).
- Automatic bill pay pulls from the bills account only.
- A scheduled transfer moves my “weekly spending amount” into the spending account.
- A separate scheduled transfer sends my savings amount to savings.
With variable income, I like weekly transfers because they smooth things out. I don’t need to guess if this is a high month or a low month. I just keep the system steady and adjust when the month is clearly different.
One practical tip that helps more than it should: if my bank allows it, I hide the savings account from my main dashboard (or I rename it something boring). When I don’t see the money, I’m less tempted to treat it like extra spending cash.
And when I’m picking specific targets to save for, I keep a short list of priorities handy so I’m not saving “for nothing.” This list of things to save up for in 2026 helps me choose a goal that actually matters.
Create “rules” for extra income so it doesn’t vanish
Side-hustle money disappears fast when it lands in the same account as everything else. I’ve watched a great payout turn into takeout, Amazon orders, and “I deserved it” spending in a week. So now I set rules before the money shows up.
A flexible baseline rule I like for side-hustle deposits and windfalls is:
- 50% to goals (savings, debt payoff, emergency fund)
- 25% to taxes (if I need it)
- 25% to fun or reinvestment (tools, courses, ads, or a guilt-free treat)
I keep it simple, then adjust based on where I am right now:
- If my emergency fund is under $1,000, I send most “goal money” there until it’s built.
- If I’m carrying high-interest debt, I shift the split (for example, 70% goals, 20% taxes, 10% fun) until I get breathing room.
- If my side hustle is growing, I treat “reinvestment” like rent for my future income, because buying back time and tools can raise earnings.
The main point is that extra income needs a job. Otherwise, it acts like water on a counter, it spreads out until it’s gone. For more ideas on building that extra income in the first place, I keep a running list of digital marketing side hustle ideas that can stack with a day job.
Cut monthly bills in a way that doesn’t wreck your lifestyle
When I want more breathing room (especially while I’m building side-hustle income), I don’t start by cutting coffee or fun. I start with the biggest recurring bills, because small percentage drops on big expenses create real monthly cash flow.
The goal is to right-size what I’m already paying for, then set a simple review routine so the savings stick. These are some of the highest-impact ways to save cash without turning my life into a constant “no.”
Lower your housing and utility costs with small, repeatable moves
Housing is the heavyweight. If I can reduce it even a little, everything else gets easier. I work top-down, starting with the moves that change my baseline.
First, I look at “space per dollar.” If I have a spare bedroom, a roommate can be the cleanest way to cut housing costs fast, as long as it’s safe and legal in my lease. If I own, I think in “house hack” terms (renting a room, basement, or ADU where permitted, with proper insurance and a written agreement). It’s not glamorous, but it’s one of the few changes that can drop my monthly nut without changing how I live day-to-day.
If roommates are a hard no, I try negotiation next. I’ve had better luck when I come prepared and make the ask simple.
- I bring facts (comparable listings, my payment history, and any minor issues that need fixing).
- I offer something in return (longer lease, auto-pay, or signing early).
- I ask for one clear win (lower rent, waived fees, or one-time credit).
Mortgages
If I have a mortgage, I review the “big three” items: rate, term, and mortgage insurance. Refinancing can help, but only when the math works and the fees don’t eat the savings. If refinancing isn’t a fit, I still call my servicer to ask about options, especially if my credit improved or my home value changed.
Next come utilities, because they’re sneaky. I don’t chase extreme frugality. Instead, I lock in a few habits that don’t feel like deprivation:
- Thermostat discipline: A small adjustment plus a fan often feels the same.
- Hot water awareness: Shorter showers, cold wash for most loads, and only running full loads.
- Vampire power cleanup: Unplug rarely used devices, or use a power strip to shut off a cluster.
- Air leaks: Weatherstripping and closing gaps helps comfort as much as cost.
Finally, I check for billing errors, because “quiet overcharges” are more common than people think. Once a month, I scan for:
- Double-billing (especially after moving or plan changes)
- Estimated utility reads that never get corrected
- Trash, water, or HOA fees that changed without notice
- Internet equipment charges for gear I returned
One more lifestyle-friendly win that also helps transportation: I plan errands like I’m routing deliveries. Fewer trips saves gas, reduces wear, and can lower mileage based insurance costs later.
If I’m only going to do one thing this month, I focus on housing first. Everything else is a lighter lift after that.
Shop insurance and phone plans like you’re switching for the first time
Insurance and phone plans punish loyalty. The easiest way I’ve found to cut them is to pretend I’m brand new and shop like I’m ready to leave.
For auto and renters or homeowners insurance, I compare apples to apples. Same coverage limits, same deductibles, and the same drivers and vehicles. Then I make three adjustments that usually move the price without wrecking protection:
- Raise deductibles only if I have a buffer. If I can’t comfortably cover the deductible from savings, I don’t touch it. A lower premium is not worth a future panic.
- Drop add-ons I don’t use. Rental car coverage I already have through another source, roadside assistance that duplicates AAA, or gadget coverage that overlaps.
- Ask for every discount. Multi-policy bundle, safe driver, low-mileage, paid-in-full, paperless, auto-pay, and defensive driving (where it applies).
I’ll often start with a comparison tool, then confirm the final numbers directly. NerdWallet’s car insurance comparison tool is a convenient place to begin, especially when I’m trying to get a quick baseline for my ZIP code.
Phone and Internet
For phone and internet, I treat the bill like a subscription I can replace. My go-to move is pricing out MVNOs (Mobile Virtual Network Operators). Many run on the same major networks, but at a lower monthly cost, as long as I’m fine with fewer perks.
On home internet, I check three things:
- Whether I’m still on a promotional rate, or if I quietly rolled to a higher price
- Whether my plan speed matches my actual needs (most households overpay for speed)
- Whether bundling (or unbundling) is cheaper after fees and discounts
Here’s the short call script I use. I keep it friendly, direct, and quiet after I ask:
- “Hi, I’m reviewing my monthly bills. What’s the best price you can offer on my current plan?”
- “Am I on a promotional rate right now? If not, what promos can you apply?”
- “If I switch plans (or remove add-ons), what would my monthly total be after taxes and fees?”
- “Are there discounts for auto-pay, paperless billing, or paying annually?”
- “If you can’t lower it, can you transfer me to the retention team?”
If they won’t budge, that’s still useful. I now have permission to switch without guilt.
Cancel, pause, or downshift subscriptions without feeling deprived
Subscriptions are where lifestyle bloat hides. The trick is to cut without making life feel empty, which is why I use a simple method instead of random cancellations.
Step 1 is the full list. I pull every recurring charge: streaming, music, apps, cloud storage, gym, meal kits, box subscriptions, and “free trials” that quietly flipped into paid plans.
Then I rank each one by true use, not wishful thinking:
- Green light: I used it weekly and I’d pay again today.
- Yellow light: I use it sometimes, but I could live without it for a month.
- Red light: I forgot about it, barely use it, or it overlaps with something else.
Then I cancel the bottom half. Not someday, not when I “have time.” I do it in one sitting.
To avoid feeling deprived, I rotate entertainment monthly. One month I keep a streaming service for a specific show. Next month I cancel it and switch to another. I’m still entertained, I’m just not paying for everything at once.
I also watch the billing cadence. Annual plans can be cheaper, but only for the few services I’d keep even if money got tight. Everything else stays monthly, because flexibility is worth more than a small discount.
One more easy win: I use a shared family plan only when it’s allowed by the service terms. If a platform supports household sharing, it can cut per-person costs without breaking rules or risking account issues.
My “once per year” bill review routine (so savings don’t fade)
Once a year, I run a personal “rate reset” week and put it on my calendar. I don’t renegotiate everything monthly. I just need a repeatable system.
Here’s my routine:
- Week 1: Pull the last 12 months of bills (housing, utilities, car costs, insurance, phone, internet, subscriptions).
- Week 2: Shop insurance quotes and request retention deals on phone and internet.
- Week 3: Re-rank subscriptions, cancel the bottom half, and set reminders before any free-trial renewals.
- Week 4: Confirm changes hit the next statement, then set auto-pay and alerts.
That’s the whole play. A few focused hours per year keeps my lifestyle intact, while my bills stop creeping up in the background.
Spend less day to day using simple guardrails, not strict budgets
Strict budgets break the moment life gets busy. Guardrails hold up better, because they guide my choices without making me track every dollar. I think of them like bumpers in a bowling alley. I can still roll the ball, but it stays out of the gutter.
These are my go-to guardrails for groceries, online shopping, and “treat yourself” spending. They’re simple, repeatable, and they free up cash for savings, debt payoff, or reinvesting in my side hustle. In other words, they’re practical ways to save cash that don’t depend on willpower.
Make groceries cheaper with a short list and a few default meals
When my grocery bill runs wild, it’s rarely because I “buy too much food.” It’s because I buy random food that doesn’t turn into meals. So I use a tight system that keeps me in the basics lane.
Here’s the repeatable routine I follow every week:
- Check the pantry and fridge first. I look for protein, produce that’s about to turn, and half-used items (tortillas, rice, pasta, sauces).
- Pick 3 to 5 low-cost default meals. I keep a short “greatest hits” list so I don’t need fresh ideas every time.
- Build a tight list from those meals only. If it doesn’t fit a meal, it doesn’t go on the list.
- Eat something before I shop. Even a snack helps, because shopping hungry turns my cart into a wish list.
My default meals are intentionally boring in a good way. For example: chili, sheet-pan chicken and veggies, rice bowls, pasta with frozen veg, and breakfast-for-dinner. When I’m busy with side-hustle work, “default” beats “perfect.”
Two more guardrails save me the most at the store:
- Store brands first. I’ll pay extra for a few items I truly care about, but most basics taste fine as store brand.
- Unit pricing over package pricing. Big numbers on signs can be misleading. I compare the price per ounce or price per count, then move on fast.
Leftovers also need a plan, or they become “future trash.” I cook with leftovers on purpose by assigning them a job: tomorrow’s lunch, a freezer portion, or a remix meal (taco night becomes taco salad, roasted veggies become omelets).
My biggest grocery guardrail is simple: I don’t buy ingredients, I buy meals.
Use a 24-hour rule to stop impulse buys online
Online shopping is frictionless by design. One click turns a rough day into a package on the porch. That’s why I don’t try to “be disciplined” in the moment. Instead, I make buying slower.
My 24-hour rule looks like this:
- I add the item to a wish list (not my cart).
- I wait one full day.
- The next day, I decide if it’s still a real need.
That pause works because the emotional heat fades. A lot of stuff feels urgent at 9 p.m. and pointless the next afternoon.
To make this even easier, I reduce temptation at the source:
- Remove saved cards from shopping apps and browsers. Re-entering numbers is annoying, and that’s the point.
- Unsubscribe from promo emails (or filter them to a folder I never check).
- Turn off push notifications for shopping and deal apps.
One more thing I remind myself of: returns are a hidden cost. Even when the return is “free,” I still pay with time, gas, printing labels, missed windows, and that low-grade stress of unfinished tasks. When I account for that, a “good deal” often stops looking good.
Plan cheap fun so you don’t “treat yourself” into debt
I don’t try to eliminate treats. I plan them. When I don’t plan fun, boredom and stress pick for me, and they usually pick something expensive. A $9 coffee turns into a $40 dinner fast, especially after a long workday.
So I schedule low-cost fun the same way I schedule errands. Having something on the calendar lowers that restless urge to buy convenience.
A few options that work well in the real world:
- Free local events: Outdoor concerts, art walks, community festivals, and park meetups.
- Potlucks: Everyone brings one dish, and nobody carries the whole bill.
- Library perks: Beyond books, many libraries offer movies, classes, and community events.
- At-home movie nights: Popcorn at home, phone on Do Not Disturb, and a “start time” like it’s a real event.
When I want ideas that don’t cost anything, I scroll a list like things to do for free and pick one for the week.
My favorite guardrail here is a “planned treat” rule: I choose one paid fun thing ahead of time (lunch out, a concert ticket, a new book), then I enjoy it fully. Planning gives me the same relief as impulse spending, but with less regret the next morning.
Turn saving into a cash-building system for long-term freedom
Saving feels hard when it’s just “money I’m not allowed to spend.” I do better when saving has a job. In practice, my system has three jobs: protect me from surprises, reduce interest, and buy tools and time to grow income.
Here’s the simple order of operations I follow so my money stops getting pulled in five directions at once:
- Starter emergency fund (small, fast, calming).
- High-interest debt payoff (the stuff that charges me rent to exist).
- Income growth bucket (small, measured reinvestment to earn more).
Build a starter emergency fund first, then grow it
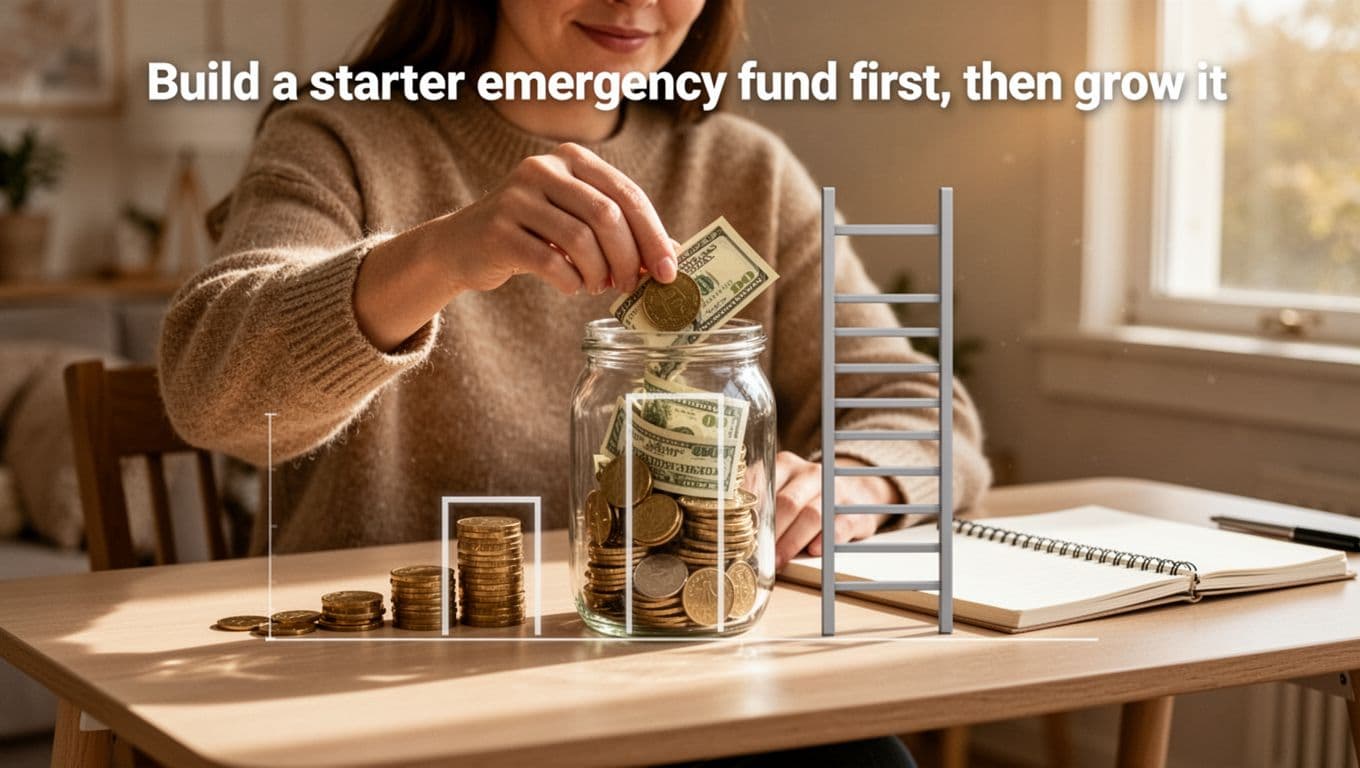
A starter emergency fund is my best defense against credit card backslides. Without a buffer, every flat tire or random copay becomes “put it on the card,” and then I’m stuck paying interest on yesterday’s problem.
I like to think of this fund as a shock absorber. It does not need to be huge to work. It just needs to be ready.
My milestones are simple and realistic:
- $500 starter buffer: Covers the most common “life happens” hits.
- One month of expenses: Makes a slow work month less scary.
- 3 to 6 months of expenses: Gives real breathing room, especially with variable side-hustle income.
Where I keep it matters, because this money has one purpose: show up fast when I need it. I keep my emergency fund safe and liquid, usually in a separate high-yield savings account at an FDIC-insured bank (not in stocks, not locked in a long-term product). If I can’t transfer it to checking in a day or two, it’s not doing its job.
My rule is boring on purpose: if it’s an emergency, it’s unexpected, necessary, and urgent. Otherwise, it’s a budget item.
Use the cash you save to kill high-interest debt faster
Once my starter fund exists, I redirect extra cash to debt. This is one of the most underrated ways to save cash because it reduces the interest I’d otherwise pay every month.
There are two simple payoff styles:
- Debt snowball: I pay off the smallest balance first (best for motivation and quick wins).
- Debt avalanche: I pay off the highest interest rate first (best math, saves more interest over time).
How do I choose? If I feel stuck and need momentum, I pick snowball. If I feel steady and want the most efficient plan, I pick avalanche. Either way, I keep paying minimums on everything, then I aim extra money at one target debt.
Here’s a real-world example: let’s say I cut a few subscriptions and tighten groceries, and I free up $150 per month. Instead of letting that disappear into “extra spending,” I add it to my debt payment. If my minimum payment is $60, I now pay $210 per month on that one card or loan. That extra $150 is like pushing a boulder downhill. At first it’s slow, then it speeds up.
The biggest trap during payoff is taking on new debt while I’m trying to escape old debt. So I set two guardrails:
- I stop carrying my credit card for daily spending if I can’t pay it off weekly.
- I don’t “celebrate” savings wins with purchases that restart the cycle.
Put saved cash to work on income growth (without blowing the budget)
After my starter emergency fund is built and my debt plan is in motion, I start using some saved cash to grow income. This is where saving connects directly to side-hustle progress. Cash can buy tools, skills, and time, but only if I keep it controlled.
I use three rules so “reinvestment” doesn’t become an excuse to shop:
- Set a monthly cap: For example, $25 to $100 per month, based on where I am.
- Measure results: I track one metric that matters (leads, applications sent, gigs landed, posts published).
- Use a separate business bucket: A separate account or “hustle” savings category keeps spending honest.
Most importantly, I put free strategies first, then I pay for tools after proof. That means I start with what costs nothing: consistent outreach, better offers, portfolio samples, and learning from free tutorials. Once I see traction, I invest to remove friction, like a basic mic for tutoring calls, a simple domain, or a targeted course that fills a real skill gap.
If I need side-hustle ideas that don’t require a big upfront spend, I pull from lists like these winter side hustles and pick one I can start with what I already have.
For tracking income and expenses once I’m earning, this guide on side hustle budgeting offers a practical way to stay organized without turning it into a second full-time job.
Conclusion
The best ways to save cash are the ones I can repeat when life gets busy. When I find one leak, automate one move, and trim one bill, I stop relying on motivation and start building a system. Over time, those small wins stack into real breathing room, even on uneven side-hustle months.
Here’s my 3-step plan for today:
- Pick one leak: Choose the easiest high-impact fix (a forgotten subscription, delivery fees, or impulse buys). Then cancel it or cap it right now.
- Set one automation: Schedule a small transfer for payday, even $10. The point is consistency, not a heroic amount.
- Cut one bill: Call one provider (internet, insurance, phone) and ask for the best rate. If they can’t help, price out a switch.
After that, I keep the savings on a job, emergency buffer first, then debt, then tools and time to grow income. If I want extra options fast, I pair this plan with a realistic earning track like these side hustles for moms.
Back to Save Money Hub