
Ways to Live On a Small Budget

Disclosure: This post may contain affiliate links, meaning if you decide to make a purchase through my links I may earn a commission at no additional cost to you. See my disclosure for more info.
Build A Smarter Online Business
Want to turn your content into traffic, income, and long-term freedom? Start with the guides built to help you grow smarter.
Explore Online Business Guides →Living on a small budget doesn’t mean scraping by or skipping fun. Right now, basics like rent, groceries, and gas cost a single person over $4,000 a month on average in the US. However, you can slash that to around $2,200 with smart moves, so you cut stress instead of joy.
Ways to live on a small budget focus on big wins first. Target housing (like roommates or cheaper towns), food (home cooking bulk meals), and transportation (biking or buses). These simple systems bring the most savings, without extreme frugality. For example, sharing rent drops costs by $500 to $1,000 monthly.
Prices shift fast, with inflation at 1.8% lately and housing eating 35% of budgets. Review your plan every month, then adjust yearly for changes. That keeps you ahead.
In this post, you’ll get tips on those top areas: housing, food, transport, utilities, smart shopping, and free entertainment. You’ll build habits that save 30-50% quickly. Start today, and feel the relief grow.
Back to Ways to Save Cash
Start with a simple budget that tells every dollar where to go
You can build a basic budget in less than an hour. First, grab your take-home pay amount. That’s your starting number after taxes. Next, list fixed bills like rent, utilities, and loans. Subtract those from pay. Then, assign every leftover dollar to categories. This is zero-based budgeting. Every dollar gets a job, so nothing slips away.
For example, say your take-home pay hits $3,000 monthly. Fixed bills total $1,800 (rent $1,200, utilities $200, phone $100, insurance $300). You have $1,200 left. Split it like this:
- Food: $400
- Gas/transport: $150
- Savings: $200
- Fun: $100
- Sinking fund: $50 (for surprises like car fixes or gifts)
A sinking fund handles irregular costs. Save a bit each month for them. No big shocks later. Check your budget Sundays. Spend five minutes noting spends and tweaks. This habit keeps you on track. As a result, you’ll spot patterns fast.
These steps fit ways to live on a small budget. They cut waste without stress.
Ready To Build More Traffic And Income?
Use Internet of Business to learn blogging, SEO, affiliate marketing, passive income, and digital business systems that compound over time.
Start Building Your Digital Income →Pick a budgeting style you will actually keep using
Choose a method that sticks. Perfection fails fast. Consistency wins. Here are three solid options.
Zero-based budgeting suits detail lovers. You assign every dollar upfront. It stops overspending because nothing floats free. Busy folks prefer the 50/30/20 rule. Put 50% on needs, 30% on wants, 20% on savings or debt. It’s flexible for starters. Cash envelopes work best for impulse buyers. Fill envelopes for categories like food or gas. Once empty, you stop. Cash feels real.
Pick one and tweak as needed. Free spreadsheets or apps help track without hassle. Stick with it for a month. You’ll build momentum.
Build a “boring money system” to stop falling behind
Automation kills forgetfulness. Set up bill pay through your bank. Bills leave on time. Next, transfer savings first on payday. Even $50 builds up. Then, do a 15-minute weekly check. Sunday evenings work well. Review spends, compare to budget, adjust next week.
Add this rule: Wait one pay cycle for non-essentials. Want new shoes? Hold until next check. This pause shows true budget fit. Impulse drops because you see the hit. In short, boring systems create freedom. You stay ahead without daily fights.
Find and fix your biggest money leaks in one weekend
Spend a weekend plugging leaks. You’ll save hundreds. Follow this checklist:
- Gather bank and card statements from the last 60 to 90 days. Print or download them.
- Highlight recurring charges. Subscriptions hide everywhere.
- Cancel unused ones. Gym pass from last year? Gone. Apps you forgot? Delete.
- Renegotiate bills. Call internet, phone, and insurance providers. Ask for deals. Many cut 10 to 20% off. Be polite but firm.
- Set calendar reminders. Re-shop these bills yearly. Rates change.
For instance, average utilities run $370 monthly. Shop around, save $50 easy. This quick audit uncovers $200 to $500 hidden spends. Then, redirect to savings. Your budget strengthens right away.
Cut the big three costs: housing, food, and transportation
Housing, food, and transportation claim the biggest chunks of your budget. In early 2026, a single person faces national averages around $1,200 to $1,800 for studio rent, $330 to $500 for groceries, and $800 to $1,200 monthly for transport. These vary by location, of course.
However, smart tweaks drop them fast. For example, you can trim housing to $800 to $1,200, groceries to $250 to $350, and transport to $150 to $300. That’s ways to live on a small budget that beat endless penny-pinching. Small changes here free up hundreds each month. Let’s break it down.
Lower your housing cost without making life miserable
Start by rethinking your space. Get a roommate to split rent. Many split a two-bedroom for $600 to $900 each, down from $1,200 solo. Pick someone reliable through friends or vetted sites. Or rent smaller, like a studio over a one-bedroom. You save $200 to $400 without much loss in comfort.
Move a few miles out. Suburbs often cost 20% less, and remote work makes commutes optional. House sitting apps offer free stays in exchange for pet care; try it for a month to test. Always negotiate at renewal. Landlords often match competitor rates if you ask politely.
Cut utilities too. They add $200 to $300 monthly. Switch to LED bulbs; they use 75% less energy. Adjust your thermostat to 78 in summer, 68 in winter. Seal drafts around doors and windows with weatherstripping. Review your energy plan yearly; shop providers for 10% savings.
Here are quick wins:
- Unplug chargers when not in use.
- Wash clothes in cold water.
- Run full loads only.
Never chase savings into unsafe spots. Vet roommates, check neighborhoods, and trust your gut. These steps keep life good while you save.
Spend less on groceries with a plan, not willpower
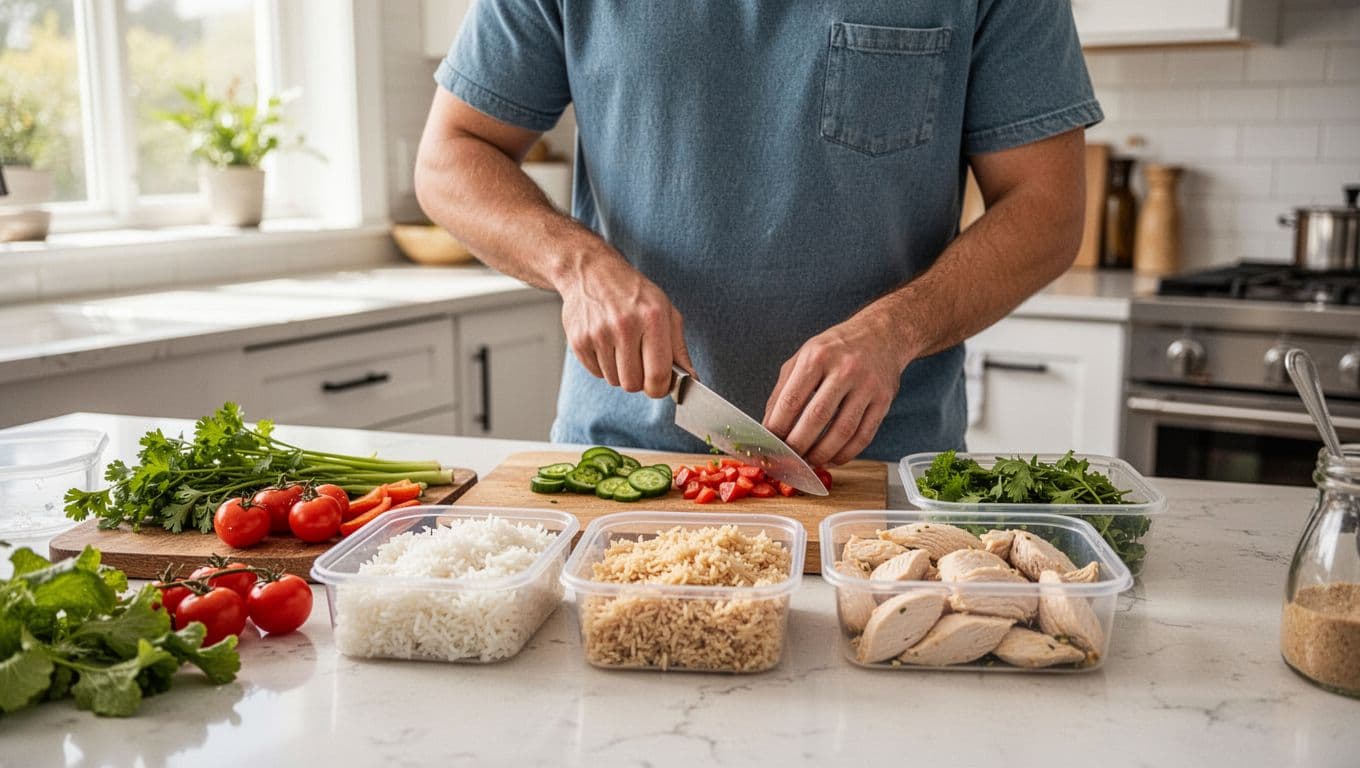
Plans beat grit every time. Pick 6 to 10 simple meals you like, such as stir-fry, pasta, or bean soup. They repeat weekly, so you shop once with a strict list. Cook extra for leftovers; double batches stretch to lunches. Limit convenience foods like premade sauces; they double costs.
Use grocery pickup. Order online, and skip the store aisles. Impulse buys vanish, saving 20% easy. National averages hit $330 to $500, but this drops you to $250 to $350.
Try this low-cost week framework:
- Breakfast: Oatmeal with fruit or eggs (under $1 per serving).
- Lunch: Leftovers from dinner, like rice bowls.
- Dinner: Rotate chicken stir-fry (Monday/Wednesday), lentil soup (Tuesday/Thursday), veggie pasta (Friday), beans and rice (weekend).
Buy generics, hit sales, and freeze extras. Shop the perimeter for fresh items. As a result, your fridge stays full without waste. You’ll eat well and bank the difference.
Transportation savings that add up every month
Group errands into one trip. Hit the store, bank, and post office together; you cut gas by half. Set no-spend days, like weekends at home. Walk or bike short distances. A helmet and backpack handle most needs.
Public transit or carpooling works great. Apps match rides, splitting costs. Keep tires inflated to 32 PSI; it boosts mileage 3%. Stay on maintenance, like oil changes every 5,000 miles. Repairs skyrocket otherwise.
Compare true costs before deciding. Add car payment, insurance ($100 to $200), gas ($150), and upkeep. Total often hits $800 plus. Biking or buses? Under $150. Ditch the car if it fits your life.
Other tips include:
- Park far and walk in.
- Use apps for transit deals.
- Bike to work if under 10 miles.
These habits stack up to $500 monthly savings. You move freely without the drain.
Lower your monthly bills and debt payments (without feeling stuck forever)
Recurring bills and debt payments trap cash each month. They add up quietly, but you can reset them to free up breathing room. These ways to live on a small budget target interest and fixed costs first. As a result, you build monthly margin without endless sacrifice. Start with a yearly check, then tackle debt and extras.
Do a yearly “bill reset” to keep up with price increases
Prices creep up with inflation around 2.4%. So, block one day each January to shop around. You will spot better deals fast.
Begin with car insurance. Full coverage averages $191 to $195 monthly now. Minimum runs $53. Call your provider first. Ask for loyalty discounts or promotions; many offer 10% off. Then, get quotes from GEICO, Progressive, or State Farm online. Switch if you save $20 or more. Next, check renters insurance at about $15 monthly. Bundle it with car for extras savings.
Phone plans cost $50 to $80 per line. Lower to basic data or switch carriers like Mint Mobile for half. Internet bills hit $60 to $100. Drop speed from gigabit to 100 Mbps if you stream less; save $20. Remove add-ons like premium channels.
Call providers politely. Say, “What promotions match my account?” They often match competitors. After changes, add a $20 to $30 inflation buffer to your budget. It covers rises without stress. In short, this reset saves $100 monthly easy.
Get serious about interest: choose a debt payoff plan
Interest grows debt fast, so pick a plan that fits you. Debt steals your margin; paying it down creates freedom. Go simple and steady, no shame needed.
Debt snowball clears smallest balances first. It builds quick wins for motivation. Avalanche hits highest interest rates next. It saves most money long-term. Choose snowball if you need momentum. Pick avalanche if math drives you.
Take this example with three debts:
| Debt | Balance | Interest Rate | Minimum Payment |
|---|---|---|---|
| Credit Card A | $500 | 22% | $25 |
| Credit Card B | $2,000 | 18% | $80 |
| Store Card | $1,200 | 25% | $40 |
Snowball pays minimums on all, then extra on smallest ($500 card). Gone in months, you roll to next. Avalanche targets store card (25%) first. You save $150 interest over a year.
Pay minimums always. Cut credit cards for basics; they add high interest traps. If overwhelmed, call a nonprofit credit counselor like NFCC.org. They review free and guide plans. Above all, extra payments shrink balances quick.
Reduce subscriptions and “small treats” without feeling deprived
Households spend $70 monthly on streaming alone, up to $1,000 yearly total. Mindless adds pile up. Cut smart, keep joy.
Swap subscriptions first. Use library apps like Libby for free books and movies. Rotate one streaming service monthly; cancel others. Share family plans with friends.
Small treats tempt daily. Brew coffee at home five days; buy once as reward. That saves $50 monthly. Set a $50 fun money category. Spend it guilt-free on treats.
Track apps weekly. Delete forgotten ones. Focus cuts waste, not fun. Therefore, you free $100 plus without regret.
Stretch what you already have: frugal habits that feel normal
You already own skills and access that cut costs. These habits make frugality feel easy because they build on daily life. In addition, they fit ways to live on a small budget by repairing, reusing, borrowing, and planning ahead. Households spend about $300 monthly on entertainment alone. So, shift to free options. You save big while keeping fun alive.
Use free community resources you are already paying for
Your tax dollars fund libraries, parks, and centers. Tap them first for entertainment. Libraries offer books, movies, and classes at no extra cost. Many lend tools too, like ladders or power drills. Borrow a drill for a weekend fix instead of buying one.
Parks provide free walks, picnics, and sports. Community centers host events like yoga or game nights. Check for free museum days or local festivals. These replace paid outings during tight months. For example, stream a movie from the library app instead of Netflix. You dodge that $11 monthly per service. As a result, fun stays cheap and close.
Buy less, but buy smarter when you do spend
Pause before non-essentials. Wait 24 hours or one pay cycle. This curbs impulses. Next, compare unit prices at the store. A bigger pack often costs less per ounce. Buy used first through apps or thrift shops. Furniture saves 50 to 70% that way. Tools and kids’ gear hold up well second-hand too.
Focus on quality for daily items like pots or shoes. They last longer, so you replace less. However, buy new for safety. Car seats and helmets need current standards.
Consider these categories:
- Great used buys: Sofas, drills, strollers, bikes.
- Buy new: Tires, cribs, safety gear.
You spend less overall. Therefore, your budget stretches further without skimping.
Stop outsourcing what you can do in minutes
Handle quick tasks yourself. Basic home fixes save labor costs, often 50 to 70% of the bill. Watch free videos for a leaky faucet or wall patch. You spend $20 on parts, not $200 for a pro.
Sew a button or hem pants in five minutes. Pack lunch from leftovers; skip $10 cafe runs. Set simple cleaning routines, like 15 minutes daily. These build skills and confidence fast.
Start small. Pick one task weekly. In short, you pocket cash and feel capable. Meanwhile, outsource big jobs only.
Earn a little extra without burning out
Extra cash helps in ways to live on a small budget. It creates breathing room, pays debt faster, or grows savings. However, you don’t need a second full-time job. Pick low-startup options that fit your schedule. In early 2026, apps make it simple with no upfront costs beyond a phone. Start small to avoid burnout. You gain $200 to $500 monthly without extra stress.
Start with quick wins: sell, swap, and barter
Declutter your home first. Sort clothes, books, electronics, or tools you forgot. Snap clear photos and list on OfferUp for local sales. You earn quick cash from items gathering dust. Prices depend on condition, but common stuff like old phones or bikes fetch $20 to $100 each.
Barter skills next. Swap childcare with a neighbor, fix a fence for yard work, or tutor math for meals. Post on Craigslist or TaskRabbit as “skills trade.” This cuts spending without cash outlay. For example, two parents alternate babysitting saves $100 weekly.
Stay safe online. Use app ratings and background checks. Meet in public spots like police stations or malls during daylight. Tell a friend your plans. For payments, stick to app direct deposits; skip cash or wire transfers. Verify buyers first. These steps protect you while you profit.
Try flexible side hustles that fit a busy schedule
Gig apps offer fast entry. Delivery via DoorDash, Uber Eats, or Instacart pays $16 to $27 per hour with tips. Run errands on TaskRabbit or temp shifts through Instawork at about $20 hourly. These fit evenings or weekends.
Local services suit homebodies. Pet sit on Rover or do yard work; average $19 per hour. Walk dogs in your neighborhood for steady gigs.
Online skills shine remotely. Freelance admin, design, or tutoring on Fiverr or Upwork starts at $20 plus per hour. No commute needed.
Track mileage at 67 cents per mile for 2025; check IRS for 2026 rates. Use apps like Shift Tracker. Set aside 25 to 30% of earnings for taxes since gigs over $400 need Schedule C reporting. Quarterly payments avoid surprises if you owe $1,000 plus.
Protect your time: the side hustle test
Test gigs before committing. First, calculate expected hourly pay after costs. Subtract gas or fees from earnings. Aim for $15 net or better.
Next, check schedule impact. Does it clash with your job or rest? Skip if it squeezes sleep.
Assess stress level. High-pressure rushes burn you out fast. Choose calm options like pet sitting.
Finally, see if it crowds family time. Protect evenings and weekends.
Pick one hustle for 60 days. Track results weekly. If it fits, keep going. Otherwise, swap it out. This filter keeps extra income helpful, not harmful. In short, you build wealth steadily.
Conclusion
You now hold solid ways to live on a small budget that work. Build a simple budget first. Then attack the big three costs: housing, food, and transport. Reset bills yearly to fight inflation. Adopt frugal habits that feel normal, like using libraries or fixing things yourself. Add side income if needed, without burnout.
These steps slash your monthly spend from over $4,000 to around $2,200. You keep joy while stress fades. Most importantly, review and tweak every month. Life changes, so your plan should too.
Start today with this 7-day plan:
Day 1: List your take-home pay and fixed bills.
Day 2: Track all spends for the day in a notebook or app.
On Day 3: Pick one roommate ad or suburb to check for housing.
Day 4: Plan 7 meals and make a strict grocery list.
Day 5: Call one bill provider to ask for a better rate.
On Day 6: Visit your library or park for free fun.
Day 7: List three items to sell online or one gig to try.
Back to Ways to Save Cash
Are you looking for better ways and tools to build your monthly revenue and brand? Be sure to check out our other resources located here to speed up the process.
Nathan
Dr. Nathan Pennington, DBA, earned his Doctor of Business Administration degree from the University of Missouri-St. Louis and brings over 15 years of online entrepreneurial experience in helping people learn how to blog, earn income online and build passive income streams outside of what the school system teaches.


