
Vanguard Institutional 500 Index Trust for FIRE Investors

Disclosure: This post may contain affiliate links, meaning if you decide to make a purchase through my links I may earn a commission at no additional cost to you. See my disclosure for more info.
Build A Smarter Online Business
Want to turn your content into traffic, income, and long-term freedom? Start with the guides built to help you grow smarter.
Explore Online Business Guides →Have you been searching for more information regarding the Vanguard Institutional 500 index trust? If you’re chasing FIRE while building side income, your investing plan has to be simple enough to stick with, even when work gets busy and your side projects demand attention.
That’s why I pay close attention to what’s already inside my employer accounts, because consistency beats complexity.
The Vanguard Institutional 500 Index Trust is a pooled investment vehicle that aims to track the S&P 500, usually offered inside retirement plans. It shows up in 401(k)s and 403(b)s because it’s built for institutions, it can be cheaper to run at scale, and it’s designed to fit plan recordkeeping rules. You’ll also sometimes see it in certain HSAs when the HSA provider offers a 401(k)-style investment menu.
Still, it can feel confusing because it’s not an ETF you can buy in a regular brokerage account, and it doesn’t behave exactly like a standard mutual fund. The ticker might be missing, the share price can look unfamiliar, and the name can vary depending on the plan. Those details matter when you’re trying to track performance, understand fees, or plan rollovers without creating a tax mess.
In this post, I’ll explain how the trust works in plain terms, how it compares to Vanguard’s S&P 500 ETFs and mutual funds, and how I decide whether it earns a spot in a FIRE-focused portfolio. I’ll also cover the practical stuff, like what to check in your plan docs and what to do when you leave a job, so your investing stays on track while you keep growing income on the side.
Back to How Can I Become an Entrepreneur
What the Vanguard Institutional 500 Index Trust actually is (and what it is not)
I first spotted the Vanguard Institutional 500 Index Trust in my 401(k) menu years ago. It tracks the S&P 500 just like popular ETFs or mutual funds do. However, it stands out as a pooled investment vehicle built for employer-sponsored retirement plans, not something you snag in a regular brokerage account.
This trust pools money from many participants into one big pot. Vanguard invests that pot to mirror the S&P 500’s large-cap stocks. The “institutional” tag signals low costs and bulk access, often with expense ratios around 0.006%.
People get tripped up by “trust” because it sounds old-school or vague. In reality, it just means a special structure for plans, complete with its own rules on pricing and trading.
Ready To Build More Traffic And Income?
Use Internet of Business to learn blogging, SEO, affiliate marketing, passive income, and digital business systems that compound over time.
Start Building Your Digital Income →It is not a retail mutual fund with a standard ticker like VFINX. You also won’t trade it intraday like an ETF such as VOO. Instead, it fits seamlessly into workplace accounts where simplicity rules for long-term holders like me chasing FIRE.
Trust vs mutual fund vs ETF: the quick, useful differences
Trusts, mutual funds, and ETFs all chase indexes like the S&P 500. Yet their setups change how you interact with them. Here’s a breakdown of the key contrasts that affect everyday use.
Trusts lack public tickers; providers list them by name or fund number, like 7518. Mutual funds show a net asset value (NAV) at day’s end. ETFs trade all day at market prices.
Trades work differently too. Mutual funds and trusts settle once daily after markets close. ETFs let you buy or sell anytime during hours.
For FIRE investors holding years or decades, these gaps rarely bite. You care more about low fees and steady tracking. But portability matters when you switch jobs. Trusts demand rollovers to IRAs, where records might not match perfectly. That can snag tracking in tools like Personal Capital.
How access works inside a 401(k) or 403(b)
You won’t find this trust on Vanguard’s main site for individuals. Plan sponsors add it to menus because it cuts costs at scale. My 401(k) labels it under names like “Vanguard Inst 500 Index Trust” or share classes such as Unit FLX.
The employer or recordkeeper runs the show. They process buys with contributions and sales on withdrawals. Statements roll out quarterly or yearly through the plan portal, not Vanguard directly.
This setup keeps things tidy for big groups. However, it limits choices until you roll over. I check plan docs first to confirm availability and fees before maxing contributions.
What you own and what protections you have
Participants own units in the trust, backed by actual S&P 500 stocks. Vanguard holds those as custodian, with the plan’s trustee overseeing rules. Your slice stays diversified across 500 big U.S. companies.
Protections mirror standard retirement plans. ERISA rules shield assets from creditors in qualified accounts. The structure adds layers like segregated accounts to guard against firm issues.
Fact sheets and updates arrive via your plan admin, not retail pages. I always download them to track changes. This keeps my FIRE path clear, even inside employer walls.
Costs, tracking, and taxes: the details that move your FIRE timeline
Small differences in fees, tracking, and taxes add up fast in a FIRE plan. They shift your timeline by months or years because money compounds over time. For example, I once compared two S&P 500 options. Start with $100,000 growing at 7% annually. After 20 years, a 0.03% fee leaves about $387,000. A 0.10% fee drops it to $384,000. That $3,000 gap covers a solid emergency fund boost or seed money for a side hustle.
The Vanguard Institutional 500 Index Trust often wins here with its low costs. However, you must dig into the details. Plan documents hide the full picture. In addition, tracking matters because even index funds vary slightly. Taxes play a role too, especially in retirement accounts. Let’s break it down so you spot what accelerates your path.
Expense ratio or trust fee, and where to find it in your plan documents
I always hunt for the true cost of the Vanguard Institutional 500 Index Trust first. The headline expense ratio looks great, often 0.006%. Yet the all-in cost includes extras.
Check your plan fee disclosure (Form 404a-5). Employers send this yearly. It lists the trust fee plus any revenue sharing. Next, grab the fund fact sheet. Finally, log into your recordkeeper portal, such as Fidelity or Empower. It shows unit prices and fees side by side.
Revenue sharing means the recordkeeper takes a cut from Vanguard. This pays for plan admin. So a 0.006% fund fee might hit 0.03% total. That seems tiny. However, over decades, it compounds. I spotted this in my old 401(k). The portal revealed extra 0.02%, pushing my effective rate higher than expected
Tracking difference: why two S&P 500 options don’t always perform the same
Even low-fee S&P 500 trackers differ slightly from the index. Tracking difference measures this gap. The Vanguard Institutional 500 Index Trust aims for close match, not outperformance.
Full replication buys every stock in the S&P 500. Sampling buys a representative basket to cut costs. Securities lending adds income by renting holdings. Cash drag happens when new money sits uninvested briefly. Rebalancing timing aligns the portfolio after index changes.
These factors cause small lags, often under 0.05% yearly. I review quarterly statements. For instance, my trust trailed the index by 0.02% last year due to cash drag. That’s fine. Close tracking keeps costs low over time.
Tax angle: why this trust shines in retirement accounts but matters less in taxable
Most hold the Vanguard Institutional 500 Index Trust in 401(k)s or 403(b)s. Tax-advantaged wrappers defer taxes on dividends and gains. No annual hits slow growth. This fits FIRE perfectly. You compound fully until withdrawal.
In taxable accounts, ETFs edge out with better tax efficiency. They minimize capital gains distributions. Trusts act like mutual funds, potentially spilling gains yearly. Still, few use trusts there anyway.
Roth conversions matter for FIRE. I plan them to fill low tax brackets now. Traditional accounts defer taxes. So pick based on your future rate. In short, taxes barely dent inside plans. Focus there first.
How it compares to Vanguard’s S&P 500 funds you can buy anywhere
I often weigh the Vanguard Institutional 500 Index Trust and the Vanguard Global Aggregate Bond UCITS ETF against retail options like the VOO ETF or VFIAX mutual fund. Both track the S&P 500 with rock-bottom fees, but the trust shines in employer plans due to its institutional edge.
VOO trades all day like a stock, while VFIAX settles at end-of-day NAV, much like the trust. However, access changes everything. You buy VOO or VFIAX anywhere with a brokerage, but the trust stays locked in your 401(k) or 403(b). For me, costs and tracking tip the scales in specific spots.
The trust often undercuts retail fees after plan perks, yet portability favors ETFs outside work plans.
When the trust is the best deal in your plan
The Vanguard Institutional 500 Index Trust beats retail S&P 500 funds inside employer plans. It delivers the lowest costs through institutional pricing, often 0.006% before extras. Solid tracking keeps pace with the index, thanks to full replication at scale. Plus, automation runs smooth with payroll deductions.
Employer perks seal the win. Plans bundle low recordkeeping fees, so your all-in cost stays under VOO’s 0.03% or VFIAX’s 0.04%. Contributions flow directly, no transfers needed. I max my 401(k) here because it builds my FIRE stack effortlessly while I focus on side income.
Use this quick checklist to confirm if the trust fits your plan:
- Fee check: Review Form 404a-5 for total expense under 0.02%.
- Tracking review: Compare last year’s return to S&P 500; lag under 0.05% works.
- Automation test: Confirm payroll buys units daily or monthly.
- Scale bonus: Assets over $1 million? Costs drop further.
In short, stick with the trust if your job lasts years. It compounds fastest there.
When an ETF or mutual fund might be better
ETFs like VOO or mutual funds like VFIAX pull ahead outside employer plans. You gain flexibility for rollovers or unified accounts. For example, I consolidate everything at one broker to track net worth easily.
Job changes trigger this shift. The trust won’t transfer directly, so cash out and rebuy VOO. A single brokerage simplifies research too; public tools show real-time quotes and holdings. Intraday trading suits VOO if you tweak rarely, though FIRE folks seldom need it.
Public data helps. Vanguard’s site details VOO flows or VFIAX yields instantly. Plan portals lag on that.
Above all, pick the cheapest, diversified S&P 500 option in your account. VOO wins in IRAs for liquidity. VFIAX fits if you prefer mutual fund simplicity. I switch to them post-job for one dashboard view.
Portability and rollovers: what happens when you change jobs
Trusts like the Vanguard Institutional 500 Index Trust don’t roll over intact to IRAs. Plan rules block direct transfers of units. Instead, you sell shares inside the 401(k), move cash to your IRA, then buy VOO or VFIAX.
This path exposes you to market risk during the switch. Stocks dip? Your cash misses gains. Or they rise, and you buy higher. I faced a 2% drop once; it cost $2,000 on a $100,000 rollover.
Minimize it simply. Initiate the rollover fast, within days. Direct trustee-to-trustee moves cut delays. Your old plan sells at NAV close, new IRA buys next day. No gap.
After all, plan ahead. Check rollover rules in your summary plan description. This keeps your FIRE momentum steady across jobs.
Building a FIRE-friendly portfolio around an S&P 500 trust
I center my FIRE portfolio on the Vanguard Institutional 500 Index Trust because it gives broad exposure to top U.S. companies at rock-bottom costs. However, I never put everything there.
A single fund misses mid-caps, small-caps, international stocks, and bonds. So I build around it with a simple setup. This keeps things diversified without constant tinkering, perfect when side hustles like freelancing or affiliate marketing eat up time. You stay invested and growing toward freedom.
The role of an S&P 500 fund in a simple three-fund style setup
The S&P 500 covers about 80% of U.S. stock market value through 500 large companies. It drives growth in my portfolio. Yet it skips smaller firms that often outperform over time.
I complement it with three other pieces for full coverage. First, add a total U.S. stock market fund or extended market fund. This grabs mid- and small-caps missing from the S&P 500. Next, include international stocks for global reach; about 20-40% allocation works for most. Finally, bonds or a cash alternative stabilize things based on your risk level.
Your time horizon guides choices. Early in FIRE, I go heavy stocks: 70% S&P 500 trust, 20% total U.S., 10% international. As retirement nears, bonds rise to 20-30%.
This setup beats single-fund risk. You capture U.S. growth while spreading bets worldwide.
Picking an asset allocation that matches your savings rate and timeline
High savings rates let you take more stock risk for faster growth. I save 50% of income, so I hold 90% stocks early on. Lower savers stick to safer mixes.
Behavior counts most. Heavy S&P 500 exposure builds wealth, but crashes test your nerves. If you sell low, gains vanish. Match allocation to what you can handle during drops.
Savings rate trumps tiny tweaks, especially at first. A 40% saver reaches FIRE quicker than a 10% saver, no matter the exact split. I review mine yearly: stocks drop near goal? Bonds cushion it.
For example, with 15 years left, I run 80/20 stocks/bonds. Shorter timeline? 60/40. Tools like Vanguard’s calculator confirm this fits your path. In short, align with your rate and stay put.
Automation that works for busy people with side hustles
Side hustles demand focus, so I automate investing. Paycheck contributions flow straight to the Vanguard Institutional 500 Index Trust and complements without thought.
Most plans offer this. Set percentage to each fund: 70% trust, 20% total market, 10% international. Rebalancing happens automatically if available; otherwise, do it yearly.
Here’s my simple process:
- Log into your plan portal.
- Choose funds and set percentages.
- Pick contribution amount or full deferral.
- Review once a year; adjust if life changes.
Consistency wins. I check annually while sipping coffee, then back to top freelance platforms for beginner side hustlers. No daily fuss means more time for income streams.
Sequence of returns risk: why S&P 500 heavy portfolios can feel scary near the finish line
Sequence risk hits when markets drop right as you retire. Early withdrawals from a falling S&P 500 trust lock in losses, delaying recovery.
I define it simply: returns order matters. Good years first build a buffer. Bad ones early shrink your nest egg forever.
Practical steps ease it. Build a cash buffer for 1-2 years spending. Add bonds as FIRE nears; they zig when stocks zag. Follow a glide path: cut stocks 1-2% yearly pre-retirement. Plan flexible spending too; trim in down years.
For details, see this sequence of returns explanation. I hold 5% cash now, bonds at 25% near goal.
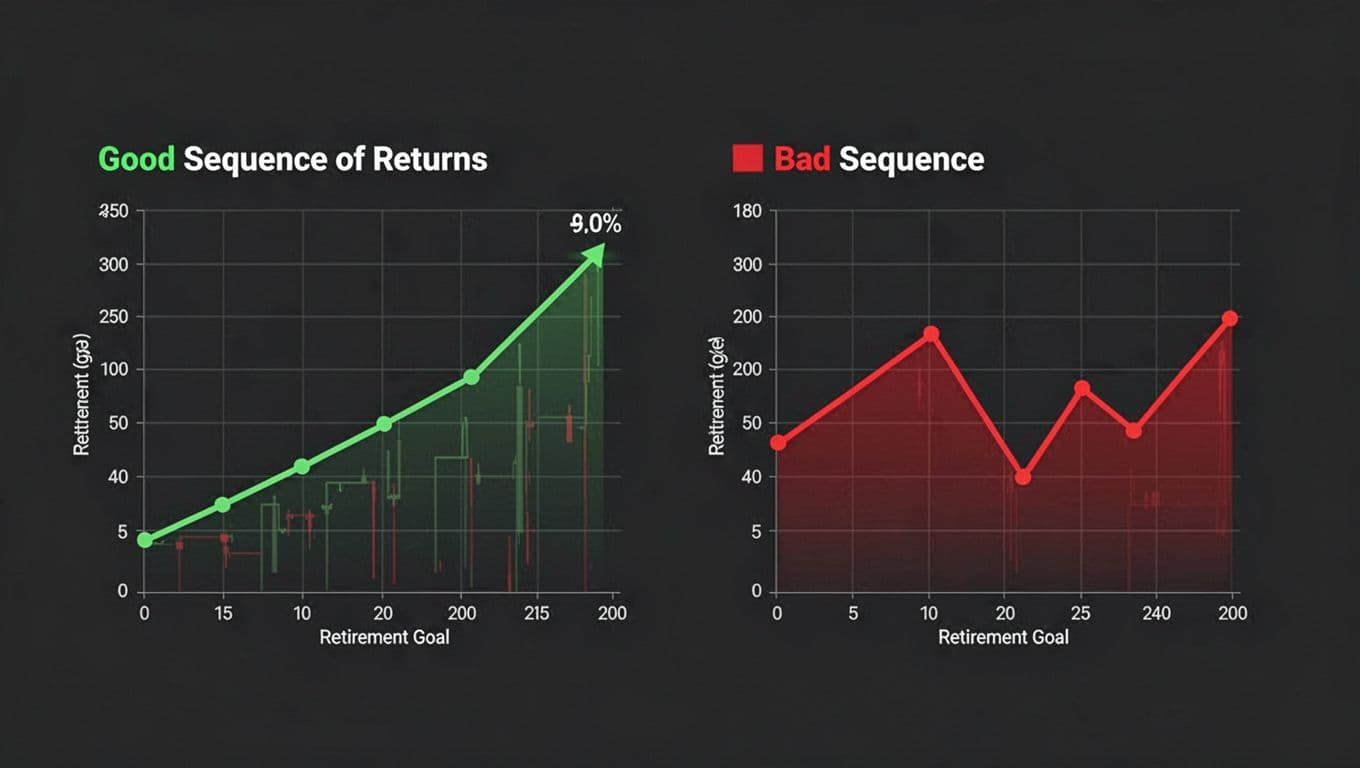
This keeps my plan steady. You sleep better knowing risks have fixes.
Common FIRE investor questions before choosing the Vanguard Institutional 500 Index Trust
Before I commit big chunks of my 401(k) to the Vanguard Institutional 500 Index Trust, I always run through these common questions. They help me weigh simplicity against risks in my FIRE plan. Many side hustlers ask the same things because employer plans limit choices. Let’s tackle them one by one so you can decide fast.
Is it safe to have most of my 401(k) in one S&P 500 option?
The Vanguard Institutional 500 Index Trust spreads your money across 500 large U.S. companies, so it offers built-in diversification. You avoid picking individual stocks, which cuts company-specific risks. However, concentration lingers at a higher level.
This fund stays U.S.-only, so it skips international markets. It also tilts toward large-caps, missing smaller firms that can boost returns over time. Stock market swings hit hard too; a broad downturn drags the whole S&P 500. For example, the index dropped 20% in 2022.
Early in FIRE, simplicity works fine if your plan lacks better options. I start heavy here because it grows fast. Later, add bonds or total market funds if available.
What if my plan offers a target-date fund too?
Target-date funds (TDFs) mix stocks and bonds, then shift safer as you near retirement. They offer convenience because you pick one based on your age. Many use indexes, so fees stay low, often 0.08% to 0.15%.
Compare that to a DIY setup with the Vanguard Institutional 500 Index Trust. The trust costs about 0.006%, but you build your mix manually. TDFs handle rebalancing; DIY demands yearly checks. If your TDF tracks indexes like the S&P 500, performance stays close, yet fees eat a bit more.
Go hands-off with a low-fee TDF if you hate tinkering, especially with side hustles pulling time. Choose DIY if the trust runs ultra-cheap and you want control over allocations.
How do I evaluate this option in five minutes inside my plan portal?
Quick checks confirm if the Vanguard Institutional 500 Index Trust fits your FIRE goals. Start in your portal’s fund list or search. Follow this checklist to spot winners fast.
- Find the fee: Look for expense ratio under 0.02% total, including plan adds. Check the fact sheet or 404a-5 disclosure.
- Confirm benchmark: It must track the S&P 500 exactly, not a custom blend.
- Review tracking: Compare 1-, 5-, and 10-year returns to the index. Lags over 0.05% yearly signal issues.
- Verify it’s broad: Ensure 500 stocks, full replication preferred.
- Spot extra fees: Note wrap fees or revenue sharing that bump costs.
- Check portfolio gaps: Does the rest of your plan cover bonds, small-caps, or global stocks?
If it passes, allocate heavily. I run this weekly at first, then yearly. For more, review a 401(k) evaluation checklist. This keeps your money working hard toward independence.
Conclusion
I choose the Vanguard Institutional 500 Index Trust in my 401(k) because it delivers S&P 500 exposure at ultra-low costs, often under 0.02% total, with tight tracking that compounds steadily toward FIRE. It fits perfectly when your job feels stable, your plan offers automation, and fees beat retail ETFs like VOO.
However, I pass if a job switch looms because rollovers create market gaps and hassle. In those cases, I shift to VFIAX or VOO in an IRA for seamless tracking.
If this trust stands as your cheapest S&P 500 play, max contributions now. Pair it with total market, international, and bonds for balance. This setup frees me to chase side income without daily portfolio worries. In short, it accelerates freedom when you stick to low-cost indexing.
Take these steps this week:
- Log into your plan portal and pull the 404a-5 fee disclosure.
- Confirm the trust’s total expense stays below 0.02% and tracking lags under 0.05%.
- Set your allocation: start with 70% trust, adjust for timeline.
- Automate payroll contributions to run hands-free.
- Mark your calendar for an annual review date.
Back to FIRE Investing Tips
Are you looking for better ways and tools to build your monthly revenue and brand? Be sure to check out our other resources located here to speed up the process.
Nathan
Dr. Nathan Pennington, DBA, earned his Doctor of Business Administration degree from the University of Missouri-St. Louis and brings over 15 years of online entrepreneurial experience in helping people learn how to blog, earn income online and build passive income streams outside of what the school system teaches.


