
Vanguard Global Aggregate Bond Ucits ETF for FIRE Investors

Disclosure: This post may contain affiliate links, meaning if you decide to make a purchase through my links I may earn a commission at no additional cost to you. See my disclosure for more info.
Build A Smarter Online Business
Want to turn your content into traffic, income, and long-term freedom? Start with the guides built to help you grow smarter.
Explore Online Business Guides →Stock swings can wreck a FIRE plan at the worst possible time, right before I retire or in the first few years of withdrawals. Even if my long-term return looks fine on paper, a bad early sequence can force me to sell shares at depressed prices, which locks in losses and shrinks what’s left to compound.
That’s where bonds earn their place. In plain terms, a bond fund often moves differently than stocks, so it can soften portfolio drops and give me a steadier pool to rebalance from when equities are down. It won’t eliminate risk, and it won’t always “go up when stocks go down,” but it can make the ride more manageable.
In this post, I’m focusing on the Vanguard Global Aggregate Bond Ucits ETF as a potential core bond holding for FIRE. I’ll walk through how it’s built (what it owns and what risks come with that), the practical trade-offs like hedged vs unhedged share classes, interest rate sensitivity (duration), and how I think about drawdowns when withdrawals begin.
I’ll also connect it to the other side of my FIRE plan, building income that doesn’t depend on market returns. A bond allocation can help, but I still like having cash flow from side work, especially during rough markets, and I’ve used ideas like these digital marketing side hustles to widen my options.
Everything here is for education and for sharing my process. I’m not giving personal financial advice, so I always double-check the fund docs, costs, and my own risk tolerance before buying anything.
Back to FIRE Investing tips
What the Vanguard Global Aggregate Bond Ucits ETF actually holds, and why that matters
When I buy the Vanguard Global Aggregate Bond Ucits ETF, I’m not buying “bonds” in the abstract. I’m buying a rules-based slice of the global bond market, packaged in a specific legal structure, with specific risk controls, and with a specific set of trade-offs that show up most clearly during stress.
At a high level, a global aggregate bond fund is a broad basket of investment-grade bonds (higher credit quality) across many countries and bond types. It typically includes government bonds, government-related issuers, and corporate bonds, across a range of maturities.
Because it tracks an index, it’s rules-based, meaning it owns what the index includes and in roughly the same proportions. That “boring” design is exactly why it can fit into a FIRE plan: fewer surprises, fewer big bets, and clearer knobs to adjust (currency hedging, duration, fees).
Ready To Build More Traffic And Income?
Use Internet of Business to learn blogging, SEO, affiliate marketing, passive income, and digital business systems that compound over time.
Start Building Your Digital Income →UCITS basics for FIRE investors outside the US
UCITS stands for Undertakings for Collective Investment in Transferable Securities. In plain English, it’s a European fund framework with strict rules around diversification, custody, and disclosures. For many non-US investors, UCITS ETFs are the easiest way to access broad, low-cost index exposure through local brokers.
Here’s why it matters for my FIRE setup:
- Broker access: Some brokers don’t offer US-domiciled ETFs to non-US clients, or they restrict them due to disclosure rules. UCITS often stays available across more platforms.
- Fund protections: UCITS has guardrails around how assets are held, how risk is managed, and how investors are treated if the provider runs into trouble.
- Tax handling can differ: The structure can affect withholding, reporting, and paperwork. I stay general here because it depends on where I live and how I hold it, but I always assume structure can change the tax outcome.
I also care about share class features because they change my day-to-day experience:
- Accumulating vs distributing: An accumulating share class reinvests bond income inside the fund. A distributing share class pays it out as cash. If I want hands-off compounding, I lean accumulating. If I want cash flow to help cover expenses, distributing can feel cleaner.
Before I buy, I run a quick factsheet checklist:
- Index tracked (and whether it’s investment-grade global aggregate).
- Share class: accumulating or distributing, plus the trading currency.
- Hedged or unhedged (and what currency it hedges to).
- Ongoing charges (fees matter more when yields are modest).
- Duration (my rate sensitivity dial).
- Credit quality mix (how much is government vs corporate, and overall ratings).
- Replication method (physical vs synthetic, I prefer physical for plain-vanilla bonds).
- Number of holdings and concentration (broad is usually better here).
Hedged or unhedged, how currency can help or hurt
Currency is the silent extra risk in global bonds. If the fund holds bonds in multiple currencies and I buy an unhedged share class, my return is a mix of bond returns plus currency swings.
A simple example: say the bonds in the fund return +3% in local terms. If my home currency strengthens 5% versus those currencies, my result in home-currency terms could end up around -2% (before fees). The bond portfolio did its job, but the currency move erased it.
That matters for FIRE because my future spending is in one main currency. Random FX swings can create a cash-flow problem right when I need stability. For that reason, a currency-hedged share class can make the bond portion act more like a shock absorber. It reduces the “noise” so the fund behaves more like bonds and less like a currency bet.
Still, hedging isn’t free. It can add costs, and it can change returns depending on interest-rate differences between currencies. So I treat hedging like insurance: useful, but not always necessary.
My rule-of-thumb decision framework:
- My spending currency is X, and I’m near or in withdrawals: I prefer hedged to X for most of my bond allocation.
- My horizon is long (10+ years) and bonds are a smaller stabilizer: I’m more open to unhedged, especially if I accept more month-to-month volatility.
- I’m building a “sleep well” bucket: I choose the version that reduces surprises, even if returns differ slightly.
Duration in plain English, the lever that drives rate sensitivity
Duration is “how sensitive the fund is to rate changes.” I think of it like the bond fund’s shock absorber length. A short absorber moves less. A long absorber moves more.
Here’s the simple scenario I keep in mind:
- If interest rates rise by about 1%, a fund with a duration near 7 might fall roughly 7% (ballpark, not exact).
- If rates fall by 1%, that same fund might rise roughly 7%.
That’s why longer duration can feel safe until it doesn’t. The bonds may be high quality, but rate moves can still hit hard. On the other hand, longer duration can also help during stock crashes, because rate cuts often show up in recessions. In those moments, duration can be the thing that gives me gains to rebalance into beaten-down stocks.
I also keep the other key terms tied to outcomes I care about:
- Yield: the income the portfolio generates, which affects how much cash flow I can expect (and how much “cushion” I have against price drops).
- Credit quality: higher-rated bonds tend to be steadier, while lower-quality bonds can drop when stocks drop.
- Fees: a small percentage drag that shows up every year, especially painful when yields are low.
This is why I check duration before I set my bond allocation. I don’t want my “stability” bucket acting like a second stock fund. To build that bucket faster, I focus on earning power too, and side income can help me keep buying even when markets look ugly, using options like these best freelance sites for beginner side hustlers.
Where this ETF fits in a FIRE portfolio, and where it doesn’t
In my FIRE plan, the Vanguard Global Aggregate Bond Ucits ETF isn’t here to “win.” It’s here to keep me from making the worst possible move at the worst possible time. I treat it like a stabilizer that helps me stick with my plan when stocks get ugly.
Bonds can play three jobs in FIRE, depending on the stage I’m in:
- Ballast: keep the portfolio from tipping too hard when stocks fall.
- Dry powder: give me something to rebalance from into cheap stocks.
- A spending buffer: cover withdrawals without forced stock sales.
If I’m also building side-hustle income, this bond sleeve matters even more. Extra cash flow reduces the pressure to sell. Meanwhile, bonds can cover the gap when business income dips or markets drop at the same time.
The big FIRE risk this helps with: selling after a market drop
Most people understand average returns. FIRE gets tricky because the order of returns matters once I start pulling money out. That’s sequence-of-returns risk.
Here’s a simple timeline example using round numbers. Imagine I retire with $1,000,000 and withdraw $40,000 a year.
Scenario A (bad early years):
- Year 1: Portfolio drops 25%, I still withdraw.
- Year 2: Drops again, I still withdraw.
- Years 3 to 10: Markets recover.
Scenario B (bad later years):
- Years 1 to 10: Markets do well, I still withdraw.
- Year 11: Big drop hits.
Both scenarios can have similar average returns over 10 or 15 years. Still, Scenario A can do far more damage because I’m selling shares after the drop, when each sale removes more future upside.
This is where a bond sleeve can earn its keep. If stocks are down, I want a “middle gear” that can fund spending for a while. In practice, I’m trying to buy time. I want to avoid turning a temporary stock drop into a permanent loss.
When I build that buffer, I usually think in terms of a few practical options:
- Bond ladder: Individual bonds maturing each year, matched to spending. This can feel clean, but it takes work, and it’s harder to diversify globally.
- Bond ETF (like the Vanguard Global Aggregate Bond Ucits ETF): Simple, diversified, and easy to rebalance. I accept that the price (NAV) moves.
- Cash buffer: Boring, stable, and psychologically calming. The trade-off is inflation risk and lower long-term return.
- A mix: Cash for the next 6 to 18 months, plus a bond ETF for the next few years.
My goal is simple: when stocks drop hard, I want a plan that doesn’t force me to sell them.
Stage-by-stage, here’s how I apply it:
- Accumulation: I don’t need a huge spending buffer yet, but I still like some bonds to smooth rebalancing.
- Coast FIRE: Bonds start to matter more because I’m less reliant on new contributions.
- Early retirement: This is where bonds pull the most weight because withdrawals are now real.
My simple “sleep at night” job for bonds, not a performance contest
I don’t buy broad bond funds to beat stocks. Stocks are my growth engine. Bonds are my shock absorber and my “planned spending” bucket.
That mental model keeps me from getting distracted when someone says “bonds are dead.” Bonds can have bad years, especially when rates rise. Yet the role stays useful because I’m not asking bonds to do everything. I’m asking them to reduce the odds of a panic sale.
A bond ETF like the Vanguard Global Aggregate Bond Ucits ETF can support a few FIRE goals at once:
- 1 to 5-year spending bucket: If I’m close to early retirement, I like having several years of expected spending in steadier assets, so a stock crash doesn’t dictate my life.
- Emergency fund supplement: I still keep cash, but bonds can be a second line of defense (with the warning that bonds can drop).
- Rebalancing source: When stocks fall, I may sell some bonds to buy stocks, rather than selling stocks to pay bills.
This is also where I address the “cash is safer” objection. Cash feels safe because the balance doesn’t move much. However, cash can quietly lose purchasing power. Bonds can also lose money, but they usually provide more income over time than a checking account, and they often behave differently than stocks.
The key is staying realistic:
- Bonds can drop when rates rise quickly.
- Credit spreads can widen during fear, which can pull prices down.
- Currency matters for global bond funds, which is why I take hedging seriously near withdrawals.
I’m not trying to predict interest rates. I’m trying to build a portfolio I can stick with while I keep earning. If I’m building extra income, for example with top side hustles for teachers in 2026, bonds help me avoid the trap of “I must sell stocks this month no matter what.”
If I want to double-check the specific fund details (share classes, hedging, distributions), I use the product page, like Vanguard’s listing for the Global Aggregate Bond UCITS ETF EUR-hedged share class.
When I’d skip it and choose something else
Even though I like a global aggregate bond ETF as a core bond holding, I don’t force it into every situation. Sometimes the right move is choosing a different tool.
I’d seriously consider skipping this ETF if:
- My time horizon is very short (months, not years). If I need the money next year for a home down payment, I don’t want duration risk.
- I need guaranteed principal on a specific date. An ETF can’t promise that, even if it holds high-quality bonds.
- I’m already heavy in rate-sensitive assets. If my portfolio already reacts strongly to rate moves, adding more duration can amplify the swings.
- I can’t tolerate NAV drops. If a 5% to 10% drawdown would cause me to sell, I should not pretend I’m fine with it.
In those cases, I prefer alternatives that better match the job:
- Cash or a cash buffer for near-term spending.
- Money market funds when I want stability and easy access.
- Short-term bond ETFs if I want less rate sensitivity.
- Inflation-linked bonds when inflation risk is the problem I’m solving.
- Higher equity allocation plus a larger cash buffer if I can handle stock volatility, but I want fewer moving parts.
I treat this choice as practical, not ideological. The point of FIRE investing is staying funded and staying calm, not proving a thesis on bonds.
How I compare this bond ETF to the other “safe” choices people use for FIRE
When people say they want the “safe” option for FIRE, they usually mean one of four things: no big drawdowns, easy access, some inflation protection, and no surprises. The catch is that you rarely get all four at once.
So I compare the Vanguard Global Aggregate Bond Ucits ETF to the other common safe choices by one simple idea: what job does this money need to do? Is it next month’s rent, the next 2 years of spending, or a long-term stabilizer I’ll rebalance from?
To keep myself honest, I like to lay the options side by side in a simple comparison table (cash or HYSA, money market funds, short-term government bond ETFs, inflation-linked bond funds, global aggregate bonds, plus “60/40” balanced funds).
Seeing volatility, inflation protection, yield stability, and interest-rate sensitivity in one place prevents “safety” from turning into a vague feeling.
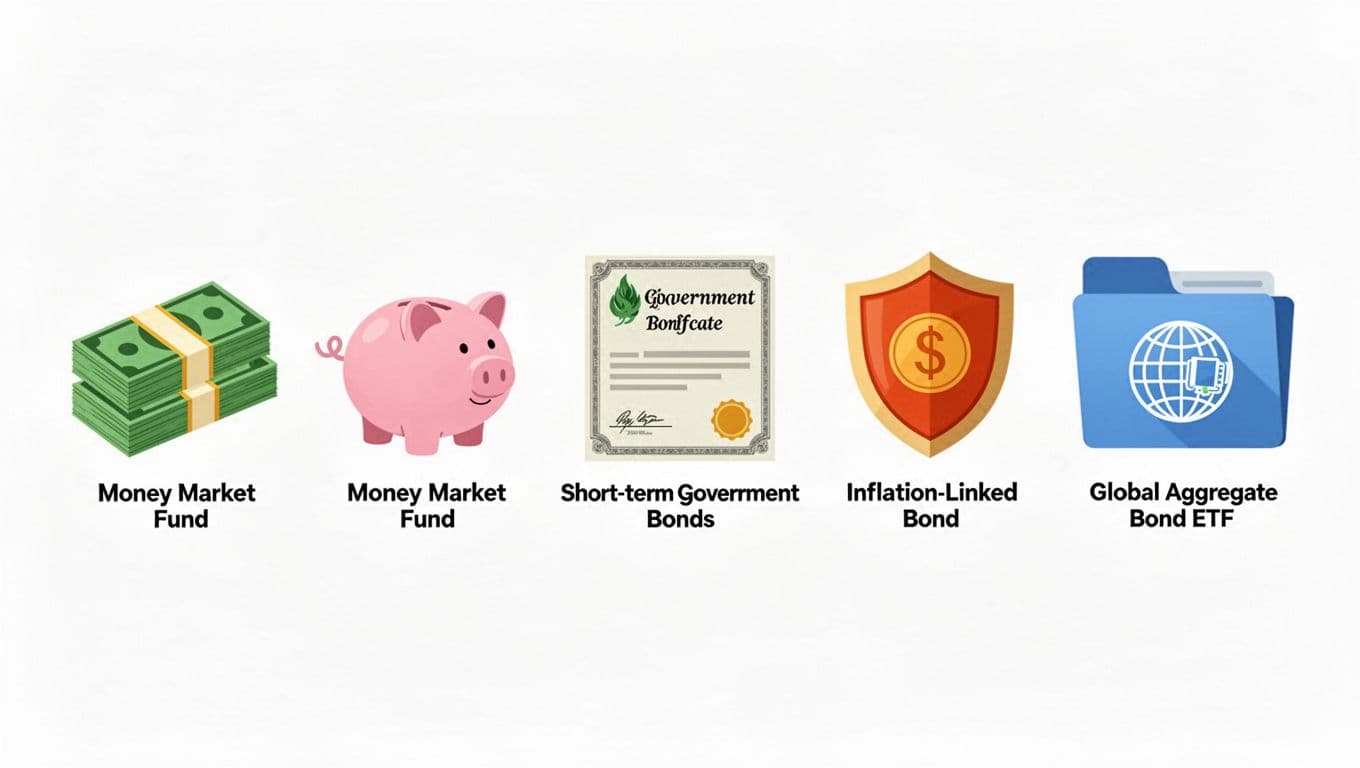
Bond ETF vs cash, why “no volatility” can still be risky
Cash feels safe because the number doesn’t move. That’s real value, especially when I’m stressed and want simple options. However, cash has a quiet risk that shows up later: purchasing power.
If inflation runs hotter than my savings yield, my cash buffer buys less every year. It’s like storing water in a bucket with a slow leak. Nothing looks wrong day to day, yet the level keeps dropping.
On the other hand, a broad bond ETF like the Vanguard Global Aggregate Bond Ucits ETF can pay more income than plain cash over time, and it can help when I rebalance during stock drops. Still, bonds show price swings, sometimes at the exact moment I wish they would not.
I also separate cash from money market funds in my mind. Both are used as “near-cash,” but money market funds can have changing yields and small risks tied to the holdings and rules in my country. They are usually stable, but they are not the same as a government-insured savings account.
Here’s my balanced take on when cash is the better tool:
- I need the money soon: Upcoming taxes, rent, a medical deductible, or a near-term move.
- My goal is emotional stability: Cash can stop me from panic-selling stocks during a bad month.
- I’m building my emergency fund: I want instant access and fewer moving parts (this fits well with setting clear savings targets like the ones I list in top things worth saving up for now).
For longer buffers, I’m willing to accept some bond volatility because inflation can do more damage than a small drawdown. I found this framing helpful when thinking about cash versus bonds, because it forces the question of what “risk” really means.
Cash protects me from price swings today. Bonds can protect me from needing to sell stocks tomorrow. The right pick depends on timing.
Global aggregate vs short-term government bonds, smoother ride vs better defense
Short-term, high-quality government bonds usually swing less when rates change. That’s because shorter maturities reset faster. In plain terms, they don’t get hit as hard when yields rise, and they don’t pop as much when yields fall.
So why not just use short-term government bonds for the whole “safe” side of a FIRE plan? Because safety has different flavors. A global aggregate bond fund can bring a broader mix:
- More diversification across issuers and sectors (not only one government curve).
- Potentially higher yield than ultra-short government-only exposure, depending on the market.
- A better chance of acting like a true “middle gear” between cash and stocks.
The trade-off is that a global aggregate fund often carries more interest-rate sensitivity than a short-term government bond fund. It can also behave differently based on credit spreads, and it may include corporates and global government bonds that do not move in lockstep.
This is where I use simple decision rules instead of trying to forecast rates:
- If I might spend the money within 1 to 3 years, I prefer cash, money markets, or short-term government bonds.
- If the money’s job is portfolio ballast for 5+ years, I’m more comfortable with the Vanguard Global Aggregate Bond Ucits ETF (especially in a hedged share class near withdrawals).
- If I know I’ll panic-sell after a 5% to 10% bond drawdown, I shorten duration, even if expected returns are lower.
I also keep one more “safe” option on my list: 60/40 balanced funds. They’re simple, and they can be fine for hands-off investors. Still, they are not a pure safe bucket. In a stock sell-off, a 60/40 can drop a lot more than people expect, because 60% is still stocks. I treat balanced funds as a full portfolio choice, not as my spending buffer.
What about inflation-linked bonds, do they solve the inflation problem
Inflation-linked bonds exist for a clear purpose: they aim to keep up with inflation by adjusting the bond’s value (and often the interest paid) based on an inflation index. If my biggest fear is rising prices, that sounds like the perfect fix.
The catch is that inflation-linked bonds don’t guarantee a smooth ride. Their prices can still fall, especially when real interest rates rise. In other words, even if inflation is high, the fund can drop if the market demands higher returns after inflation.
So I don’t treat inflation-linked bond funds as a total replacement for a broad bond fund. I treat them like a specialist tool that can sit next to a global aggregate bond ETF:
- Broad bond fund (global aggregate): steadier “all-purpose” ballast, usually better diversified.
- Inflation-linked bonds: targeted protection when I worry that inflation will crush my spending power.
- Cash and money market funds: liquidity and short-term certainty, even if inflation bites.
If I’m building a FIRE plan that has to survive both inflation spikes and equity bear markets, mixing tools often beats trying to find one perfect fund. The money’s job comes first, then I pick the product.
A practical due diligence checklist before I buy any bond ETF
Before I buy a bond ETF, I slow down and run a repeatable checklist. It keeps me from buying based on a headline yield or a recent chart. With something like the Vanguard Global Aggregate Bond Ucits ETF, the goal is usually stability and reliability, so small “details” matter more than people think.
I do this with two tabs open: the fund factsheet (or KID) and my broker’s order screen. Then I work top to bottom.
Fees, spreads, and tracking, the quiet costs that add up
TER/OCF is the fund’s ongoing annual fee, expressed as a percentage, and it comes out of returns automatically.
After that one-liner, I spend most of my time on the costs I actually feel when I click buy.
First, I check fund size (AUM) and basic liquidity signals. Bigger isn’t always better, but tiny funds can be harder to trade, especially in less active market hours. For small accounts, poor liquidity shows up as annoying fills and wider spreads.
Next, I look at:
- Bid-ask spread: the gap between what buyers pay (ask) and sellers receive (bid). I treat it like a hidden toll.
- Typical trading volume (if my broker shows it): low volume often means a wider spread.
- Tracking difference / tracking error: how closely the ETF matches its index after fees and trading costs. A cheap TER means little if tracking is sloppy. State Street’s overview of an ETF due diligence checklist is a useful reminder that the index and the fund’s real-world execution both matter.
Here’s the simple spread example I use, because it’s easy to underestimate.
If I buy $1,000 of an ETF and the spread is 0.40%, I give up about $4 right away (half on entry, half on exit is the common way to think about it, but either way the “gap” is real). If the TER is 0.10%, that’s about $1 per year on a $1,000 position. Trade a few times a year, and the spread can cost more than the annual fee.
That’s why I default to limit orders for ETFs. In plain language, a limit order lets me set the highest price I’ll pay (or the lowest I’ll accept when selling). It reduces the chance I get filled at a bad price when the spread is wide or the market is moving.
While I’m here, I also confirm:
- Trading currency (the currency the ETF trades in on my exchange).
- Base currency (often shown on the factsheet).
- Domicile (for UCITS, commonly Ireland or Luxembourg). Domicile can affect taxes and reporting, so I verify it against my local rules.
Distribution choice: do I want cash payouts or automatic reinvestment
For FIRE planning, the distributing versus accumulating choice is not just preference, it changes how hands-on I need to be.
- Distributing share classes pay interest income out as cash.
- Accumulating share classes reinvest income inside the fund, so my share count stays the same but the NAV reflects reinvestment.
In the accumulation phase, I like accumulating because it’s one less moving part. I don’t have to remember to reinvest small cash amounts, and I avoid cash drag.
In the drawdown phase, distributing can feel cleaner. Cash shows up, then I spend it. That said, I still keep a cash buffer, because bond payouts are not guaranteed month to month.
Taxes can differ by country and by account type, so I don’t guess. I confirm my local rules before choosing a share class.
Here’s the decision guide I actually follow:
- I’m still building (accumulation): I prefer accumulating, unless my broker can’t buy it cheaply.
- I’m near retirement and want simpler cash flow: I consider distributing, especially for my “spending buffer” sleeve.
- I’m already retired (drawdown): I choose the option that makes my tax and cash flow easiest, not the one with the prettiest yield number.
Right after that, I check whether the fund has a hedged share class in my home spending currency. If my goal is stability, I want bonds acting like bonds, not like an FX trade.
Credit quality and “safe enough” assumptions
Credit quality is where “bond ETF” can quietly turn into “stock-like stress behavior.”
At the highest level:
- Investment-grade bonds are higher-rated issuers (lower default risk).
- High-yield (junk) bonds pay more but can drop hard when fear spikes.
A global aggregate fund often skews investment-grade, but it still holds corporates and often securitized bonds (for example, mortgage-related exposure). Those can behave fine most of the time, then get hit when spreads widen.
So I verify, line by line, what the factsheet shows:
- Index tracked: I want the benchmark name, not just “global bonds.”
- Replication method: physical (full or sampling) versus synthetic. I prefer physical for plain bond exposure, and I want to know if it uses sampling because bond indices can be huge.
- Credit quality split: how much is AAA/AA/A/BBB, and whether any slice dips below investment-grade.
- Issuer and sector concentration: top issuers, government versus corporate, and how much sits in securitized sectors. Concentration is like loading one side of a backpack, it feels fine until you walk uphill.
- Duration: my quick interest rate sensitivity check.
- Yield measures: bond ETF factsheets may show yield to maturity (YTM), distribution yield, yield to worst, or a regional equivalent. SEC yield often won’t apply to UCITS, so I make sure I understand what the fund is quoting and whether it’s before or after fees.
This is also where I remind myself of the uncomfortable truth: bonds can crash. They don’t default in a broad investment-grade fund very often, but prices can fall fast when rates spike or when credit spreads jump.
Finally, I check the “boring” operational items that protect me from sloppy behavior:
- Rebalancing schedule: how often I plan to rebalance (for example, quarterly or annually), and what threshold triggers action.
- Behavioral risk: I don’t buy a bond ETF for yield alone, and I don’t panic sell after a rate spike. If I can’t hold through a 5% to 10% drawdown, I should shorten duration or hold more cash instead.
For another perspective on fixed income ETF metrics, Investing.com’s guide on how to evaluate fixed income ETFs is a solid cross-check when I want to confirm I’m reading the factsheet correctly.
How I’d use it with a side-hustle-first approach to FIRE
When my income comes from freelancing, blogging, or affiliate commissions, my biggest enemy is forced timing. A slow month can push me to sell stocks after a drop, which is the exact opposite of what I want in a FIRE plan. That’s where a core bond holding like the Vanguard Global Aggregate Bond Ucits ETF can earn its spot: not as “extra return,” but as a buffer that helps me stay consistent.
Using bonds as a buffer for irregular income months
Here’s the kind of month that used to mess with my head. My fixed bills hit either way, but my side hustle income can swing hard.
A simple example (round numbers):
- Monthly bills: $4,000
- Normal side hustle month: $5,000 (I invest $1,000)
- Slow month: $2,500 (I’m short $1,500)
If stocks are down 15% in that same slow month, selling equities to cover the gap is like selling the roof because it’s raining. Instead, I want a “middle bucket” I can tap without touching my long-term engine.
This is where I’d use a basic 3-bucket system:
- Emergency fund (cash): 3 to 6 months of essentials in a true cash account.
- Buffer bucket (bonds): a bond ETF sleeve, potentially including the Vanguard Global Aggregate Bond Ucits ETF, sized to cover irregular months and reduce stock-selling pressure.
- Growth bucket (stocks): the part I try hard not to disturb.
The key warning: a bond ETF is not a checking account. Its price moves, sometimes at the worst time. So I still keep a real emergency fund separate, because “I need rent money next week” is not the moment to find out bonds are down too.
If I want to sanity-check a specific share class (hedged, accumulating, and so on), I start with the Vanguard fund page for the Global Aggregate Bond UCITS ETF.
Rebalancing rules I can follow without staring at the market
Rebalancing sounds fancy, but I treat it like basic car maintenance. It keeps my risk from drifting when one asset runs hot or gets crushed. Most importantly, it can force buy low, sell high behavior without me trying to “feel” the bottom.
These are the simple methods I can actually stick to:
- Calendar-based (1 to 2 times per year): I pick two dates (for example, January and July). I rebalance back to my target percentages, then I stop thinking about it.
- Threshold bands: I rebalance only if an asset class drifts too far, like stocks move more than 5 percentage points away from target. It’s hands-off, but it still reacts when things get lopsided.
- Rebalance with contributions: in months when my side hustle overpays, I direct new money to whatever is underweight. That often fixes drift without selling anything.
My beginner-friendly version looks like this: I check allocations twice a year, I use contributions first, and only then do I sell something to top up what’s low.
Rebalancing is one of the few “buy low, sell high” systems I can follow without predictions.
If you want a deeper look at how buffer and rebalance approaches behave in retirement-style planning, AAII has a useful discussion in rebalancing vs buffer strategies.
A sample FIRE allocation thought process, not a one-size-fits-all portfolio
I don’t start with a “best portfolio.” I start with a few yes-or-no questions, then I pick a bond slice that matches my real life.
My plain-language decision tree:
- How soon is FIRE? (15 years vs 3 years changes everything.)
- How stable is my main job? (steady W-2 is different than contract work.)
- How reliable is my side hustle? (retainer clients vs ad revenue swings.)
- How do I sleep during drawdowns? (if I panic, the plan is wrong.)
Then I map that into simple personas:
- Early accumulator (20s to 30s, 10+ years to FIRE): I keep bonds smaller. I mainly want them for rebalancing discipline and a little calm.
- Near-FIRE (1 to 5 years out, side hustle income varies): I raise the bond slice and keep a clearer cash and bond buffer, because a bad sequence can hurt more now.
- Newly retired (first 5 years of withdrawals): I prioritize stability and spending coverage. If side hustle income can cover part of my spending, I may not need to sell much at all.
One last point matters more than people admit: earning power is a hedge too. When I grow skills and income streams, I reduce withdrawal pressure. Even seasonal work can help smooth cash flow, which is why I like having a short list of options like these winter side hustles for extra income when I want fast, practical ways to fill a gap.
Conclusion
The Vanguard Global Aggregate Bond Ucits ETF earns a spot in my FIRE plan because it does the boring jobs well. It gives me broad, rules-based exposure to investment-grade bonds across countries and sectors, and that breadth can smooth portfolio swings when stocks get rough. Most importantly, it helps me build a spending buffer, so I’m less likely to sell stocks after a drop.
At the same time, I don’t treat it like a guarantee. This ETF still carries interest-rate risk (duration can bite when yields rise), and the price can fall for long stretches. It can also lag stocks over time, which is fine, because I’m not buying it for maximum growth. I’m buying it for stability and better behavior during stress.
Before I buy or adjust my position, I keep the next steps simple:
- Define the job of bonds in my plan (ballast, rebalancing source, or spending buffer).
- Choose hedged vs unhedged based on my spending currency and how close I am to withdrawals.
- Pick distributing vs accumulating based on whether I want cash flow or auto-reinvestment.
- Confirm fees and duration, then decide if the risk matches the job.
- Set an allocation and a rebalancing rule I can follow (calendar-based or threshold bands).
Back to FIRE Investing tips
Are you looking for better ways and tools to build your monthly revenue and brand? Be sure to check out our other resources located here to speed up the process.
Nathan
Dr. Nathan Pennington, DBA, earned his Doctor of Business Administration degree from the University of Missouri-St. Louis and brings over 15 years of online entrepreneurial experience in helping people learn how to blog, earn income online and build passive income streams outside of what the school system teaches.


