
Living Simply and Frugally Tips

Disclosure: This post may contain affiliate links, meaning if you decide to make a purchase through my links I may earn a commission at no additional cost to you. See my disclosure for more info.
Build A Smarter Online Business
Want to turn your content into traffic, income, and long-term freedom? Start with the guides built to help you grow smarter.
Explore Online Business Guides →You check out at the grocery store and wince. That receipt shows $504 for your household this month alone, up from last year because prices rose 2.7%. Meanwhile, subscriptions pile up, and your home feels cluttered with stuff you rarely use. Sound familiar?
Living simply and frugally means just this: spend on what truly matters, cut the rest, and gain calm in the process. You focus on needs over wants. For example, families of four can trim to $1,000 monthly on groceries by smart choices, not sacrifice.
In this post, you’ll get practical tips that fit real life. No tiny house required. No extreme rules either.
Pick a few changes to try first, like meal planning or ditching one unused sub. Start small this weekend. You’ll save money and stress right away, even as grocery costs climb 2.3% to 2.5% next year. Ready to build that calm?
Back to Ways to Save Cash
Figure out what matters to you, so you stop spending on what does not
Living simply and frugally starts with clarity on your priorities. You gain peace of mind when you spend on goals that light you up, not random urges. Guilt fades away. Instead, you build habits around values like family time or personal growth.
Consider two friends. Sarah saves for trips because travel recharges her. She skips daily lattes but books one adventure a year. Tom values home life, so he invests in a solid kitchen setup for cooking with kids. He rarely eats out. Both live simply in their own ways. Their choices cut stress and boost joy.
This mindset fights lifestyle creep, where raises lead to bigger spends. About 40% of Americans overspend to keep up, and many high earners live paycheck to paycheck. You can break that cycle. Focus on your “enough” line first. Then apply simple tools to trim fat. As a result, you free up cash for what counts.
Try a quick “keep, cut, change” list for your spending
Grab a notebook or app. List your top 10 monthly spending areas, like groceries, coffee runs, or streaming services. Next to each, decide: keep it, cut it, or change it.
Ready To Build More Traffic And Income?
Use Internet of Business to learn blogging, SEO, affiliate marketing, passive income, and digital business systems that compound over time.
Start Building Your Digital Income →Keep high-joy, high-use items. That might mean your gym membership if you go weekly and love the energy boost.
Cut low-joy, low-use stuff. Unused gadgets or impulse buys top this list. Toss subscriptions you forgot about.
Change needs you can meet cheaper. Switch name-brand snacks for store versions, or cancel cable for free apps.
Start with one category to avoid overwhelm. Groceries work well because they hit hard, up 25-30% lately. Review last month’s statements. Mark changes right away. You might save $50 fast. Small wins build momentum for bigger shifts.
Know your “enough” line and stop chasing upgrades
Lifestyle creep sneaks in as income grows. You upgrade phones yearly or swap decor for trends. Perfectly good items get replaced too soon. Meanwhile, 57% of low earners and even $500,000+ folks feel broke.
Define your enough line. Ask what serves you now. A reliable phone lasts three years. Replace only when broken, or if it saves time long-term, like a tool that cuts chores.

Photo by Dany Kurniawan
For example, skip the new couch if yours works. Save raises instead; banking 25% could grow to millions over decades. Non-essentials eat 20-35% more now, with debt straining budgets. Pause before upgrades. Does it align with your goals? Often, no. You keep calm and cash.
Make room for fun without blowing your budget
Frugal life stays fun. You just pick low-cost joys. Host potlucks where friends bring dishes. Check free community events like concerts or markets. Game nights beat pricey outings.
Libraries offer books, classes, and movies at zero cost. Hiking trails provide adventure nearby. Streaming shared accounts cut bills too.
Before buying fun gear, ask these questions:
- Will I use it 10 times this year?
- Can I borrow or rent it?
- Does a free option work just as well?
These choices fit any budget. You laugh more without regret. In short, align fun with values. Peace follows.
Set up a budget you will actually use in real life
Living simply and frugally works best with a budget that fits your routine. You skip complicated spreadsheets. Instead, you create a simple plan that tracks cash flow and curbs waste. This setup frees you from money worries. As food costs climb in 2026, these steps help you stay ahead. Best part? It takes little time each week.
Start with a “two number” budget: must pays and flexible spending
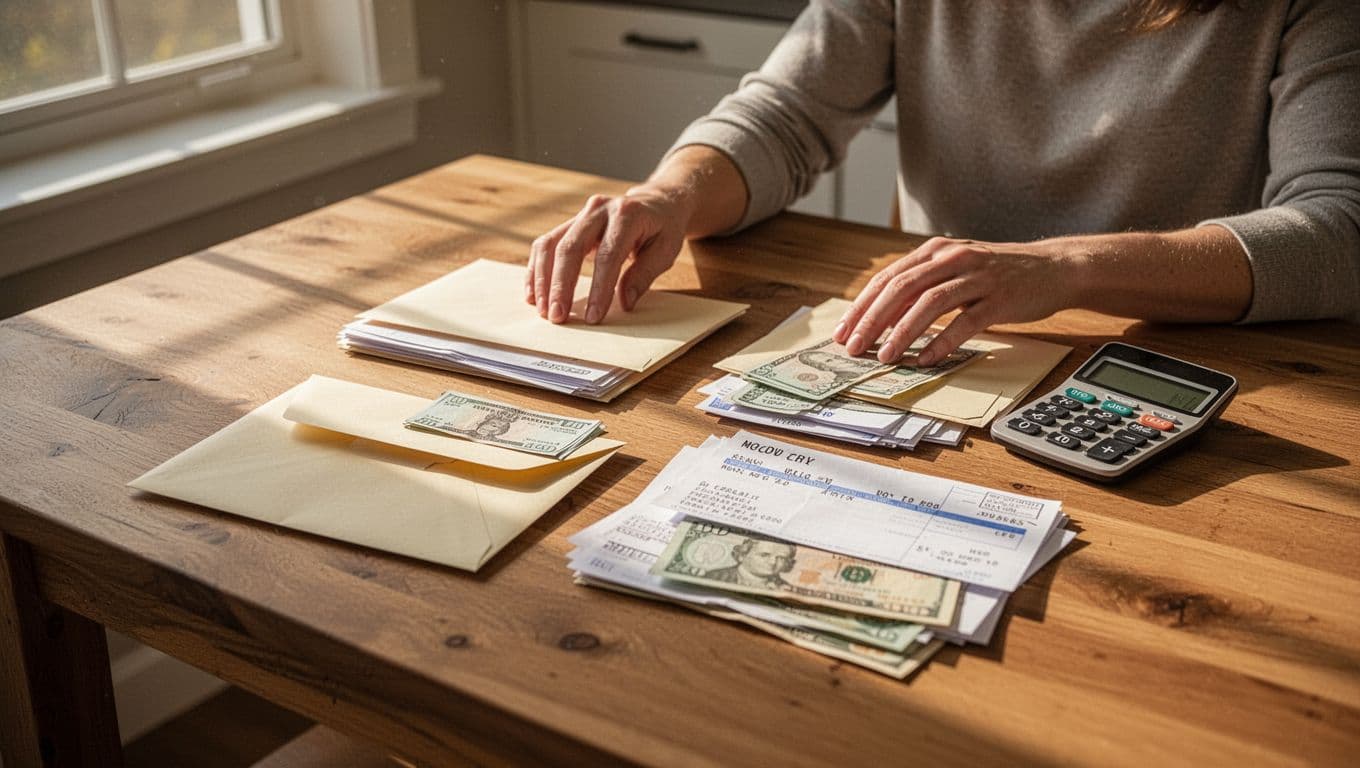
Divide your money into two buckets. First, cover must-pay bills like rent, utilities, and minimum debt payments. Second, handle flexible spending for groceries, gas, and fun.
Take a $4,000 monthly paycheck as an example. List must-pays first: $1,500 rent, $300 electric, $200 car payment, $400 groceries minimum, and $100 insurance. That totals $2,500. You have $1,500 left for flexible spending.
However, build in a buffer. Set aside 5% or $200 for surprises like car repairs. This keeps you calm when unexpected hits occur. Adjust as needed each month. You gain control fast.
Use a weekly money check-in to stay on track
Set a 15-minute routine each Sunday. First, check account balances. Next, scan recent transactions for surprises.
Then, move extra cash to savings. Finally, plan the week’s flexible spending. Use one spot to track, like your bank app or a notebook. Set a calendar reminder so you never skip it.
This habit gives freedom. You spot overspends early, like extra snacks amid rising food prices. Check spending weekly, then adjust the full budget monthly. In short, you stay flexible without stress.
Cancel subscriptions you forgot about and stop silent spending
Forgotten subs drain cash. Americans average $219 monthly on them, or $2,628 yearly, but waste $200 on unused ones. You hold about 5.4 on average, with streaming leading the pack.
Follow this cleanup every three months:
- Pull bank and card statements.
- Spot trials that auto-charged or forgotten apps.
- Cancel overlaps, like multiple cloud storage.
- Downgrade plans, such as basic streaming tiers.
- Rotate services monthly, like one video app at a time.
Common culprits include streaming, phone apps, delivery memberships, and beauty boxes. This stops silent spending. As a result, you reclaim cash for real needs.
Automate the basics so you do not rely on willpower
Set up auto-pay for fixed bills right away. Banks handle rent or utilities on time. You avoid late fees.
Next, schedule transfers to savings the day after payday. Start small, like $100 weekly. This builds your buffer without thinking.
Keep enough in checking, though. Aim for one month’s must-pays. Review automations after pay raises or cuts. Therefore, you protect against errors. Living simply and frugally becomes effortless.
Cut your biggest costs first, without feeling deprived
You save the most when you target big expenses like food, transportation, and utilities. These areas eat up 50-60% of many budgets. Yet, you cut them smartly without skipping favorites or feeling pinched. Living simply and frugally shines here because small tweaks add up fast.
For instance, families trim groceries from $1,500 to $1,000 monthly on thrifty plans. Gas at nearly $3 per gallon hurts too, but fewer trips help. Meanwhile, old habits slash utility bills 10-20%. Start with these changes. You keep comfort while cash grows.
Lower your grocery bill with meal planning that is not complicated
Meal planning cuts waste and impulse buys. You spend less because you shop with purpose. Families save $200-500 monthly this way, even as food prices rise 2.3% next year.
Pick a simple method. First, check your pantry. List staples like rice, beans, or canned goods. Next, choose 2-3 easy dinners, such as stir-fry, pasta, or sheet-pan chicken. Plan leftovers for lunch. Build your list from there. Add fresh items last.
Here is how it works in practice:
- Scan pantry Sunday morning.
- Pick dinners: Monday stir-fry with rice, Tuesday pasta, Wednesday chicken.
- Note leftovers for Thursday and Friday.
- Write the shopping list. Stick to it.
Cook at home more often. You avoid takeout markups. Shop after eating to skip snack urges. Compare unit prices on shelves; ounces per dollar matter. Grab store brands; they match quality 90% of the time. Finally, end the week with a “use it up” meal. Toss odds like veggies or bread into soup. No waste, full bellies.
In short, this routine frees cash. You eat well without stress.
Spend less on transportation by driving less and maintaining what you have
Transportation costs add up quick, especially with gas near $3 per gallon. Yet, you trim 20-30% without selling your car. Combine habits for real savings. Renters and owners both benefit.
Batch errands first. Hit the store, bank, and post office in one trip. Carpool to work or school when possible. Use public transit for city runs. Walk or bike short distances under two miles. These steps cut fuel use right away.
Maintain basics too. Keep tires inflated; it boosts mileage 3%. Change oil on schedule to avoid breakdowns. Shop insurance yearly; rates drop with good records or bundles. When gas spikes, skip unnecessary drives like extra coffee runs.
As a result, your wallet stays fuller. You drive smarter, not less.
Reduce utility bills with old-school habits that still work
Utilities run steady, but tweaks lower them 10-20% for most homes. Small changes stack up because they target daily use. Renters adjust thermostats; owners add habits like these.
Hang dry laundry a few times weekly. It saves on dryer cycles. Adjust your thermostat 2-3 degrees; you barely notice but save big. Run cold-water washes for clothes. Unplug chargers or devices not in use; they suck power quietly. Take shorter showers by five minutes.
These fit any home. No big buys needed. Track one bill monthly to see gains. Therefore, you pocket extra without cold rooms or stiff clothes.
Above all, consistency wins. Your bills drop, life stays cozy.
Buy less, but buy smarter when you do spend
You build a frugal life when you cut purchases that lead to clutter and regret. Smart buying means you pick quality over quantity. Therefore, you avoid “deal” traps that fill drawers with junk. For example, that $10 kitchen gadget breaks fast and costs more in replacements. In contrast, one solid pan lasts years. About 45% of folks regret impulse buys, with 33% backing out in 24 hours. Living simply and frugally gets easier because you own less but enjoy more.
Use a waiting rule to stop impulse buys
Impulse buys hit hard. You spot a sale and click “buy now.” Yet, most wants fade quick. Set a simple rule: wait 24 hours for items under $50, or 7 days for anything pricier. This pause kills 51% of urges from millennials and Gen Z.
Save links first. Use your phone’s notes app or a wishlist. Add the item, note the price, and set a reminder. Re-check later. Often, you forget why you wanted it. One person saved $300 in a month this way by skipping extra water bottles. As a result, your home stays clear, and cash stays put.
Avoid cheap items that break fast and cost more later
Cheap stuff tempts you with low prices. However, it breaks quick and costs more over time. Buy once, cry once: spend up front on quality, then forget replacements. Sturdy shoes last seasons, not months. A good winter coat handles years of cold. Basic tools like hammers or screwdrivers take daily use without fail. Cookware, such as a thick cast-iron skillet, cooks better and outlives thin pans.
Cheap works fine for low-use items, like holiday decor or party cups. There, you toss without worry. But for daily needs, quality wins. Picture replacing sneakers three times a year at $30 each versus one pair at $90 that lasts two years. You save cash and space.
Borrow, rent, or buy used before you buy new
New items shine in stores. Still, you get most needs without full price. Check your library for books and movies first; it’s free. Tool libraries lend drills or ladders if available locally.
Ask friends to borrow lawn mowers or camping gear. Join buy-nothing groups on apps or Facebook for free hand-me-downs. Thrift stores offer clothes and housewares at fractions of retail. Facebook Marketplace turns “used” into steals like bikes or furniture.
You save big this way. Impulse spending dropped to $151 monthly lately, thanks to smart secondhand hunts. Always buy new for safety items like car seats or helmets; used ones risk failure. Test electronics before buying. In short, borrow or thrift builds your frugal habits without skimping on life.

Photo by cottonbro studio
Stop buying single-use gadgets and duplicates in your home
Single-use gadgets pile up fast, like avocado slicers or egg cubers. You buy one, use it twice, then regret the clutter. Duplicates waste space too: three peelers when one works fine. Focus on kitchen basics. Get one sharp chef’s knife, one versatile pan, and one spatula set. These handle 90% of tasks.
Do a quick drawer audit. Pull everything out. Keep what you use weekly. Donate or sell the rest. Apply a “one in, one out” rule for small spaces. Want a new blender? Ditch the old one first. Therefore, your home feels open, not jammed. 36% of Americans call most buys unplanned; break that with this check. You live lighter and spend less.
Build simple routines that keep you frugal all year
Living simply and frugally lasts when you build easy routines. Motivation fades, but systems stick around. You create habits for money checks, home care, and bill planning. These keep clutter low and cash steady. Best of all, they take little effort. Pick one to start this month. You’ll feel the calm build over time.
Do a monthly reset: money, meals, and calendar
End each month with a quick reset. This routine reviews your budget, plans meals, spots upcoming costs, and sets a goal. It takes 30 minutes tops. You stay ahead without stress.
First, pull up bank statements. Check what you spent against your plan. Note wins like lower grocery tabs. Adjust next month’s numbers based on real life.
Next, scan the calendar. Flag birthdays, school fees, or annual bills. For example, note car insurance renewals or holiday prep.
Then, plan three to five meals. Use pantry staples for basics like pasta or soup. This cuts shopping waste right away.
Finally, pick one goal. Maybe save $20 extra or declutter a shelf. Write it down. Therefore, you end strong and start fresh.
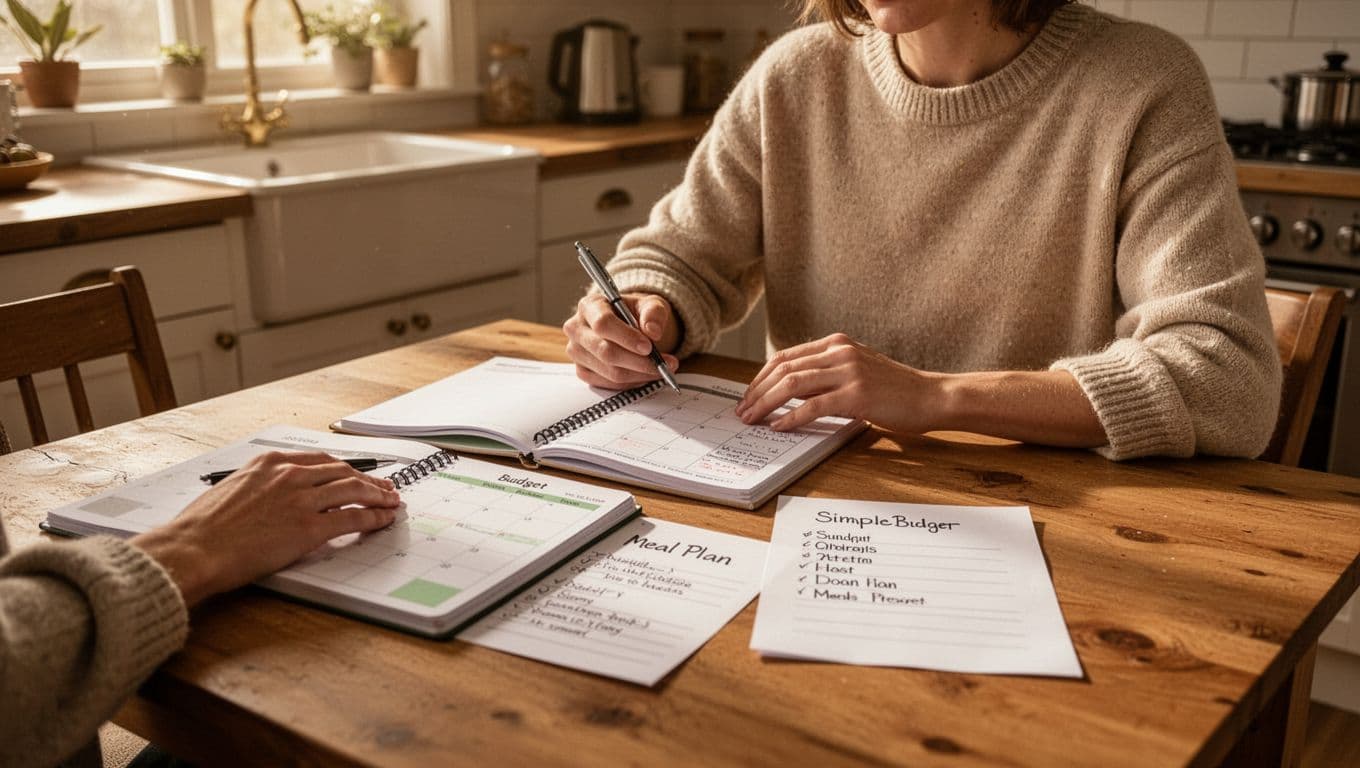
In short, this reset keeps living simply and frugally on track. You avoid surprises because you plan ahead.
Declutter in small chunks so your home stays easy to manage
Clutter leads to extra spending. You forget that blue shirt in the drawer, then buy another. Small sessions fix this fast. Aim for 10 to 15 minutes, one spot at a time. Pick a drawer or shelf daily.
Sort into three piles: keep, donate, sell, recycle. Keep only what you use often and love. Donate clothes or books to local spots. Sell workable items on apps for quick cash. Recycle the rest.
A simple rule helps: if you have not touched it in a year, let it go. This clears space and your mind. As a result, your home stays light. You shop less because you know what you own.
Besides, maintenance like this beats big cleanups. Your space supports frugal habits year-round.
Repurpose what you already have before you shop
Look around first before you buy. Repurposing saves cash and cuts waste. It keeps things realistic, no fancy projects needed.
Turn glass jars into pantry storage for pasta or spices. Cut old towels into cleaning rags; they work better than paper ones. Pack leftovers into lunches the next day. Rearrange furniture for a fresh room look instead of new decor.
These swaps add up. You skip store trips for small needs. Meanwhile, your home feels organized. Try one idea weekly. You’ll notice the difference fast.
Above all, this habit builds confidence. Wondering how to live simply and frugally? You live simply and frugally with what sits right there.
Plan for “not monthly” expenses so they do not wreck your budget
Irregular costs like car repairs or holidays sneak up. They hit hard, often $1,000 to $2,500 for fixes alone. Sinking funds fix this. You set aside small amounts each month into separate pots. No debt needed.
Start with basics. Save $50 monthly for car repairs, since many pull that from savings yearly. Add $40 for holidays, $20 for back-to-school supplies, and $15 for annual subscriptions. Total stays under $200.
Use a high-yield savings account. Label each fund clearly. Automate transfers after payday. Check progress quarterly. For example, $50 times 12 covers most repair surprises.
This system beats scrambling. You cover 72% of common setbacks without worry. In addition, add 5% extra as prices rise. Therefore, your budget stays solid all year.
Conclusion
Living simply and frugally means you pick what matters most, then build habits that make those choices easy every day.
You started with that wince at the grocery receipt and piles of unused stuff. Now you have tools to trim subscriptions, plan meals, cut big costs, buy smarter, and reset monthly. Small shifts like these stack up. Families drop grocery bills by hundreds. You pocket more cash and gain calm amid rising prices.
Start today with three quick wins. Cancel one forgotten subscription; it reclaims $20 or so right away. Plan two simple meals to slash impulse buys. Set up your weekly money check-in Sunday mornings.
These actions fit any routine. You see results fast, without big sacrifices.
Back to Ways to Save Cash
Are you looking for better ways and tools to build your monthly revenue and brand? Be sure to check out our other resources located here to speed up the process.
Nathan
Dr. Nathan Pennington, DBA, earned his Doctor of Business Administration degree from the University of Missouri-St. Louis and brings over 15 years of online entrepreneurial experience in helping people learn how to blog, earn income online and build passive income streams outside of what the school system teaches.


