
How to Invest 2 Million for Retirement

Disclosure: This post may contain affiliate links, meaning if you decide to make a purchase through my links I may earn a commission at no additional cost to you. See my disclosure for more info.
Build A Smarter Online Business
Want to turn your content into traffic, income, and long-term freedom? Start with the guides built to help you grow smarter.
Explore Online Business Guides →Imagine you’ve just hit your goal: $2 million saved for retirement. You’re ready to quit work, but a nagging doubt hits. Will this nest egg cover 30 years of living, especially with costs climbing?
In 2026, inflation sits around 2.4% to 3%, and it could push higher due to tariffs and strong jobs. For an average US couple, yearly expenses run $50,000 to $60,000 on basics like housing, food, and travel. Yet many need $60,000 to $100,000 if they want comfort, plus over $300,000 in lifetime healthcare costs that keep rising faster than Social Security.
That’s why how to invest 2 million for retirement matters now. Poor choices let inflation eat your savings; smart ones grow it to beat rising prices.
In this post, you’ll learn key steps. First, assess your real needs and timeline. Next, use tax strategies like Roth conversions to cut bills. Then, diversify across stocks, bonds, and more for steady growth. We’ll cover withdrawal rules to avoid penalties, and common pitfalls that trip people up.
Follow this plan, and your $2 million can stretch 30+ years or more. Let’s get started.
Back to Ways to Save Cash
Start by Calculating Your True Retirement Needs
You hold $2 million for retirement, but does it fit your life? Start here because how to invest 2 million for retirement begins with knowing your real costs. Track spending now, then project ahead with inflation. Plan to age 95 for safety. A modest lifestyle might make $2 million last; luxury travel or big homes could fall short. Simple calculators or Monte Carlo tools help test scenarios.
Track Your Spending and Add for Inflation
Grab a notebook or app today. Log every expense for three months. Coffee runs count too.
Next, categorize them. Housing often tops the list at 30-40% of spending. Food, utilities, and travel follow. For US couples, Schwab data shows $60,000 to $100,000 yearly on average after basics.
Ready To Build More Traffic And Income?
Use Internet of Business to learn blogging, SEO, affiliate marketing, passive income, and digital business systems that compound over time.
Start Building Your Digital Income →Then, add inflation. Use 3-4% to stay safe. Tools like Vanguard’s retirement calculator make this easy.
Follow these steps:
- Download a tracker app like Mint or PocketGuard. Link your accounts.
- Review bank statements weekly. Note cash too.
- Group into buckets: housing, food, healthcare, travel, fun.
- Calculate monthly total. Say you spend $5,000 now. At 3% inflation over 20 years to retirement, it hits $9,025. Over 30 years, expect $12,300 monthly or $147,600 yearly.
- Run projections. Free Monte Carlo simulators on Fidelity’s site test if $2 million covers it 90% of the time.
For example, $80,000 yearly today becomes about $120,000 in 20 years at 3%. Your $2 million supports a 4% withdrawal of $80,000 initially. Adjust investments later to match.
Budget for Healthcare and Long-Term Care
Healthcare eats 15% of retirement budgets. Medicare covers basics from age 65, but gaps loom large. Dental, vision, hearing aids, and most copays stay out-of-pocket. Long-term care like nursing homes? Medicare skips it entirely.
Plan $315,000 to $366,000 for a couple retiring at 65, per Schwab and Fidelity updates. That’s premiums, deductibles, drugs, and more through life expectancy. Chronic issues push higher.
Income affects Part B and D costs. Check this 2025 table (similar for 2026):
| Income (Single) | Income (Married Joint) | Part B Monthly (2025) | Part D Extra (2025) |
|---|---|---|---|
| $106,000 or less | $212,000 or less | $185 | Plan premium only |
| $106,001-$133,000 | $212,001-$266,000 | $259 | + $13.70 |
| $133,001-$167,000 | $266,001-$334,000 | $370 | + $35.30 |
| $167,001-$200,000 | $334,001-$400,000 | $480.90 | + $57 |
| $200,001-$499,999 | $400,001-$749,999 | $591.90 | + $78.60 |
Buy Medigap or Medicare Advantage to fill holes. Add long-term care insurance early; premiums rise with age. HSAs let you save tax-free up to $8,750 for families in 2026.
In short, bake in these costs. Your $2 million shrinks fast without them. Test with online tools for peace of mind.
Put Your Money in Tax-Advantaged Accounts First
You have $2 million ready for retirement. Before chasing stocks or bonds, park as much as possible in tax-advantaged accounts. These spots let your money grow without Uncle Sam taking a big cut each year. As a result, how to invest 2 million for retirement starts here. You keep more compound interest working for you.
Most people near retirement hold funds in taxable brokerage accounts, traditional 401(k)s, or IRAs. Shift them wisely to cut taxes over decades. For example, roll over old 401(k)s into IRAs for better control. Max new contributions too. In 2026, aim for these limits if eligible.
First, tackle the withdrawal order for tax smarts. Pull from taxable accounts upfront. They use lower capital gains rates. Next, tap traditional 401(k) or IRA funds. Save Roth for last. This keeps tax-free growth alive longest.
A $2 million nest egg shines here. Tax drags can eat 20-30% otherwise. Smart moves save thousands yearly. Let’s compare top options next.
Roth IRA vs Traditional 401(k): Which Fits You?
Near retirement, pick based on your tax now versus later. Traditional 401(k)s defer taxes. You contribute pre-tax, up to $24,500 in 2026 if under 50.
Over 50-59? Add $8,000 catch-up for $32,500 total. Ages 60-63 get $11,250 super catch-up, hitting $35,750. Roth IRAs grow tax-free. Limits sit at $7,500 under 50, or $8,600 with catch-up over 50. Income caps apply for direct Roth contributions.
For you close to quitting work, Roth often wins. Pay taxes upfront at lower rates. Withdrawals come tax-free after 59½ and five years. No required distributions force sales in down markets.
Here’s a quick side-by-side:
| Feature | Roth IRA | Traditional 401(k) |
|---|---|---|
| Contributions | After-tax, income limits | Pre-tax, higher limits |
| Growth | Tax-free | Tax-deferred |
| Withdrawals | Tax-free (qualified) | Taxed as income |
| RMDs | None during life | Start at 73 |
| Best for Near Retirement | Tax-free income later | If expect lower tax bracket in retirement |
Roth pros:
- Tax-free withdrawals match your $80,000 yearly need from $2 million at 4%.
- Heirs inherit tax-free.
- No RMDs keep flexibility.
Roth cons:
- Upfront tax hit.
- Lower contribution limits.
Traditional 401(k) pros:
- Bigger contributions now.
- Lowers current taxes.
Traditional cons:
- Taxes hit on every withdrawal.
- RMDs force outflows.
Roll overs help switch. Move 401(k) to Roth IRA via conversion. Pay tax on the amount shifted. Do it gradually to fill low brackets.
Real savings? Say you convert $50,000 yearly for five years from traditional funds. Pay about $4,000 tax each time. Later, skip $8,500 yearly taxes on withdrawals. Over 20 years, save $150,000 plus extra growth. Bigger $100,000 conversions save $10,000 annually long-term. Run your numbers; it pays off big for $2 million portfolios.
Diversify Your $2 Million Across Smart Assets
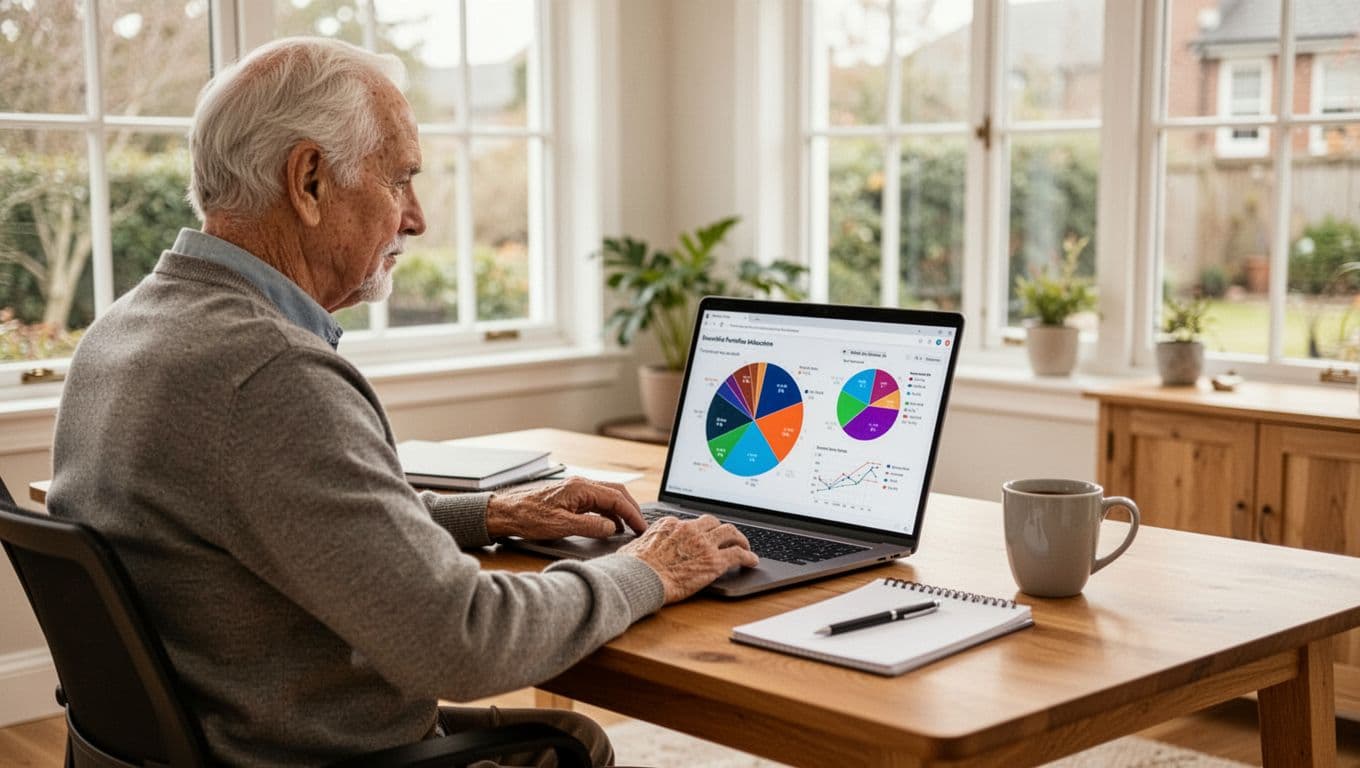
You hold $2 million for retirement. Now spread it smartly to grow and protect it. All cash loses to inflation at 2.4-3% in 2026; it buys less each year.
Instead, mix stocks for growth, bonds for safety, and real estate for hedges. For ages 60+, start with 50-70% stocks if retiring early, then shift to more bonds. Global diversification cuts risks from one market. Target-date funds auto-adjust this mix too.
Here’s a sample $2 million portfolio by phase. Adjust based on your needs.
| Phase | Stocks/ETFs | Bonds/CDs/Annuities | Real Estate/Alternatives | Total |
|---|---|---|---|---|
| Early (55-60s) | 50% ($1M) | 40% ($800k) | 10% ($200k) | $2M |
| Steady (60s-70s) | 60% ($1.2M) | 30% ($600k) | 10% ($200k) | $2M |
| Later (70+) | 40% ($800k) | 50% ($1M) | 10% ($200k) | $2M |
This setup yields 3-5% income while beating inflation. How to invest 2 million for retirement gets easier with low fees and steady payers.
Stocks and Dividend ETFs for Growth and Income
Stocks power long-term growth. Low-cost index funds beat most pickers over time. For example, S&P 500 trackers average 10% yearly returns historically.
Dividend ETFs add income without selling shares. SCHD yields 3.8-4%, VYM around 2.5%, and DGRO 2-2.2%. These payers grow dividends 10% per decade. Put 30-50% here early on. Rebalance yearly to stay on track. As a result, your $1 million in stocks could throw off $30,000-$50,000 yearly. Global funds like VXUS add worldwide exposure.
Bonds, CDs, and Annuities for Steady Paychecks
Bonds offer safety. The 10-year Treasury yields about 4% now. CDs and high-yield savings hit 4-5% too. Lock in rates before they drop.
Annuities guarantee paychecks. A 65-year-old puts $500,000 in a single-life SPIA and gets $29,500-$30,000 yearly for life, around 6% payout. No market worry; insurers back it. However, shop A-rated firms. Allocate 20-40% here for basics like $50,000 yearly needs. In addition, ladders mature CDs every year for steady cash.
Real Estate and Alternatives to Beat Inflation
Real estate fights rising prices. REITs yield 4.3-5% with rent hikes. They trade like stocks, no landlord hassles. Direct rentals bring higher returns but eat time; skip them unless hands-on.
Alternatives shine in 2026. MLPs offer 6-8% distributions from energy. Farmland and gold hedge inflation too. Target-date funds mix these in. Aim for 10-20% total. REITs suit most.
Set Up a Withdrawal Plan That Keeps Your Nest Egg Safe
Your $2 million sits diversified across stocks, bonds, and real estate. Great setup. Now you need a withdrawal plan to make it last 30 years or more. How to invest 2 million for retirement includes pulling money safely without running dry.
Start with the classic 4% rule. It suggests you take $80,000 in year one, then adjust for inflation each year after. This approach fits many plans, but tweak it for today’s markets. Bonds yield less, stocks look pricey, and lives run longer. Safer rates like 3-3.5% build in buffers.
Why the 4% Rule Works and When to Tweak It
William Bengen created the 4% rule in 1994. He tested U.S. data back to 1926, crashes included. A mix of 50-75% stocks and the rest bonds succeeded in nearly every 30-year period. You withdraw 4% of your starting balance, so $80,000 from $2 million. Then bump it yearly for inflation. History shows high success rates.
However, 2026 calls for caution. Bond yields stay low. Stock prices sit high. People live longer too. Morningstar pegs 3.9% as optimal now, up from 3.3% in recent years as rates rose. Many experts push 3-3.5% for extra safety. At 3.5%, your first year drops to $70,000. That leaves room if markets dip early.
Sequence of returns risk hurts most. Bad years hit right when you start spending. Stocks fall, you sell low, principal shrinks fast. Bonds help buffer this. Keep 30-50% there for steady cash. Or use flexible withdrawals. Cut spending 10-20% in down years. Skip inflation bumps sometimes. For example, in a 2023-style bear market, drop from $80,000 to $64,000. Portfolios rebound better this way.
BlackRock likes annuities for guarantees. Put 5-10% of your $2 million into one. A 65-year-old gets fixed payments for life, around 6% payout. It covers basics, lets stocks grow the rest.
Here’s how rates stack up today:
| Rate | Fits 2026? | Reason |
|---|---|---|
| 4% | Riskier | Old high yields assumed |
| 3.5% | Safer | Matches low yields, high prices |
| 3.9% | Balanced | Morningstar pick for new retirees |
Test your plan with free tools. Vanguard’s calculator runs scenarios. NerdWallet simulates 4% paths. Fidelity offers Monte Carlo tests. Bengen himself says 4.7% works in worst cases with diverse assets. Adjust based on your age and health. Flexible rules beat rigid ones over time. In short, start conservative. Your nest egg stays safe longer.
Avoid These Traps That Could Derail Your Retirement
Your $2 million nest egg looks solid. Yet simple mistakes derail many plans. These traps shrink savings fast, especially with inflation at 2.4-3% in 2026. How to invest 2 million for retirement demands you spot them early. Common errors include no clear plan, too much cash, skimpy diversification, skipped taxes and health costs, plus panic sales. Let’s break them down with real fixes
Steps back to safety
- No plan leaves you guessing. Meet Sarah. She saved $2 million but never tracked spending or tested scenarios. Inflation pushed her costs up 30% over a decade. She ran short by 70. Fix it: Build a budget now. Use Fidelity’s Monte Carlo tool to check if $2 million covers your needs 90% of the time. Review yearly. This keeps your strategy on track.
- Too conservative cash drags you down. John parked everything in savings at 4-5%. Inflation ate half his buying power in 10 years. Fix it: Shift to 50-60% stocks early, as we covered. Your $1 million there grows to beat 3% rises. Balance risk with your age.
- Undiversified bets one flop. Lisa loaded up on tech stocks. The 2022 drop cut her $2 million by 25%. Fix it: Spread across stocks, bonds, REITs per our portfolio table. Rebalance once a year. Global ETFs add protection.
- Ignoring taxes and health costs bites hard. Tom skipped Roth conversions and HSA fills. Taxes plus $315,000 health bills drained 20% early. Fix it: Convert gradually to low brackets. Budget $300,000-plus for care. Max HSAs tax-free.
- Panic selling locks in pain. During the 2022 crash, Mike sold stocks low. He missed the rebound and lost $400,000 in growth. Fix it: Hold through dips. Use bonds for cash needs. Set rules upfront.
Most importantly, grab a fee-only advisor. They spot blind spots and tweak your $2 million plan. Small changes now save big later. Stay steady, and your retirement thrives.
Conclusion
You now know how to invest 2 million for retirement the right way. First, assess your true needs with inflation and healthcare in mind.
Then, shift funds into tax-smart accounts like Roth IRAs. Next, diversify across stocks, bonds, real estate, and more for growth and safety. Set up flexible withdrawals around 3.5-4%, and steer clear of common traps like panic selling or too much cash.
Take action today. Grab a fee-only advisor to tailor this plan to your life. Run your numbers with tools from Vanguard or Fidelity right now.
Back to Ways to Save Cash
Are you looking for better ways and tools to build your monthly revenue and brand? Be sure to check out our other resources located here to speed up the process.
Nathan
Dr. Nathan Pennington, DBA, earned his Doctor of Business Administration degree from the University of Missouri-St. Louis and brings over 15 years of online entrepreneurial experience in helping people learn how to blog, earn income online and build passive income streams outside of what the school system teaches.


