
Fire Method for Early Retirement

Disclosure: This post may contain affiliate links, meaning if you decide to make a purchase through my links I may earn a commission at no additional cost to you. See my disclosure for more info.
Build A Smarter Online Business
Want to turn your content into traffic, income, and long-term freedom? Start with the guides built to help you grow smarter.
Explore Online Business Guides →More time, less stress, and the freedom to say yes (or no) on your own terms is the dream. The fire method for early retirement can get you there, but it isn’t magic, it’s a plan built on choices, math, and tradeoffs.
FIRE stands for Financial Independence, Retire Early. In plain terms, you save and invest enough that your investments can pay your bills, so work becomes optional. For some people, that means fully retiring in their 30s, 40s, or 50s; for others, it means switching to lighter work, taking long breaks, or doing a part-time job for benefits.
In this post, you’ll learn how FIRE works, starting with the core idea: spend less than you earn, invest the gap, and repeat until your portfolio can cover your lifestyle. You’ll also see how to estimate your FIRE number (often based on annual expenses), what to invest in, and how to think about taxes and account access.
Finally, we’ll cover the risks people don’t talk about enough, like market drops early in retirement, healthcare costs before Medicare, and inflation. By the end, you’ll know how to choose a version of FIRE that fits your life, not someone else’s spreadsheet.
Back to Financial Confidence Strategies to Earn More
How the FIRE method works in plain English
The FIRE method for early retirement is simple math with real-life choices behind it. You spend less than you earn, save a high percent of your income, and invest the gap. Then you give your money time to grow, so it can cover your bills later.
Here’s the key shift: FIRE is not about being “rich,” it’s about being financially independent. Independence depends more on what you spend than what you make. A high income with high expenses can feel like a trap. On the other hand, moderate income with low expenses can create real freedom.
A quick round-number example makes this click. If you spend $60,000 a year, you need a much larger portfolio than if you spend $40,000. Lower spending usually shrinks your target and speeds up your timeline, because you can invest more each month and you need less to live on later.
The three levers you can actually control: spending, income, and time
Think of FIRE like a three-knob radio. You can turn spending down, turn income up, and give your plan time to work. You don’t need perfection, but you do need consistency.
Ready To Build More Traffic And Income?
Use Internet of Business to learn blogging, SEO, affiliate marketing, passive income, and digital business systems that compound over time.
Start Building Your Digital Income →1) Spending (the fastest lever to pull)
This is where most people find their biggest wins, because it raises your savings rate immediately. Start with the “big rocks,” then clean up the small leaks.
Common Places to Look
- Housing: House hacking, downsizing, moving, getting a roommate, refinancing (if it truly lowers cost), or negotiating rent at renewal.
- Transportation: Driving a paid-off car longer, dropping to one car, using public transit, biking, or shopping insurance rates annually.
- Food: More home cooking, fewer delivery orders, a simple weekly meal plan, and being honest about “small” grocery trips.
- Subscriptions: Cancel bundles you forgot, rotate streaming services, or downgrade phone plans.
Small change vs big change (real-world difference):
Cutting a $4 daily coffee can help, but changing housing usually moves the needle more. Saving $120 a month is nice. Saving $600 to $1,200 a month on housing can reshape your whole timeline.
If you want FIRE to feel easier, lower the lifestyle you need to fund. Expenses are the weight on the bar.
2) Income (the power lever for speed)
Lower spending is great, but income can help you invest more without feeling deprived. A few practical routes:
- Raises: Track wins, bring numbers to reviews, and ask directly.
- Job hopping: Switching roles often boosts pay faster than waiting.
- Side gigs: Freelance work, weekend shifts, consulting, selling a skill, or seasonal work with clear income goals.
When your income rises, avoid “automatic upgrades.” Keep your core lifestyle steady, invest the difference, and watch your savings rate climb.
3) Time (the quiet multiplier)
Time is compounding’s best friend. Starting earlier matters because your investments get more years to grow, even if you start small. If you’re starting later, you can still win by saving a higher percent and staying invested through boring months and scary headlines.
What “retire early” really means today
For many people, “retire early” doesn’t mean sitting still forever. It often means work optional, where you can walk away from a bad job, take time off, or choose work that fits your life.
Here are common versions you’ll see:
- Work optional: You can cover your needs without a paycheck, so work becomes a choice.
- Mini retirements: Taking months off between jobs, or after a big savings push.
- Sabbaticals: A planned break to rest, travel, care for family, or reset.
- Passion projects: Starting a small business, making art, or building something meaningful without panic about income.
- Part-time work: Working 10 to 25 hours a week for structure, social time, or benefits.
In 2026, the reality is that remote and flexible work can make a “semi-retired” life easier to pull off. With about 22 to 25% of paid workdays in the US done remotely, and roughly 32.6 million Americans projected to work remotely by 2026, it’s simpler to keep some income coming in without giving up your freedom. For many FIRE followers, that middle path is the sweet spot: lower stress, more time, and a smaller portfolio required.
Find your FIRE number without getting lost in math
Your FIRE number is the portfolio size that lets your investments cover your bills forever. In the fire method for early retirement, you get there by multiplying your annual expenses by 25. That simple step skips the guesswork. Most people rush this part and end up with a shaky plan. Instead, follow these steps to nail it down.
Step 1: Figure out your real yearly expenses (not your guess)
Grab your bank and credit card statements from the last three to six months. Add up every dollar spent. Divide by the months to find your monthly average. Then multiply by 12 for your yearly baseline. This beats wild guesses because it shows your actual habits.
Next, adjust for one-time costs you spread out. Add full-year amounts for car insurance, property taxes, or holiday gifts. For example, if travel hits hard in summer, smooth it across 12 months. Tools like Mint or YNAB make this easy; they categorize spending automatically.
Early retirement brings fresh costs too. Budget extra for healthcare before Medicare kicks in, new hobbies that fill your days, or trips you always dreamed about. Healthcare alone can add thousands yearly, so don’t skip it. Your goal is a realistic number that lasts.
Step 2: Use the 25x rule and the 4% rule, and know the limits
The 25x rule comes from the 4% rule. It says you can pull 4% from your portfolio in year one, then adjust for inflation each year. That should last 30 years in most markets. So, multiply expenses by 25 to get your target (because 100 divided by 4 equals 25).
Take $40,000 in yearly spending. Your FIRE number hits about $1 million. You withdraw $40,000 first year, or 4%. Markets go up and down, but history shows this works 95% of the time for 30 years.
For fire method for early retirement, though, you might retire decades earlier. That means 40 to 50 years of withdrawals. Bad markets right at the start can drain your nest egg fast; experts call it sequence risk. In 2026, with lower expected returns, stick to 3.25% to 3.5% for safety. That bumps your target to 28 to 30 times expenses.
This rule is a solid starting point, not ironclad. Test it with a calculator, and plan flexible spending.
Common “missing line items” that blow up early retirement budgets
Budgets fail when people forget ongoing hits. Here is a quick checklist of traps:
- Healthcare: Premiums and copays soar pre-Medicare; add $10,000 or more yearly.
- Taxes: Withdrawals trigger income tax; factor in 15% to 25% on top.
- Home repairs: Roofs, HVAC, or plumbing average 1% to 2% of home value each year.
- Car replacement: Plan $5,000 to $10,000 every 7 to 10 years.
- Family help: Gifts or support for kids or parents add up fast.
- Inflation: Costs rise 2% to 3% yearly; your number must grow.
- Fun money: Hobbies, dining out, or spontaneity keeps life good.
Add a 10% to 20% buffer right away. If your baseline is $40,000, aim for $44,000 to $48,000. This makes your plan tougher against surprises. In short, overplan now so you relax later.
Build a FIRE-friendly investing plan that you can stick with
You have your FIRE number locked in. Now direct your savings there with a plan that runs on autopilot. In the fire method for early retirement, success comes from boring, consistent investing, not hot tips or timing the market. Set it up once, automate deposits, and let time do the heavy lifting. This keeps you on track even when life gets busy.
A simple investing setup: diversified funds, automatic deposits, long horizon
Picking individual stocks sounds exciting. Yet most people lose to the market over time because they buy high and sell low. Diversification spreads your money across hundreds or thousands of companies. So one flop does not sink your ship.
Start with a basic mix. Put most in stock index funds for growth over decades. Add bonds or cash for stability as you near retirement. For example, someone in their 30s might go 90% stocks and 10% bonds. Your mix depends on how much risk you stomach and years until FIRE.
Set automatic deposits from your paycheck. Increase them with every raise. Ignore daily noise; hold for 20 to 30 years. Markets rise about 7% to 10% yearly after inflation, so patience pays.
Fees matter too. Choose low-cost funds under 0.1% expense ratio. They save you thousands over time. In short, simple beats fancy every time.
Where to invest first: using tax-advantaged accounts and a brokerage account
Taxes eat returns if you ignore them. The fire method for early retirement shines when you use accounts that delay or cut taxes. Fill these first, then spill into a brokerage.
A 401(k) lets your employer match contributions, free money. You contribute pre-tax, so it lowers your current bill. In 2026, limits hit $24,500 if under 50, plus $8,000 catch-up at 50 or older.
Next, traditional IRA grows tax-deferred. Withdrawals get taxed later. Roth IRA uses after-tax dollars now but tax-free later. Both cap at $7,500 in 2026, or $8,500 with catch-up. Roth suits early retirees because you access contributions anytime.
HSA works best if you have a high-deductible health plan. Contributions reduce taxes, growth is tax-free, and medical withdrawals stay tax-free. Check IRS for exact 2026 limits.
Once maxed, use a taxable brokerage. No special breaks, but you control it fully. Early retirement before 59 and a half needs tricks like Roth conversions or Rule 72(t) for penalty-free access. Rules change, so verify limits and your fit.
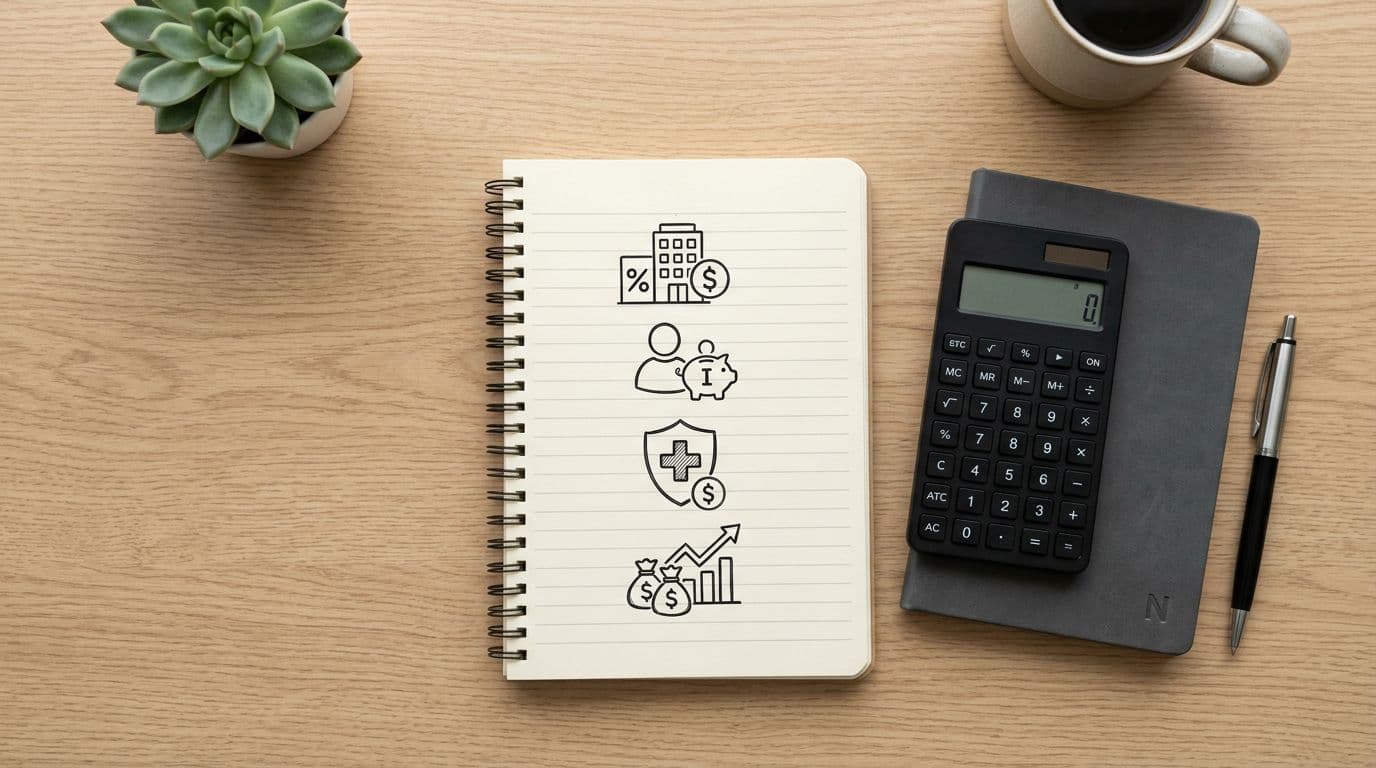
Prioritize this ladder because taxes compound against you otherwise.
Real estate and other income streams: helpful, but not required
Real estate tempts many in FIRE circles. Rentals bring cash flow after expenses. Yet repairs, vacancies, bad tenants, and management eat time and money. Real estate funds offer easier entry, but they carry concentrated risk if one area tanks.
You do not need property to hit FIRE. Index funds match history without the hassle. Still, rentals fit if you enjoy hands-on work and live near properties.
Side income acts as a buffer too. Freelance gigs or part-time consulting cover gaps during market dips. They ease pressure without full-time grind. For example, a few hours weekly might add $1,000 monthly.
Keep extras optional. Your core plan stands alone if you save aggressively.
Watch for scams promising quick real estate riches. Stick to what you understand. Above all, test any addition against your simple stock setup.
Choose a style of FIRE that fits your life, not someone else’s spreadsheet
The fire method for early retirement works best when you pick a path that matches your needs. You see stories online of people quitting at 35 with tiny budgets. Others keep luxury spending and retire later. Both can succeed.
The trick stays in knowing your spending habits, lifestyle wants, and risk comfort. Lean versions speed things up for minimalists. Fatter ones add padding for families or travelers. Hybrids blend work and freedom. Let’s break down the main options so you choose wisely.
Lean FIRE vs Fat FIRE: trading comfort for speed (or vice versa)
Lean FIRE means you cut spending low to retire fast. Think $25,000 to $40,000 a year for basics like rent, food, and transport. One person might live in a small apartment, cook simple meals, and skip new cars. Your FIRE number drops to $625,000 to $1 million at 25x. Speed comes quick because you save more each month.
Fat FIRE keeps higher spending, say $80,000 to $120,000 yearly. You hold space for dining out, vacations, or a bigger home. A couple could afford hobbies and helpers. Yet it takes longer; your target jumps to $2 million or more. You trade time for comfort.
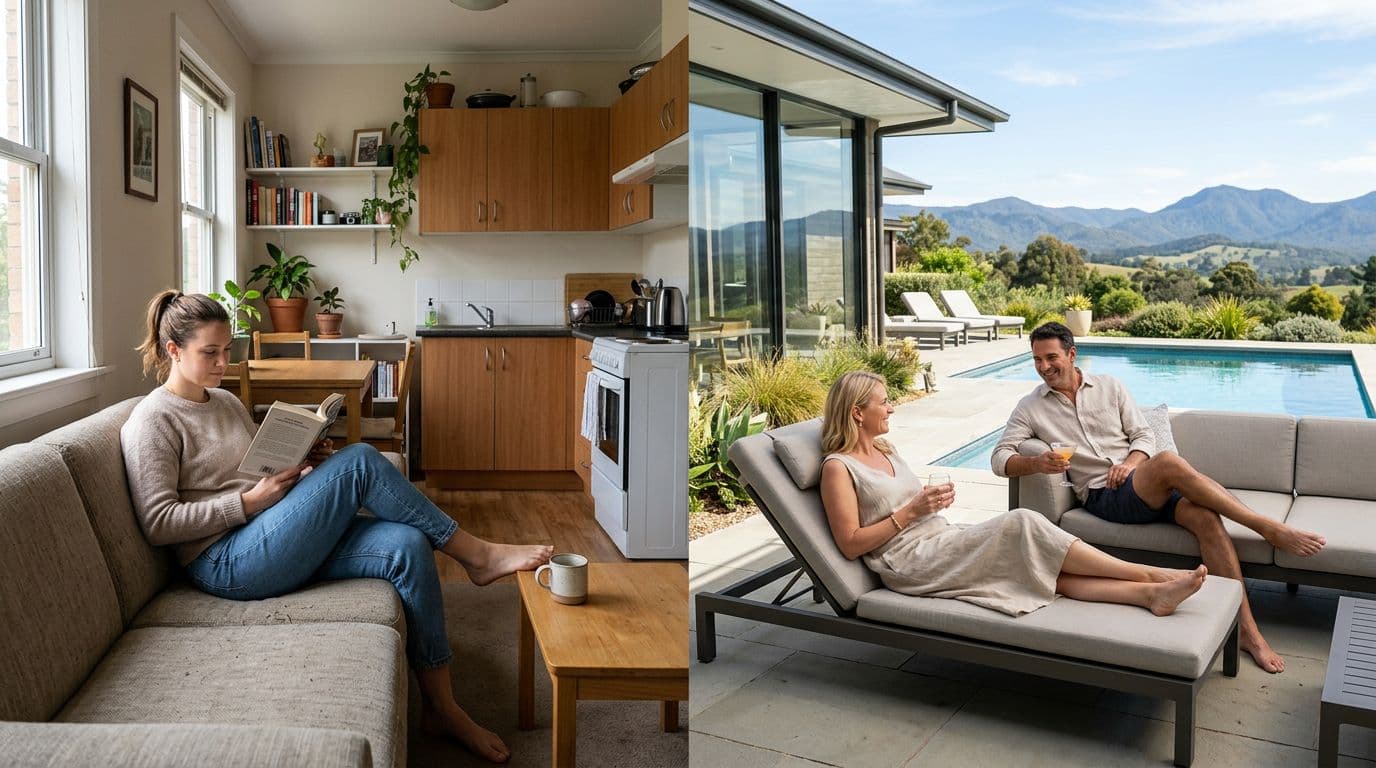
In short, Lean FIRE suits singles or couples okay with basics; it cuts your timeline but leaves little room for surprises. Fat FIRE fits those who need buffer, like parents or location lovers. However, it demands higher income or longer saving.
Barista FIRE and Coast FIRE: the “middle path” that many people prefer
Barista FIRE lets you quit full-time work but take part-time gigs for cash and perks. You cover basics from investments, then add $10,000 to $20,000 yearly from a coffee shop job or freelance. Benefits like health insurance stay key.
Coast FIRE shifts focus early. You invest enough now so it grows to your FIRE number by retirement age. Meanwhile, you just pay current bills. No aggressive saving later.
These paths gain traction in 2026. Remote work fills 22 to 25% of workdays, with 32.6 million Americans working remotely. Hybrid setups dominate at 52 to 53% of remote-capable jobs. So you grab flexible hours without office chains.
Barista FIRE works for social types who want structure. Coast FIRE helps if you hate grinding forever. Both lower your full portfolio needs.
A quick self-check to pick your version of FIRE
Ask yourself four questions to narrow it down. First, how much daily freedom do you crave? Total exit fits Lean or Fat. Some structure points to Barista.
Next, how do you handle uncertainty? Low buffer suits risk-takers for Lean FIRE. More cushion matches Fat or hybrids.
Then, do you like your work? If yes, Coast FIRE lets it coast along. Hate it? Push for quicker exit.
Finally, what expenses won’t budge? Kids mean higher spending, so Fat or Barista. Travel or city life pushes Fat FIRE. Basics only? Lean wins.
Write your answers. Match them to styles. For example, a family traveler picks Fat FIRE for peace. A solo minimalist goes Lean. Your pick sets the pace in the fire method for early retirement.
Avoid the biggest FIRE mistakes that can derail early retirement
You follow the fire method for early retirement step by step. Savings grow, your number nears. Yet common slips can wreck it all. People burn out from too much penny-pinching. Healthcare shocks hit hard before Medicare. Markets tank right when you quit. Taxes surprise from quiet withdrawals. In short, these issues turn dreams sour. So spot them now. Then build guards into your plan from day one.
Burnout and “frugal fatigue”: when the plan costs too much emotionally
Strict budgets feel great at first. You track every dime, skip lattes, cook beans and rice. Savings soar. However, months drag on. Joy fades. You resent the grind. Frugal fatigue sets in because humans crave balance. Cut too deep, and you quit before the finish line.
For example, one saver slashed fun to zero. Gym canceled, friends skipped, travel dreamed only. Life turned gray. They bounced back later with tweaks. Extreme cuts backfire because they ignore emotions.
Switch to values-based budgeting instead. List what matters most: family time, health, adventure. Fund those first. Then trim extras. Add a fun category, say $100 to $200 monthly. Spend it guilt-free on coffee dates or books. Focus cash on joys that stick, like classes over gadgets.
Hunt cheaper versions of joy too. Camp locally instead of flights. Borrow tools, join free groups. Host potlucks, not restaurants. These keep spirit high without blowing goals. As a result, you stay in the fire method for early retirement longer
Healthcare before Medicare: plan it early, not last minute
Medicare starts at 65. Early retirees face a gap. In the US, costs average $10,000 to $20,000 yearly per person on ACA plans without help. Keep income low, and subsidies drop it under $1,200 or to zero. Location, age, and plan type shift numbers too. Skip planning, and it eats your portfolio.
A 60-year-old single filer pays $800 monthly without subsidies. Couples lose $18,000 yearly in aid if income tops limits. Out-of-pocket hits add up. So build it into your fire method for early retirement budget now.
First, slot $12,000 to $15,000 per person yearly as baseline. Test scenarios on HealthCare.gov. Control income with Roth pulls, not traditional ones. They count less for subsidies.
Consider part-time work for benefits. A barista gig covers premiums. Keep an emergency health fund, three to six months of costs in cash. Shop open enrollment each fall. These steps make the gap survivable.
Market drops, inflation, and sequence risk: protecting your plan in the real world
Markets crash sometimes. Inflation grinds value. Sequence of returns risk hurts most: poor years hit early in retirement. You sell low to pay bills. Fewer shares rebound later. Two folks see same average returns. One thrives with good starts. The other shrinks fast.
Picture $1 million start, $40,000 yearly pulls. Early drops leave $100,000 after 20 years. Good starts build to $650,000. First decade counts 77% for success. No plan kills risk. You manage it.
Build a cash buffer, two to three years expenses. Spend flexible: cut 20% in bad years. Add part-time income during dips. Diversify stocks, bonds, maybe real estate. Shift safer near quit date. Stay invested; panic sells lock losses. So your fire method for early retirement weathers storms.
Taxes and “surprise bills”: why early retirees still need a tax plan
Retirement skips paychecks, not taxes. Withdrawals count as income. Under 59½, add 10% penalty on most IRAs or 401(k)s. Capital gains tax stocks sold. All raise MAGI, cutting ACA subsidies. One extra $10,000 pull spikes health costs too.
Basics matter. Track total income yearly. Roth contributions pull free. Conversions fill low-tax years. Rule 72(t) skips penalties with steady payments. Yet rules tangle fast.
Learn brackets, MAGI math. Model scenarios. Get pro help for withdrawal order. Therefore, surprises stay small in your fire method for early retirement.
Conclusion
The fire method for early retirement boils down to smart choices over perfection. You control spending, income, and time. So you cut costs where it counts, boost earnings without lifestyle creep, and let investments compound. Pick your style, whether Lean, Fat, Barista, or Coast, to match your life. Then dodge pitfalls like burnout, healthcare gaps, and market dips with buffers and plans.
Here are the core steps to start today:
- Track your spending for three months to find your real baseline.
- Set a starter FIRE number by multiplying adjusted expenses by 25 (or 28-30 for safety).
- Choose a savings rate goal, like 50% if possible, to speed your path.
- Automate deposits into tax-advantaged accounts first, then a brokerage.
- Build an emergency fund covering two to three years of lean expenses.
- Pick your FIRE style based on your needs, risk tolerance, and joy factors.
FIRE is not a race or contest. It’s your plan for more time and less stress. Many mix it with remote work for flexibility. In addition, real stories show discipline wins amid AI shifts and rising costs.
Back to FIRE planning tips
Are you looking for better ways and tools to build your monthly revenue and brand? Be sure to check out our other resources located here to speed up the process.
Nathan
Dr. Nathan Pennington, DBA, earned his Doctor of Business Administration degree from the University of Missouri-St. Louis and brings over 15 years of online entrepreneurial experience in helping people learn how to blog, earn income online and build passive income streams outside of what the school system teaches.


