
Conservative Asset Allocation Tips for FIRE Investors

Disclosure: This post may contain affiliate links, meaning if you decide to make a purchase through my links I may earn a commission at no additional cost to you. See my disclosure for more info.
Build A Smarter Online Business
Want to turn your content into traffic, income, and long-term freedom? Start with the guides built to help you grow smarter.
Explore Online Business Guides →Looking for more tips pertaining to conservative asset allocation? FIRE stands for Financial Independence, Retire Early, which means I’m building enough invested (and often partially passive) income that my bills are covered without a full-time job. For a lot of us, the goal isn’t to beat the market with a flashy portfolio. It’s to reach a number, protect it, and keep options open.
That’s why I’m cautious with the popular “just go 80/20 and forget it” advice. When I’m close to my target, a big drop early on can do real damage, because withdrawals and living costs don’t pause just because the market’s down. This is sequence-of-returns risk, and it hits hardest when the timeline is short or the portfolio has to start supporting real spending.
There’s also the sleep-at-night factor. FIRE is supposed to buy freedom, not anxiety, and a portfolio that’s too aggressive can make it hard to stay consistent when volatility spikes. Besides, many FIRE investors already have a high savings rate, so I don’t need to take maximum risk to make progress, I need a plan I’ll stick with.
In this post, “conservative asset allocation” doesn’t mean “no stocks.” It means choosing a stock and bond (and cash) mix that matches my actual need to take risk, plus my ability to take risk, so I can keep investing through good markets and bad ones. I’ll focus on practical tips for building a simple allocation, deciding what “conservative” looks like for your stage of FIRE, and setting basic rebalancing rules that don’t require daily attention.
I’m also going to treat this like a checklist you can copy, then adjust to fit your income, goals, and comfort level. If you’re still working on the foundation, it helps to align investing with basic priorities like emergency savings and near-term expenses, and this list of essential savings goals like emergency funds can help you sanity-check what should stay in cash versus what can be invested.
This is informational only, not personalized financial advice. I’ll share how I think about it, but you’ll still want to do your own research and make choices you can live with.
Start with the real risk in FIRE, it’s not market dips, it’s bad timing
The biggest risk in FIRE usually isn’t a random down year. It’s when that down year hits. If the market drops hard right as I stop working (or right before), my portfolio has to do two jobs at once: recover from losses and fund my life.
Here’s the simple story I use to keep this real. Two investors start with $1,000,000 and both average about the same return over a decade. Investor A gets hit with a nasty bear market in year one, then strong gains later. Investor B gets the strong gains first, then the bear market later. If neither withdraws, they can end up in a similar place. But in FIRE, I’m withdrawing. That early hit can permanently shrink the base I’m living on, even if markets “do fine” later.
This is where conservative asset allocation starts to matter more than bravado. It’s not about predicting crashes. It’s about reducing the damage if the timing is bad.
Ready To Build More Traffic And Income?
Use Internet of Business to learn blogging, SEO, affiliate marketing, passive income, and digital business systems that compound over time.
Start Building Your Digital Income →Just as important, FIRE changes how I think about risk:
- Risk tolerance: how I feel during a 30% to 40% drop.
- Risk capacity: what I can survive without ruining the plan (job options, cash, flexibility).
- Risk need: how much risk I must take to hit the goal.
When I’m years away, I may have high capacity (I can keep earning). As I approach early retirement, capacity drops fast because my paycheck is about to vanish.
One more thing people skip: a high savings rate is the boring advantage. If I’m saving 40% to 60% of my income, I’m already doing the heavy lifting. That makes “chasing returns” less useful, and it makes a calmer allocation easier to stick with.
The danger zone, the 5 years before and after you hit your FIRE number
This 10-year window is where sequence-of-returns risk has teeth. In the five years before FIRE, a big drop can delay the date because my portfolio is smaller than planned. In the five years after, a drop can be worse because withdrawals turn a temporary decline into a lasting haircut.
I think of it like hiking above the tree line. When the weather shifts, I don’t want to be wearing the same outfit I wore at sea level. Similarly, as I get close to my FIRE number, I prefer a glide path that shifts risk down, at least somewhat, instead of staying aggressively stock-heavy until the last minute.
A conservative glide path can look like:
- Holding more cash for near-term spending, so I’m not forced to sell stocks after a bad year.
- Increasing high-quality bonds (or similar stabilizers) temporarily, then adjusting later once the portfolio has “survived” the early-retirement years.
- Rebalancing more deliberately, because big swings matter more when I’m close to the finish line.
A simple rule of thumb I like: as I enter the five years before FIRE, I want 2 to 5 years of basic spending in lower-volatility assets (cash, T-bills, and high-quality bonds, depending on my plan).
Still, it’s personal. A pension, rental income, or a spouse’s steady job changes the math. So does health, family needs, and how tight my budget is.
How withdrawals change the math, even if your investments are “good”
Withdrawals are where timing stops being an abstract concept. When I sell shares to pay bills during a downturn, I’m selling more shares to raise the same cash. Those shares are gone, so they can’t participate in the rebound.
Here’s an easy example. Say I retire with $1,000,000 and plan to withdraw 4% ($40,000) for the year.
- The market drops 30%, and my portfolio falls to $700,000.
- I still need $40,000.
- After the withdrawal, I’m at $660,000.
Now my next year’s recovery starts from $660,000, not $700,000, and definitely not $1,000,000. Even if markets bounce later, I’ve reduced the “engine size” that compounds.
That’s why I like to build shock absorbers into my plan:
- Flexible spending: I can cut travel, delay big purchases, or reduce discretionary costs for a year or two.
- Part-time income: a small side income can cover a surprising amount of spending, which means fewer forced sales.
- Cash buffer: I can fund withdrawals from cash for a while, instead of selling stocks at the worst time.
This is also where budgeting stops being boring and starts being a survival skill. If you want a practical refresher, I keep coming back to master budget tips for 2026 because a tight budget gives me more options when markets get rough.
A quick self-check to pick a risk level you can stick with
Before I pick an allocation, I run a simple self-check. I’m not trying to sound tough. I’m trying to be honest, because honesty is what keeps me invested.
Here are questions I ask myself (and I recommend you answer them in writing):
- How stable is my current job or main income stream?
- If I lost income, how fast could I replace it (same field or any work)?
- How many months of expenses do I have in a true emergency fund?
- Do I have high-interest debt that would become a crisis in a downturn?
- Do I have dependents who rely on my income or benefits?
- Do I have a side hustle or part-time work I’d realistically do again?
- How did I behave during 2020 or 2022, did I hold, buy more, or panic-sell?
- Could I cut my spending by 10% for a year without breaking my life?
My rule is simple: if I can’t hold through a 40% stock drop, I don’t build a plan that requires it. The “best” allocation on paper is useless if I abandon it at the exact wrong time.
Build your conservative asset allocation, pick a simple mix you’ll actually maintain
A conservative asset allocation only works if I can keep it steady when headlines get loud. So I build it like a good side hustle system, simple inputs, repeatable steps, and no fancy pieces I won’t maintain.
My default is a broad stock base (for long-term growth), a bond base (for stability), and a cash buffer (for short-term spending and emotional comfort). The goal is to limit downside and reduce forced selling, not to guess the next winner.
Pick your stock slice, broad index beats “safer” stock picking
When I want stock exposure without babysitting a portfolio, I use two plain-vanilla pieces:
- Total US stock index: one fund that owns a huge swath of public US companies, from giant firms to smaller ones. If the US stock market grows over decades, this captures it.
- Total international stock index: one fund that owns thousands of companies outside the US, spread across developed and emerging markets. It’s global diversification in one step.
In practice, this approach keeps me from “defensive” stock picking that often backfires. People will say, “I’ll just buy safer stocks,” then load up on a handful of brands they recognize. That’s not safety, that’s concentration risk with a comforting story.
How I decide US vs international: I pick a split I can live with for a decade and move on.
- If I want simple and common: 70% US, 30% international inside my stock allocation.
- If I want closer to global market weights without obsessing: 60% US, 40% international inside my stock allocation.
Either can be reasonable. What matters is that I choose one, write it down, and stop tinkering.
One more trap: dividend funds aren’t the same as low risk. Dividends can be cut. Dividend-heavy funds can also tilt toward certain sectors, which adds hidden concentration. I treat dividend yield as a feature, not a safety label.
Choose your ballast, bonds, TIPS, and cash each have a job
In a conservative plan, bonds are my ballast. They don’t exist to “beat stocks.” They exist to help me stay invested and avoid selling stocks in a bad year.
Here’s how I think about the main options in plain language:
- Nominal bonds (Treasuries or high-quality bond funds): They pay interest in normal dollars. They often hold up better when stocks fall, although nothing is guaranteed.
- TIPS (Treasury Inflation-Protected Securities): These adjust with inflation, so they aim to protect purchasing power. They can still bounce around in price, especially over short periods.
- Short-term bond funds: These own bonds that mature sooner. They tend to swing less when rates change, but usually pay less interest than longer-term bonds.
That last point ties into interest-rate risk. When rates rise, existing bonds tend to drop in price. The key term is duration, which is basically a sensitivity meter. Higher duration usually means bigger price moves when rates change.
FIRE Investors
For conservative FIRE investors, I usually prefer short to intermediate duration because it’s a middle path:
- Long-term bonds can be great diversifiers at times, but they can also take bigger hits when rates jump.
- Ultra-short options can feel stable, but they may not give much “shock absorber” effect against stock volatility.
- Short to intermediate duration often gives a more manageable ride.
TIPS fit best when I’m worried about inflation eating my future spending power. Still, I keep my expectations realistic. They’re not magic, they’re just a different kind of bond.
Where do pension, real estate, or strong side income fit? I treat reliable income streams as bond-like cash flow in planning. If I have a pension coming later, steady rental net income, or a side hustle that’s genuinely durable, I may not need as much “bond ballast” on day one. On the other hand, if that income is shaky or tied to the same economy as my job, I don’t count it as a full bond replacement.
My rule: I only “credit” an income stream as bond-like if I’d still expect it during a recession.
Cash also has a job. It’s useful for near-term spending and emergency flexibility. However, if I let cash sprawl across the portfolio forever, it becomes a drag on long-term growth.
Add a cash buffer without letting it get out of hand
I like the cash wedge idea: holding 6 to 24 months of expenses in cash-like options so I can ride out stock dips without panic-selling.
When does a bigger wedge make sense?
- I’m within a few years of FIRE, and a bad market would force withdrawals.
- My income is variable (freelance, commissions, side hustles).
- I know I’m prone to stress-selling, so I pay for calm with a slightly bigger cash buffer.
For where to hold it, I stick to boring places that are easy to access:
- High-yield savings account (HYSA) for true “grab it tomorrow” money.
- Money market fund (usually inside a brokerage) for cash that’s still liquid.
- Treasury bills when I’m fine locking cash for a short term and want a government-backed option.
The tradeoff is simple. More safety now usually means less growth later. That’s okay if the wedge is doing its job, which is to protect my decisions, not maximize returns.
One-page allocation examples you can copy, then customize
I keep model portfolios “one-page simple.” That means broad index funds, low fees, and no overlap that makes it hard to rebalance. Below are four conservative ranges I’d actually consider, each with a small cash bucket to smooth withdrawals.
Here are the models in a quick table:
| Model | Stocks | Bonds (nominal + TIPS) | Cash | What it optimizes for |
|---|---|---|---|---|
| A | 40% | 55% | 5% | Sleep-at-night stability, smaller drawdowns |
| B | 50% | 45% | 5% | Balanced caution, still solid growth potential |
| C | 60% | 35% | 5% | More growth, still conservative relative to all-stock |
| D | 50% | 30% | 20% | Simplicity + cash wedge for early-retirement spending |
Then I choose a stock split inside those models, usually 70/30 US/international for simplicity. For bonds, I often start with high-quality nominal bonds plus a smaller TIPS sleeve if inflation protection matters to me.
A few quick customization rules I follow:
- If I have a reliable pension later, I may lean toward Model B or C, because future income lowers my need for portfolio stability today.
- If my “income” is mostly rental property, I’m careful. Real estate can be bond-like, but vacancies and repairs can show up at the worst time.
- If my side income is steady and recession-resistant, I might use a smaller cash wedge. If it’s ad-driven or client-driven, I keep the wedge bigger.
Finally, I don’t obsess over where each fund sits yet. Later in the post, I match these pieces to taxable vs retirement accounts so the allocation stays clean and tax-aware.
Make your plan tougher with guardrails, rebalancing, and a “what if” playbook
A conservative asset allocation isn’t “set it and forget it.” It’s “set it, protect it, and keep it from drifting.” Without guardrails, two things can break my plan: a crash that scares me into selling, or a long bull run that quietly turns my cautious portfolio into an aggressive one.
I plan for both. In a crash, the guardrails keep me from panic decisions. In a bull market, they keep risk from creeping up while I’m feeling confident. The point is behavioral: the best asset allocation is the one I can follow, year after year, without improvising under stress.
Set rebalancing rules you can follow on autopilot
Rebalancing is basic maintenance. I’m not trying to “improve returns.” I’m keeping risk where I intended it. The cleanest way to do that is to pick a rule that feels boring.
Here’s how I compare the most common options:
| Approach | How it works | Pros | Cons | Best for |
|---|---|---|---|---|
| Quarterly | Check every 3 months, rebalance if needed | Keeps drift small, good for hands-on planners | More trades, more taxable events | People who like routines |
| Yearly | Check once per year (often same month) | Simple, low effort, fewer trades | Drift can get large in fast markets | Most investors with steady contributions |
| Band-based | Rebalance only if an asset moves outside a band (example: 5 percentage points) | Trades only when it matters | Requires tracking bands | People who want fewer “busywork” rebalances |
| Hybrid | Check yearly, but also rebalance if bands are hit | Balanced discipline | Slightly more complex | My default choice |
A straightforward hybrid rule I like: review once a year, but also rebalance any time an asset class is off target by 5 percentage points (for example, 50/45/5 drifting to 56/39/5). It’s simple, and it responds when markets move fast.
Two details that matter
- Transaction costs: Many brokerages offer commission-free ETF trades, but spreads still exist. Frequent small trades can add friction. That’s another reason I prefer yearly or band-based rules.
- Taxes in taxable accounts: Selling winners can trigger capital gains. I try to rebalance tax-efficiently, and I avoid creating tax bills just to chase a perfect pie chart.
My favorite “first move” is the easiest one: use new contributions to rebalance before I sell anything. If stocks ran up, I direct new money toward bonds or cash until I’m back near target. This reduces trades and often avoids taxes.
Just as important, I define when not to rebalance: I don’t override my rule because I’m scared, and I don’t “wait for things to calm down.” Panic selling dressed up as “rebalancing” is still panic selling. If I can’t follow my rule, the rule is too strict or my allocation is too aggressive.
Write a simple investment policy statement in 10 minutes
I treat an Investment Policy Statement (IPS) like the owner’s manual for my portfolio. When markets get loud, I don’t want to “feel my way” through decisions. I want to read what Past Me already decided.
I keep mine short. If it turns into a legal document, I won’t use it.
Here’s a quick IPS template I can copy into a notes app:
- Target allocation: My portfolio will hold __% stocks, __% bonds, __% cash, with stocks split __% US and __% international.
- Rebalancing rule: I will review on (month) each year and rebalance if any major asset class is off by 5 percentage points (or more). I will use new contributions first.
- When I’ll change the plan: I will only change the allocation for life events (job loss, new dependents, major health change, nearing FIRE within __ years), not for market forecasts.
- What I won’t do: I won’t buy based on hot tips, headlines, or short-term predictions. I won’t go to cash because “it feels safer.”
- My 30% drop plan: If stocks fall 30%, I will follow my rebalancing rule, review my cash needs, and reduce discretionary spending before I sell long-term holdings.
Stress-test your allocation with plain numbers, not fancy spreadsheets
I don’t need a complex model to stress-test. I just need a “can I live with this” check.
A quick drawdown estimate I use:
- Pick a stock drop that feels realistic in a bad year. Historically, broad stocks have seen drops of 30% to 50% at times.
- Multiply that drop by my stock percentage to estimate portfolio impact (bonds may help, but I stay conservative in assumptions).
- Add withdrawals if I’m near or in FIRE, because withdrawals deepen the hole.
Example: If I’m 60% stocks and stocks drop 40%, a rough portfolio hit is 0.60 × 40% = 24% (before any bond changes). On a $1,000,000 portfolio, that’s about $240,000 down on paper. Then I ask, “If I also need $40,000 to live, how does that change year one?”
Next, I run three mini-scenarios that cover most of the real-world pain:
- 2008-style crash: Big drop, scary headlines, then a multi-year climb back.
- High inflation: Prices rise fast, cash loses buying power, and bonds can disappoint.
- Flat decade: Stocks churn, returns feel pointless, and boredom becomes a risk.
Then I look for pressure-release valves. Even small changes can make a conservative plan much tougher:
- Adding cash: A bigger cash wedge can cover spending so I sell fewer shares at bad prices.
- Lowering withdrawals: Cutting spending 5% to 15% for a year or two can protect the base.
- Side income: A part-time gig, freelancing, or a small online business can replace enough withdrawals to change the math.
What to do in a downturn, a calm checklist for FIRE investors
When markets drop, I don’t hunt for predictions. I run a short process that keeps me steady.
- Pause big purchases for 30 days. I keep the option to spend later, but I stop impulse decisions now.
- Check my emergency fund and near-term cash. I confirm I can cover essentials without selling stocks this month.
- Rebalance only if my rule says so. I don’t “rebalance” as an excuse to bail out of risk.
- Look for tax moves in taxable accounts. If I have losses, I consider tax-loss harvesting (and I stay aware of wash sale rules). I keep it simple and avoid creating a mess.
- Adjust withdrawals, not the whole strategy. I cut discretionary spending first, then revisit my withdrawal rate if the downturn lasts.
- Focus on controllables. I keep saving if I’m working, I keep fees low, and I protect my income. In a downturn, extra cash flow from a side hustle can be more powerful than perfect timing.
My steady rule: I can’t control markets, but I can control my behavior. That’s what makes a conservative asset allocation work when it actually counts.
Conservative withdrawals are part of asset allocation, plan them together
A conservative asset allocation is only half the job in FIRE. The other half is how I pull money out when markets act up. If my withdrawal plan is rigid, even a well-built portfolio can get stressed in the first bad stretch.
I like to think of it like a car with good brakes but a reckless driver. The portfolio might be fine, but the spending plan can still send me off the road. So I plan withdrawals and allocation together, because they solve the same problem: avoiding forced stock sales when prices are down.
Use a flexible withdrawal rule instead of a single magic number
The 4% rule is a useful reference point, but it can feel less conservative for early retirees. My timeline might be 40 to 60 years, not 30. Also, real life rarely follows a clean inflation-adjusted path.
Instead of clinging to one number, I prefer a simple guardrail approach. The basic idea is: start with a reasonable rate, then adjust spending based on how the portfolio is doing. If things go well, I can spend a bit more. If things go poorly, I tighten up before damage compounds.
Here’s a clean, light-math version I can actually follow:
- Pick a starting withdrawal rate I can live with (for example, 3.5% to 4.0%).
- Set portfolio “bands” around my starting value (or around a rolling high-water mark).
- Raise or cut spending when I cross those bands.
A practical band setup might look like this:
- Green (safe): Portfolio is at or above plan, I can give myself a small raise (like 2% to 5%).
- Yellow (caution): Portfolio is down but not scary, I hold spending steady and skip “raises.”
- Red (risk): Portfolio drops past my trigger point, I cut discretionary spending for a while.
I don’t need perfect triggers. I need triggers I’ll follow. Flexibility does most of the heavy lifting because it reduces the worst-case behavior: selling a lot of stocks after a big drop.
If I can cut spending 10% for a year or two, I can often lower risk more than I can by trying to “pick safer” investments.
Buckets done right, spending plan first, investment plan second
When I hear “bucket strategy,” I don’t think market timing. I think organization. Buckets help me match money to time, so my near-term bills don’t depend on next month’s stock price.
I keep it simple with three buckets:
- Cash bucket (1 to 2 years): This covers my basic spending and reduces panic. Think HYSA, money market funds, T-bills.
- Bond bucket (3 to 7 years): This is my “bridge” money, meant to refill cash during normal rebalancing. Think high-quality short to intermediate bonds, possibly some TIPS.
- Stock bucket (long-term): This is growth money for the later years of FIRE. It funds the decades, not next year.
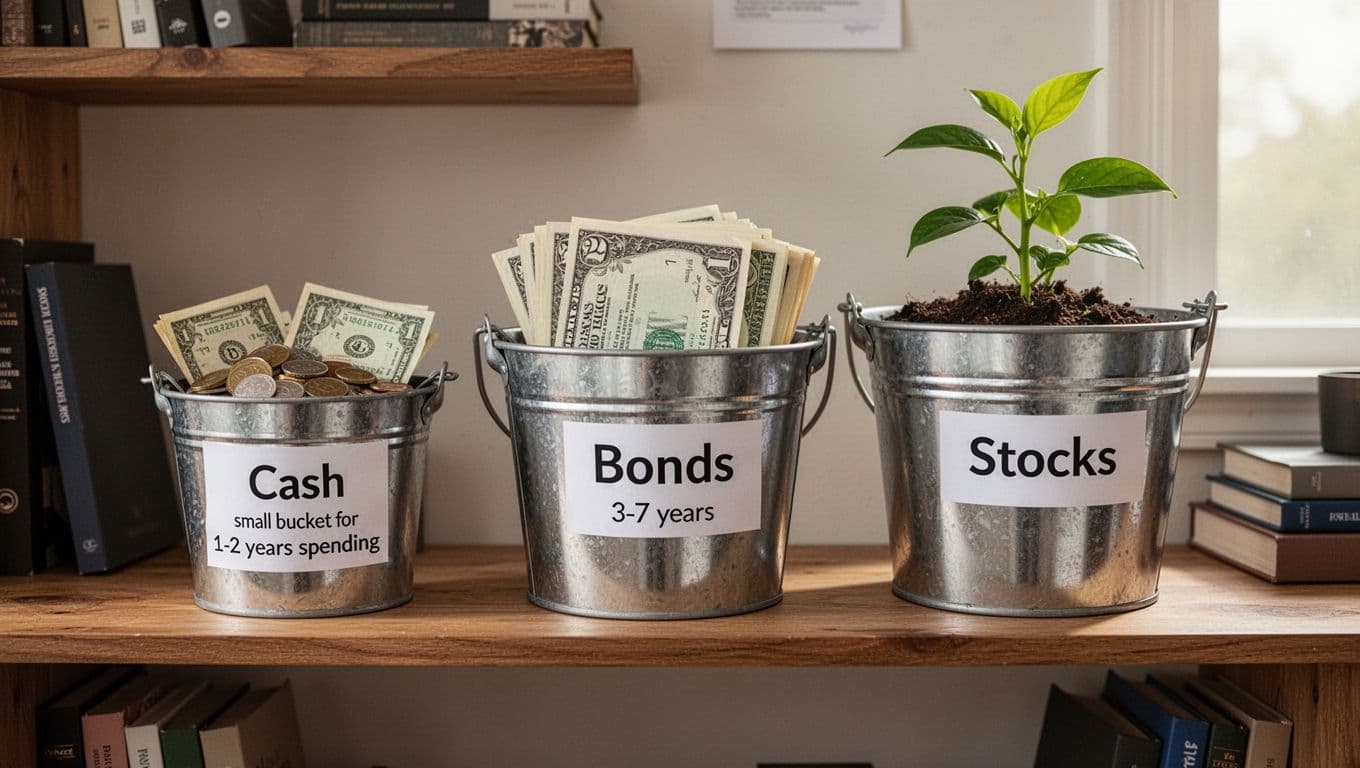
The part that makes buckets work is how I refill them. I don’t refill based on vibes or headlines. I refill during scheduled portfolio maintenance, usually alongside rebalancing.
My refill rule of thumb:
- If stocks had a strong run and I’m above my target stock percentage, I trim stocks and refill bonds and cash.
- If stocks are down hard, I try to avoid refilling cash by selling stocks. Instead, I live off cash, then bonds, while I wait for recovery and rebalance when my rules say so.
This is why I call it spending plan first. I decide what I need for the next 1 to 7 years, then I invest the rest for growth.
A side-hustle “income floor” can let you sleep better
A small side hustle can do something my portfolio cannot: reduce withdrawals in the exact years I need it most. Even a few hundred dollars a month can mean fewer shares sold during a downturn. That’s a direct hit to sequence-of-returns risk.
I treat side income like a shock absorber, not a promise. In other words, I don’t build my base budget assuming I’ll always earn it. Instead, I plan for it as a bonus that strengthens my buckets.
Here’s how I like to use side income in practice:
- In bad markets: I route side income to the cash bucket first, so I can delay selling stocks.
- In good markets: I can invest it, or use it to top off bonds if my allocation drifted.
- In any market: I keep my baseline spending supported by the portfolio alone, so I’m not trapped.
Good “income floor” options tend to be skills-based and flexible, like freelance work, consulting, or simple productized services. If I’m starting from scratch, I’d rather pick something I can turn on and off than something that needs perfect ad rates or viral traffic. This list of best freelance websites for beginners can help if I want a practical way to find early clients without overthinking it.
One warning I take seriously: unstable income is still unstable, even when it feels consistent for a few months.
I only count side income after it shows up for a full year, and even then, I treat it as optional.
Avoid hidden risks that make conservative portfolios fail
A conservative asset allocation can still fail if I build it around comforting stories instead of real risk. The sneaky problems are usually boring: too much cash for too long, chasing yield, complex funds I don’t understand, ignoring inflation, and letting taxes and fees quietly eat my returns. Add emotional overreactions to news, and I’ve basically built a “conservative” plan that breaks under stress.
Chasing dividends and high yield can add risk, not remove it
High yield often shows up when something is wrong. If a bond fund is paying a lot more than safer bonds, I assume it’s taking more credit risk, meaning a higher chance of defaults or downgrades. That risk tends to show itself at the worst time, like recessions, when I most want my “safe” bucket to hold steady.
Dividend stocks can also fool me. A dividend doesn’t protect the share price. Plenty of dividend-paying companies still drop hard in bear markets, and dividends can get cut when profits shrink.
If I buy dividend funds because they “feel like income,” I might end up with a portfolio that is heavy in a few sectors (financials, energy, utilities), which is just concentration risk in a nicer outfit.
A safer mindset
- I focus on total return, not just the cash a fund throws off.
- I keep broad diversification, because boring indexes usually beat “safe stock picking.”
- I plan withdrawals on purpose, selling shares as needed, rather than forcing the portfolio to manufacture income.
One more quiet failure point is cash. Holding a cash buffer for spending is smart. Holding “too much cash” as a long-term default can make the plan fall behind, especially over decades. Cash is a parking lot, not a home.
If I need stability, I’d rather own high-quality bonds and a cash wedge than reach for yield and hope it behaves.
Inflation is the quiet threat, build in protection on purpose
Inflation doesn’t crash like stocks. It erodes. That slow leak matters in FIRE because I’m buying groceries and insurance for decades, not a few years. A conservative plan still needs some growth engine, which usually means keeping meaningful stock exposure even if I dislike volatility.
I also like inflation-linked tools when they fit. TIPS and I Bonds can help because they are designed to respond to inflation. The details matter, though, especially taxes and holding periods.
Practical moves I actually use:
- Keep some equities even in a conservative asset allocation, because inflation can outlast my patience.
- Consider I Bonds or TIPS as a “purchasing power” sleeve, not as a magic shield.
- Adjust spending in high inflation years, especially discretionary categories, so withdrawals don’t ramp up at the worst time.
When inflation spikes, it’s tempting to overhaul everything. I try not to. Small spending cuts plus a steady allocation often beat frantic portfolio changes.
Taxes and fees matter more when you play defense
When expected returns are lower (which is common in conservative mixes), every little drag matters more. A 0.60% expense ratio might not sound like much, but it’s a yearly leak. Add trading costs, bid-ask spreads, and constant fund swapping, and I’ve built friction into a portfolio that’s supposed to be calm.
Tax drag is similar. If a fund kicks off a lot of taxable income each year, I can lose a chunk of that return before it compounds. That’s why I try to keep my conservative setup simple and tax-aware.
At a high level, here’s an account placement approach that’s easy to remember:
- In taxable accounts, I prefer tax-efficient stock index funds/ETFs when possible, because they tend to distribute less taxable income each year.
- In tax-advantaged accounts (like traditional retirement accounts), I prefer bond funds and other higher-tax income investments, because ordinary income taxes on interest can be a drag in taxable.
- In Roth accounts, I like assets with higher growth potential when it fits the plan, because growth can compound without yearly tax friction.
Limiting Changes
To keep myself from “defensive overreacting,” I also limit changes based on headlines. If I wouldn’t change my plan on a calm Tuesday, I don’t change it during a scary week.
Keep it boring checklist (the kind that works):
- I don’t chase yield, I manage withdrawals.
- I keep a cash buffer for spending, but I don’t park decades of money in cash.
- I hold broad index funds, not complex products I can’t explain.
- I build inflation protection on purpose (equities, TIPS, or I Bonds as appropriate).
- I watch fees, because small leaks matter in conservative portfolios.
- I place tax-efficient funds in taxable when possible, and higher-tax income funds in tax-advantaged when available.
- I ignore breaking news, and follow my written rules instead.
Conclusion
A conservative asset allocation works in FIRE because it respects the real enemy, bad timing. Sequence-of-returns risk can wreck an early retirement even when long-term returns look fine, so I plan for the first rough years, not just the average.
I keep the structure simple, broad stock index funds for growth, high-quality bonds and (sometimes) TIPS for stability, plus a cash buffer that covers near-term spending. That mix helps me avoid selling stocks after a drop, which is the moment many FIRE plans break.
Most importantly, I write clear rebalancing rules (yearly plus 5-point bands is enough) and I pair my portfolio with flexible withdrawals, so spending can tighten before the portfolio takes lasting damage.
Here’s my 30-day action plan:
- Pick a target conservative asset allocation (like 40/55/5, 50/45/5, 60/35/5, or 50/30/20 with a bigger cash wedge).
- Choose simple, low-cost funds that match the plan, then stop adding extra “safety” funds.
- Turn on auto-investing, so progress doesn’t rely on motivation.
- Write a one-page IPS, including my downturn checklist and what would justify a real change.
- Set a rebalance reminder, then follow it instead of headlines.
- Decide my cash bucket size (6 to 24 months of expenses) and where it sits (HYSA, money market, or T-bills).
- Pick a fallback income plan for down markets (a small, realistic side gig helps)
Back to FIRE Investing Tips
Are you looking for better ways and tools to build your monthly revenue and brand? Be sure to check out our other resources located here to speed up the process.
Nathan
Dr. Nathan Pennington, DBA, earned his Doctor of Business Administration degree from the University of Missouri-St. Louis and brings over 15 years of online entrepreneurial experience in helping people learn how to blog, earn income online and build passive income streams outside of what the school system teaches.


