
Best Referral Bonus Apps

Disclosure: This post may contain affiliate links, meaning if you decide to make a purchase through my links I may earn a commission at no additional cost to you. See my disclosure for more info.
Build A Smarter Online Business
Want to turn your content into traffic, income, and long-term freedom? Start with the guides built to help you grow smarter.
Explore Online Business Guides →Referral bonuses are one of the few side hustles that can pay me for something I already do, recommending tools I’m using anyway. When I focus on the best referral bonus apps, I’m looking for offers that feel fair, pay on time, and don’t come with a bunch of gotchas.
Here’s how referral bonus apps work in plain English: I share a link or code, a friend signs up, they complete a requirement (like making a first purchase, sending a payment, or finishing a task), then I get paid. Sometimes my friend gets a bonus too, which makes it easier to get real sign-ups instead of polite “maybe later” replies.
At the same time, I keep my expectations realistic. Referrals won’t replace a full-time income for most people, but they can stack into solid extra cash, especially if I pair them with other low-effort money moves. That’s why I like them, they’re light on time, easy to track, and they fit alongside other side hustles without adding much stress.
In this guide, I’ll show how I judge referral offers so I don’t waste effort chasing bonuses that never clear. I’ll cover payout type (cash vs. gift cards vs. credits), the exact requirements, trust and track record, limits and caps, and the basics of taxes so there are no surprises later. If you want a quick comparison point before we get into my full checklist, this older roundup is a helpful reference: top 5 refer and earn apps.
Back to How to Make Money with Your Phone
How referral bonus apps actually pay you, and what to watch for
When I compare the best referral bonus apps, I don’t just look at the headline bonus. I look at how they pay, when they pay, and what has to happen in between. Most apps follow a simple funnel, but the fine print decides whether I get paid or end up with a “pending” reward that never clears.
In practice, the flow usually looks like this: I share a link or code, my friend installs the app, signs up, passes any identity checks, then completes a trigger (first purchase, first deposit, first ride, or a spending goal).
Cash, gift card, or points, picking the payout that fits my goals
If I’m doing referrals for flexibility, cash wins. Cash payouts (PayPal, bank transfer, or a prepaid debit) let me use the money anywhere, and they’re easier to value. The trade-off is that cash apps often have minimum cash-out thresholds (like $10 or $25) and sometimes payment rails have fees.
Gift cards can still be great, but only when they match what I already buy. If I know I’ll spend $50 at a retailer this month, a $50 gift card is basically cash to me. Where gift cards get annoying is when I’m forced into a brand I don’t use, or the app only offers certain denominations (like $25 minimum).
Ready To Build More Traffic And Income?
Use Internet of Business to learn blogging, SEO, affiliate marketing, passive income, and digital business systems that compound over time.
Start Building Your Digital Income →Points and “credits” are the easiest to misread. A points bonus can be fine, but it’s riskier because redemption values can change, options can disappear, and rewards can expire. The same goes for account credit, which often only offsets future purchases inside that app.
Here’s a quick example of how a “$20 bonus” shrinks in the real world:
- The app pays “$20” as points.
- Points redeem at $20 only if I cash out at $50+.
- I’m at $20 total, so I either wait, or I redeem for a gift card where the same points equal $17.50.
- If I choose an instant cash-out option with a $1.99 fee, I net $15.51.
If the payout isn’t cash, I treat the headline bonus like a coupon, not money, until I confirm the redemption value and minimums.
Requirements that matter most: deposits, spending, and time windows
Most referral bonuses exist for one reason: the app wants a new customer who proves they’re real and active. That’s why requirements tend to cluster around a few common triggers:
- Install and sign up: Basic tracking, ties the referral to a new account.
- Identity checks: Often required for anything involving payments, banking, or crypto. If my friend skips verification, the reward may never move past
pending. - First transaction: This might be a first purchase, transfer, ride, delivery, trade, or bill payment.
- Minimum spend or deposit: The app is trying to avoid paying for users who never use the product.
- Time window: Many apps require the action within 7, 14, or 30 days so they can measure the campaign.
Time windows are the one that silently kills bonuses. I’ve seen friends sign up, get busy, then miss the spending deadline by a day and lose both bonuses.
To avoid that, I keep it simple and helpful:
- I send one message with the link and the key requirement in one sentence.
- I set a reminder for day 5 and day 25 (depending on the window).
- I follow up once with, “Want me to walk you through it?” and then I stop.
That last part matters. If I act like a pushy salesperson, people drag their feet. If I act like tech support, they finish the steps.
Understanding limits, fraud rules, and why bonuses sometimes get denied
Bonus denials usually aren’t personal, they’re automated rules. Referral programs are magnets for abuse, so apps build filters that can accidentally catch normal users too.
Here are the big denial triggers I watch for:
- One account per person: Duplicate accounts, even “by accident,” can void rewards.
- Same household limits: Some apps restrict bonuses if you share an address, payment method, or device with another user.
- Device and network rules: Multiple accounts on one phone can flag you. VPN use can also raise fraud alerts because it hides location.
- Chargebacks and reversals: If the qualifying purchase gets refunded, the app may claw back the bonus.
- Geo restrictions: Some referral offers only apply in certain states or regions.
- Bonus caps and invite limits: You might only get paid for the first 5 to 25 referrals, even if your link keeps working.
- Expired rewards: Points or credits can expire if you don’t redeem them in time.
Staying compliant is mostly common sense, but I treat it like a checklist because small mistakes cost real money:
- I use one account per person, and I tell friends to do the same.
- I avoid VPNs while signing up and completing the required action.
- I keep receipts and confirmation emails until the reward pays out.
- I don’t spam my link in places that violate terms (some apps ban public posting).
- I screenshot the offer terms before I share the link, because offers change often.
Finally, before I send any referral link, I run this quick personal gut-check:
- What payout type is it, and what’s the real cash value?
- What exact action qualifies (deposit, spend, first transaction)?
- What’s the deadline for my friend to complete it?
- Is there a hold period before it pays, and can it expire?
- Any household, device, or location limits that could block it?
My criteria for choosing the best referral bonus apps
When I’m sorting through the best referral bonus apps, I don’t start with the bonus amount. I start with a repeatable scorecard, because the fastest way to waste time is chasing flashy offers that friends never finish, or that sit in “pending” forever.
Here’s the framework I use to judge an app before I share anything:
- Real-world usefulness: Would I still use it if there were no bonus?
- Simplicity of referral steps: How many steps until my friend qualifies, and how easy are those steps?
- Payout speed: How soon can the reward move from
pendingto paid? - Transparency of terms: Are requirements written in plain language, with clear deadlines and caps?
- Customer support quality: Can a real person fix tracking issues, or am I stuck with bots?
- Long-term value: Is there a reason for friends to stay active, so referrals compound over time?
I also separate apps into two buckets: high-intent (banking, investing, credit) and low-friction (cashback, shopping, rewards). High-intent offers can pay more, but people hesitate because money and identity checks are involved. Low-friction offers pay less, but they convert like a wide-open door.
High payout is nice, but I care more about how easy it is for friends to finish
A referral bonus is only “big” if it actually clears. I’ve learned to value completion rate more than headline dollars, because an easy finish stacks up like steady drip irrigation, while a hard offer is a rain barrel most people never fill.
Here’s a simple comparison I use when I’m deciding what to share:
| Offer type | Bonus | Friend must do | Typical completion reality |
|---|---|---|---|
| High-intent finance app | $50 | Deposit $500 | Many people stall, question it, or miss the deadline |
| Low-friction rewards app | $10 | Free sign-up | Most people can finish in minutes |
If I share the $50 offer with 10 friends and only 1 completes it, I make $50. If I share the $10 offer with 10 friends and 7 complete it, I make $70, and I didn’t need anyone to move serious money.
That’s why I weight simplicity heavily. In my scorecard, I reward programs where the trigger is clear (sign up, verify email, maybe one small action). I still like high-intent apps, but I treat them like “high-touch” referrals and only send them to friends who already want that product.
How fast I can get paid, and what “pending” really means
Timing matters because referral programs don’t pay on vibes, they pay on settled transactions. In general, I see three payout windows:
- Instant to same day: Rare, but possible when the qualifying action is low risk.
- 1 to 7 days: Common for standard app tracking and basic settlement time.
- 30+ days: Common when the app wants to clear return windows, chargeback risk, or deeper fraud checks.
A reward usually goes pending for boring reasons, not because you did something wrong. The big causes are bank settlement time, refund and return windows (especially for shopping offers), and fraud and identity checks designed to catch fake accounts.
To stay sane, I track referrals like a lightweight project. A simple spreadsheet with date shared, date completed, and expected pay date tells me when I should follow up, and when I should escalate to support. If you want a real example of how ongoing referral earnings can work when users stay active, see my Ysense refer and earn program.
My rule: if an app can’t explain payout timing clearly, I assume it will be slow.
Trust signals I look for before I ever share my link
I protect my reputation first, because one sketchy app can burn trust with friends fast. Before I share, I look for a few trust signals that are hard to fake:
I check app store history and read the most recent reviews, not just the top ones. I also scan Better Business Bureau complaint patterns (not a single rating) to see if the same issue repeats, like “couldn’t cash out” or “support stopped replying.”
Next, I look for real contact options. A clear help center, email support, and an in-app chat path tell me the company expects problems and plans to solve them. Plain language terms matter too. If the rules read like a trap, I move on.
Privacy is the other deal-breaker. I avoid apps that ask for unneeded permissions, like contacts access when a referral link works fine without it. On my side, I keep it simple:
- I use a separate email for side hustles and sign-ups.
- I turn on two-factor authentication anywhere money touches the account.
- I don’t share links if the app’s privacy policy feels vague or incomplete.
If an app checks these boxes, I’m comfortable putting it in my “share again” list, not just my “try once” pile.
The best referral bonus app categories, and where each one shines
When I’m trying to pick the best referral bonus apps, I don’t start by hunting for the biggest bonus. I start by matching the app category to the person I’m inviting. Different categories “convert” for different reasons, and the easiest categories usually win because my friends finish the steps.
Below are the categories I’ve had the best results with, what they’re best for, what your friend usually has to do, a broad sense of bonus range, and the main pros and cons. Before I share any link, I also remind people that offers change, so it’s smart to confirm the current requirements inside the app.
Cashback and shopping apps, the easiest wins for most people
Cashback and shopping referrals convert well because they fit into something people already do. Nobody needs a new habit. They just need to route a purchase through a portal, activate an offer, or link a card.
Best for: Friends who shop online, buy groceries, or like getting a little money back without thinking too hard.
What friends must do: Usually a first purchase through the app or portal, a receipt scan, or linking a card and using it at a participating store.
Typical bonus range: Usually small to medium, but it adds up because completion rates are high.
A few conversion triggers show up again and again:
- The friend already planned to buy something, so the “first purchase” requirement feels natural.
- The qualifying step is clear, like “buy once” or “link card,” instead of “deposit $500.”
- The reward often posts after return windows, but the process feels simple.
Best practices that keep this category easy:
- I recommend stores my friends already use (Target, Walmart, Amazon-type shopping). If they don’t love the store, they won’t bother.
- I share around big sales and seasonal shopping (back-to-school, Black Friday, holiday travel bookings).
- I avoid spammy posting. Instead, I send one helpful message: “If you’re buying X anyway, run it through this app first.”
Pros: High completion rate, low risk, easy to explain in one text.
Cons: Smaller bonuses, payout can be delayed by returns, some purchases don’t track if coupon codes or ad blockers interfere.
Investing and free-stock apps, higher bonuses but more steps
Investing and “free stock” referrals can pay more, but they come with more friction. People hesitate when identity checks and money transfers show up, even if the app is legitimate.
Best for: Friends who already want to start investing, open a brokerage account, or move a small amount into a platform.
What friends must do: Common steps include opening an account, completing identity verification, connecting a bank, and making a deposit or completing a trade.
Typical bonus range: Often medium to high, sometimes paid as stock, not cash.
This category has a few common “gotchas” that can surprise people:
- Verification delays: If their ID check fails or takes days, they can miss the promo window.
- Deposit and settlement timelines: A deposit might need to clear before the bonus triggers.
- Lockup periods: Some programs require keeping funds in the account for a set time.
I treat the bonus like a tip jar, not the plan. Markets move, and the last thing I want is a friend blaming me for a dip that had nothing to do with the referral.
Here’s my safe approach:
- I tell friends to start small, because they can always add more later.
- I push them to read the fee schedule, especially anything tied to transfers, margin, crypto spreads, or account closure.
- I remind them the bonus is a perk, not the reason to invest.
Pros: Bigger upside, good fit for motivated friends, can be a long-term financial upgrade.
Cons: More steps, possible fees, market swings, and extra rules like holding periods.
Banking and fintech apps, great when you can help someone set it up right
Banking and fintech referrals can be great, but they’re picky. The requirements often involve direct deposit, debit card spending targets, or maintaining a balance. In other words, a friend can’t just “sign up and forget it.”
Best for: Friends who already want a new checking account, a better app experience, or a clean way to separate bills from spending.
What friends must do: Often one of these triggers: set up direct deposit, hit a debit card spend requirement, make a certain number of transactions, or keep funds in the account long enough.
Typical bonus range: Usually medium to high, because the bank is paying for a sticky customer.
Where this category shines is when I can act like setup support. One clean setup often beats three half-finished attempts.
Tips that help referrals actually clear:
- I only suggest it to people already shopping for a new account. Cold pitching a bank bonus rarely works.
- If direct deposit is required, I offer to walk them through updating payroll, because that’s where people stall.
- When payroll feels like too much, a small recurring transfer sometimes works (depending on the terms). I still tell them to verify what qualifies, because “direct deposit” can be defined narrowly.
Pros: Strong payouts, useful product, good chance of recurring use.
Cons: Harder to complete, longer wait times, strict definitions of “qualifying deposit.”
Gig, delivery, and task apps, strong for people who want to earn too
Gig app referrals can be strong because your friend is not just signing up, they’re signing up to get paid. Still, the requirements are usually performance-based, so patience matters.
Best for: Friends who want flexible work, have a steady schedule, and can meet onboarding requirements.
What friends must do: Typically get approved, then complete a set number of deliveries, rides, or tasks within a time window.
Typical bonus range: Often medium to high, but it depends heavily on market and season.
The big variable here is demand. Some cities are busy year-round, while others slow down after the holidays. Seasonality shows up fast, especially in food delivery and shopping gigs. Local promotions also change, so two people in different zip codes might see different referral terms.
I also get honest about costs. A referral bonus looks great until someone forgets:
- gas and charging costs
- wear and tear
- insurance considerations
- extra time driving between orders
Pros: High earning potential, clear “work X jobs” requirement, great for motivated friends.
Cons: Approval delays, market-dependent earnings, real vehicle costs.
Travel and ride-share apps, best for frequent travelers and planners
Travel referrals can work extremely well, but only with the right audience. If someone rarely travels, they will not complete the first booking. On the other hand, frequent travelers already have the habit, so the referral feels like a free rebate.
Best for: Friends who travel for work, families planning vacations, and anyone who books hotels, flights, or rental cars regularly.
What friends must do: Usually create an account and complete a first booking (sometimes through a mobile app, sometimes within a set time).
Typical bonus range: Often medium, and it may come as travel credit instead of cash.
I see travel referrals shine in two scenarios:
- Someone is already planning a trip and just needs a “best place to book” nudge.
- A friend likes points and rewards, so they understand credits and redemption rules.
Pros: Can be valuable for frequent use, easy to time around real trips.
Cons: Credits can expire, blackout rules may apply, and cancellations can reverse the trigger.
Money transfer or payment apps, quick setup, but strict anti-fraud rules
Payment apps feel simple, but they can be surprisingly strict behind the scenes. Anti-fraud systems watch these programs closely, so you want clean behavior.
Best for: Friends who already split bills, pay rent with roommates, or send money to family.
What friends must do: Usually sign up, verify identity, link a bank or card, then send a first payment or complete an “add funds” step.
Typical bonus range: Usually small to medium, with occasional higher promos.
I’ve found two habits make a big difference in avoiding bonus headaches:
- I tell friends to complete the first transaction with a real purpose (splitting dinner, paying for a group gift), not a weird back-and-forth loop.
- I discourage VPNs, duplicate accounts, and shared devices, because those can cause “pending forever” problems.
Pros: Fast onboarding, easy explanation, natural use case for many people.
Cons: More fraud flags, reversed transactions can claw back bonuses, some offers exclude households or repeat users.
If I’m ever unsure which categories to focus on first, I keep a short shortlist of proven earners and rotate based on my friends’ needs. I also keep a running list of top money-making apps with referral bonuses on my own resource page: recommended tools and earning apps.
A simple plan to earn more from referrals without annoying people
When I want better results from the best referral bonus apps, I treat referrals like a favor, not a hustle. My simple system is: pick 2 to 3 apps that fit my audience, write a short “why it helps you” message, share it in the right places, then follow up once. After that, I track outcomes and tighten the process.
Before I share anything, I pick 2 to 3 offers that match real needs. For example, I’ll choose one low-friction cashback app, one payment app people already use, and one higher-payout finance app for friends who are already shopping for it. Keeping it to a short list helps me stay consistent, and it keeps my messages clean.
My north star: if I wouldn’t recommend the app without a bonus, I don’t send the link.
Start with people who already trust me, then expand slowly
Warm audiences convert because the trust is already there. I start with people who know me well, and I expand only after I’ve seen a few clean payouts.
My best “warm” buckets are:
- Family and close friends who already ask me what apps I use.
- Coworkers, but only if it’s allowed and I keep it low-key.
- Existing followers (email list, blog readers, social followers) who opted in to hear from me.
The key is how I frame it. I don’t lead with “help me out.” I lead with saving them money or making their next step easier, because that’s the real value.
Here’s the wording style that keeps it feeling like a tip, not a pitch:
- Start with their situation: “If you’re already ordering groceries this week…”
- Name the benefit first: “You can get $10 back…”
- Be upfront about my bonus (when true): “Full disclosure, I get a bonus too.”
- Give them an easy out: “No worries if it’s not your thing.”
I also stick to ethical channels where people expect recommendations:
- One-on-one texts (best for high-intent apps)
- Niche groups that allow it (and only in the right threads)
- Email newsletter (people subscribed for tips)
- My blog (a resource page or a short callout in a relevant post)
- Social bio link (quiet, always there, no spam posts)
The message that gets the most sign-ups, short, clear, and helpful
The message that performs best for me is short and specific. It includes (1) what they get, (2) what they must do, (3) the deadline or time window, and (4) that I get a bonus too if that’s part of the deal.
Below are templates I reuse and tweak. I keep the tone casual, like I’m sharing a coupon.
Template 1 (text to a friend, low-friction app)
“Quick tip: If you’re shopping online this week, this app gives you a sign-up bonus after your first purchase. I get a bonus too (full disclosure). If you want it, use my link, then make a purchase within the deadline listed in the app.”
Template 2 (text to a friend, higher-friction finance app)
“I’m using [App Name] for [one benefit]. They’re doing a referral bonus right now, and we both get it if you sign up and complete the required step (usually a deposit or first transaction) by the deadline. Want the link and the exact steps?”
Template 3 (follow-up once, not pushy)
“Friendly reminder in case you started it: the bonus only triggers after the required step. If you want, tell me where you’re stuck and I’ll help. If not, all good.”
Template 4 (social post, consent-based)
“I only share referrals I actually use. If you’re already planning to [shop, send money, open an account], I have a referral link that gives a bonus (and yes, I get one too). DM me and I’ll send the steps and the deadline so you don’t miss it.”
Template 5 (blog callout)
Referral bonus note: If you’re trying [App Name], use my referral link for a bonus when you complete the required step (check the app for the deadline). I may receive a bonus too, and I only recommend tools I’d use anyway.
Track results like a mini business so I know what is working
If I don’t track referrals, I end up guessing. A simple tracker also keeps me from forgetting pending bonuses, and it gives me clean records at tax time.
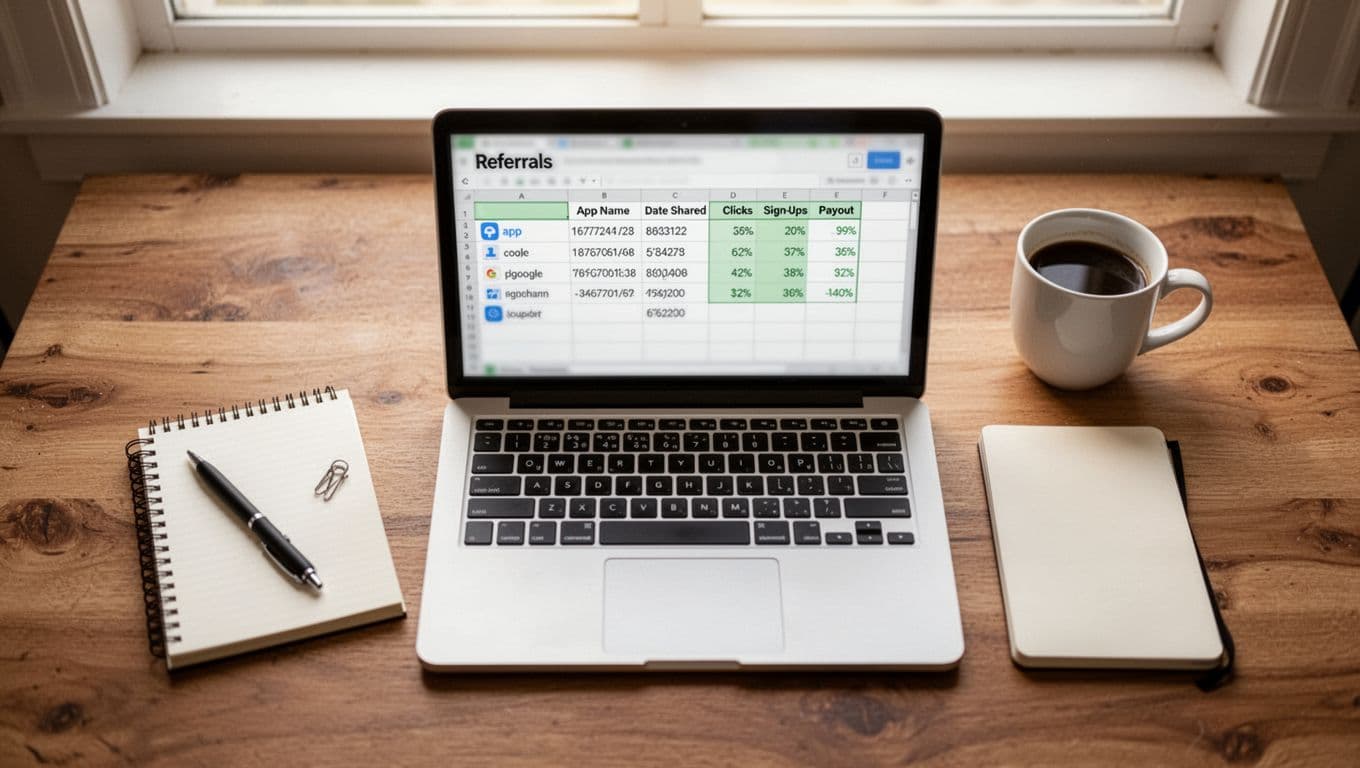
I use a spreadsheet (or notes app) with these columns:
| Field | What I record | Why it matters |
|---|---|---|
| App name | The exact app and offer version | Offers change, I need context |
| Link location | Text, email, blog, bio, group | Shows which channel converts |
| Date shared | When I sent it | Helps time follow-ups |
| Clicks (if available) | From a link tracker or platform | Shows interest vs. drop-off |
| Sign-ups | Who started | Helps me support the right people |
| Completions | Who finished required steps | Predicts payouts |
| Payout amount | Cash value | Real ROI, not headline hype |
| Payout date | When it posted | Flags slow or flaky programs |
Then I run a mini playbook to improve results without spamming:
- Test one app at a time for a week or two so results aren’t mixed.
- Ask one simple question when someone doesn’t finish: “Did the requirement feel confusing or too much?”
- Adjust the message, not the relationship. Usually I just add the missing step, the deadline, or a reminder about verification.
- Keep the follow-up to once, because trust is the asset that pays long-term.
Safety, taxes, and common mistakes that can cost you the bonus
Referral bonuses can feel like free money, but the “easy” part ends the second I ignore safety, skip the fine print, or treat payouts like they are not real income. When I’m chasing the best referral bonus apps, I protect three things first: my identity, my accounts (so I don’t get banned), and my relationships.
The good news is most bonus denials come from a small set of predictable mistakes. Once I built a simple safety and tracking routine, my payouts got more consistent and way less stressful.
Spotting sketchy apps and fake referral offers before I sign up
I treat referral apps like I treat used-car listings. If the deal looks too perfect, I slow down and verify everything. A legit app usually makes it easy to figure out who runs it, how it makes money, and how support works. Scammy apps hide that stuff because they want speed, not trust.
Here are the red flags that stop me from signing up:
- Unclear company info: No real company name, no physical address, no support email, or a broken website.
- Unrealistic payouts: Huge “instant” bonuses with vague requirements, especially if every action pays a lot.
- Reviews that mention missing withdrawals: A few angry reviews are normal. A pattern of “can’t cash out” is not.
- Sensitive data requests with no reason: Social Security number, full bank login, or contact list access when the app can’t explain why.
I also keep my downloads clean. I install apps only from official app stores, and I avoid third-party APKs. That one habit eliminates a lot of junk.
For payment-style apps, I also follow the basics from the FTC, because scams often look like normal transfers until it’s too late.
If an app needs my identity or bank info, it must earn that right with transparency and a track record.
Taxes and paperwork basics for referral bonuses
I plan for referral bonuses like they are income, because many of them are. In plain terms, cash bonuses and bank bonuses are often treated as taxable, and some companies may send tax forms (often a 1099 type form) depending on how the bonus is structured and how much I earn in a year. Rules vary by company, so I don’t guess when the numbers get meaningful.
A simple way I think about it:
- Cash or cash-like rewards (PayPal cash, bank deposits, prepaid cards) often behave like income.
- Points, discounts, and statement credits can be treated differently in some cases, especially when they act more like a rebate. Still, I track them because a “reward” can turn into a form later.
When I want background reading, I look at high-level explanations from reputable sources, then I confirm how my specific app reports rewards. These two are helpful starting points:
To stay organized, I keep it boring and consistent:
- I maintain a simple income log with date, app, bonus type, amount, and payout method.
- I set aside a small percentage for taxes once payouts start adding up.
- I separate my side-hustle activity from personal life by using a separate email, and when it makes sense, a separate bank account or payment account for payouts.
I’m not a tax pro, so if I’m earning more than “fun money,” I ask one. The peace of mind is worth it.
Mistakes I see all the time, and how to avoid them
Most referral bonus failures look like “the app cheated me,” but the pattern is usually simpler. People miss a step, miss a deadline, or trigger fraud rules by accident. I’m careful here because the same behavior that loses a bonus can also get an account flagged.
These are the mistakes I see most:
- Sharing expired promos: Referral terms change fast. If I don’t re-check the offer, I’m sharing a dead link.
- Not reading the terms: One phrase like “new users only” or “first transaction within 7 days” decides everything.
- Forgetting the referral code: Some apps require the code at sign-up, not after.
- Missing the time window: A friend signs up, gets busy, then completes the action on day 31.
- Inviting people who won’t complete the steps: High-friction offers need high-intent friends, not random blasts.
- Getting banned behavior: VPN use, multiple accounts, public posting where it’s not allowed, or “looping” payments back and forth can trigger fraud systems.
One more thing matters just as much as the rules: relationships. I never pressure anyone, and I don’t spam communities that forbid links. I’d rather earn slower than burn trust.
When I want clean results, this is what I do instead:
- I screenshot the terms, then I share the link with a one-sentence requirement and deadline.
- I remind my friend to complete the steps immediately, while the promo is still active.
- I follow up once, then I stop.
- I track pending bonuses, and I keep receipts until the reward clears.
Conclusion
The best referral bonus apps aren’t the ones with the biggest headline payout, they’re the ones my friends will actually finish and keep using. When I judge an offer, I focus on the payout type (cash beats fuzzy points), the exact trigger (deposit, spend, first transaction), the time window, and the fraud rules that can quietly block a reward. I also protect my reputation by sharing only apps I’d use with or without the bonus, because one bad recommendation can cost more than any referral payout.
My simple 30-day action plan looks like this.
First, I pick one low-friction cashback or shopping app category because it’s easy to complete with a normal purchase, and it usually feels like a helpful tip instead of a sales pitch. Next, I pick one higher-value category that fits the person, either banking (great for someone already switching accounts) or investing (best for someone who already wants to start). After that, I read the terms inside the app, then I screenshot them so I can confirm the deadline and steps.
Then I share the offer with 5 trusted people, one-on-one, with a single sentence that includes the requirement and time limit. I follow up once, and only once, to help them finish. Finally, I track results for 30 days (date shared, who completed, expected payout date, and what actually paid) so I can keep what works and cut what doesn’t.
If you want extra low-friction options to pair with referrals, I also keep a list of play and earn real money with gaming apps.
See our Best Apps for Refer and Earn
Are you looking for better ways and tools to build your monthly revenue and brand? Be sure to check out our other resources located here to speed up the process.
Nathan
Dr. Nathan Pennington, DBA, earned his Doctor of Business Administration degree from the University of Missouri-St. Louis and brings over 15 years of online entrepreneurial experience in helping people learn how to blog, earn income online and build passive income streams outside of what the school system teaches.


