
Your Guide to Finding the Best Bank Account Bonus

Disclosure: This post may contain affiliate links, meaning if you decide to make a purchase through my links I may earn a commission at no additional cost to you. See my disclosure for more info.
Build A Smarter Online Business
Want to turn your content into traffic, income, and long-term freedom? Start with the guides built to help you grow smarter.
Explore Online Business Guides →Finding a great bank account bonus can feel like free money, and you might have wondered if those ads promising $200 or $300 are real. The short answer is yes. These cash incentives are a powerful way for financial institutions to win your business.
Think of it as a welcome gift. Banks offer you a piece of their marketing budget for becoming a new customer. It’s a win-win. They grow their customer base, and you get some extra cash with relatively little effort.
Back to FIRE Saving Strategy
What Are Bank Account Bonuses
At its core, a bank bonus is a simple marketing tactic. Banks need customer deposits to operate. This is the money they use to fund loans and other investments. To get those deposits, they’re willing to pay you.
The competition for your money is fierce. Between 2019 and 2024, funds managed by banks grew by a staggering $122 trillion. Many institutions are dangling bigger signup bonuses to attract new depositors. This helps them grab a larger slice of the pie. Recent McKinsey insights on global banking trends highlight this competitive space.
The Different Types of Bonuses
You will notice offers come in a few common flavors. Knowing the difference is key to finding a bonus that aligns with your financial habits.
Here are the main types you’ll run into:
Ready To Build More Traffic And Income?
Use Internet of Business to learn blogging, SEO, affiliate marketing, passive income, and digital business systems that compound over time.
Start Building Your Digital Income →- Checking Account Bonuses: These are probably the most common. The bank usually asks you to set up a qualifying direct deposit. This might be a paycheck or government benefits for a few months.
- Savings Account Bonuses: These offers hinge on bringing in “new money.” You’ll typically need to deposit a specific amount. You must keep it in the account for a set period, often 90 days or more.
- Business Account Bonuses: Often the most generous offers, these are geared toward entrepreneurs. The requirements are usually steeper. They demand higher deposit amounts or a certain number of monthly transactions.
To really compare these offers like a pro, you need to understand the real return. A great place is understanding Annual Percentage Yield (APY). It puts the bonus into perspective against the money you have to tie up.
The core idea is simple: a bank pays you a one-time fee to become a customer. For entrepreneurs and side hustlers, this represents one of the lowest-effort ways to generate a new income stream.
Why This Is a Smart Financial Move
Chasing bank bonuses isn’t just about grabbing free money. It’s a genuinely smart financial move. Successfully earning a bonus forces you to pay close attention to details. You must track dates and manage your money. These are all fantastic financial habits to build.
Improving your general financial awareness helps you spot the best opportunities. It also helps you avoid potential pitfalls. When done right, these bonuses offer a fantastic return on your time. They can give a nice boost to your savings goals or fund your next project.
How to Find the Best Bank Bonus Offers
Finding a great bank account bonus is all about knowing where to look. You could hop from one bank website to another, but that’s a fast track to burnout. A much smarter approach is to use resources that already do the heavy lifting.
I always start my search with reputable financial blogs and deal aggregator websites. A site like Doctor of Credit is a goldmine for this stuff. They maintain massive, constantly updated lists of bank bonuses. These sites are fantastic because they list the deals and include fine-print details. They also offer real-world feedback from people who’ve gone through the process.
Sourcing High-Value Offers
If you want a steady stream of good bonus opportunities, you need a system. I have a small handful of sources I check regularly. Each source offers a unique angle.
- Deal Aggregator Sites: These are non-negotiable for serious bonus hunters. They pull together offers from countless banks, saving you research time. I’d recommend bookmarking at least one.
- Major Financial Blogs: Big-name personal finance blogs are great for finding “best of” lists. They tend to spotlight appealing offers from major players like Chase or U.S. Bank.
- Direct Bank Promotions Pages: If you have a relationship with a bank, head straight to their website. Look for a “promotions” or “offers” link. This is where you’ll find the official terms and conditions.
The real secret is to stop searching passively and start building a routine. A quick 15-minute check of your trusted sources each week will put you ahead of the curve. You’ll spot the most lucrative deals the moment they drop.
How to Compare Bonuses Effectively
Once you have a list of potential offers, it’s time to vet them properly. That big, shiny $300 bonus is tempting, but it’s just the headline. The real value is hidden in the details.
To figure out if an offer is worthwhile, you have to dig a little deeper. How much do you have to deposit to get the bonus? A $300 bonus requiring a $15,000 deposit is different than one needing a $1,500 direct deposit. You also need to know how long your money is tied up. Consider if monthly fees will chip away at your earnings.
This kind of incentive isn’t just limited to traditional banks. Other financial apps often have their own promotions. For more, see our guide on how to get free cash on Cash App.
An easy way to compare offers is by calculating a rough “return on deposit.” Just divide the bonus amount by the required deposit. This simple math cuts through the marketing fluff. It shows you which offer truly gives you the most bang for your buck.
Cracking the Code on Bank Bonus Requirements
Getting a bank bonus isn’t just about signing up. It’s about playing by the bank’s rules. These offers are designed to attract sticky, long-term customers. They attach some strings to make sure you’re serious. The key to getting cash is reading and understanding the fine print.
You’ll almost always have a set window to meet all conditions. This is usually 60 to 90 days from when you open the account. Miss just one, and you can kiss that bonus goodbye. It’s all about precision.
This whole process isn’t that complicated when you break it down.
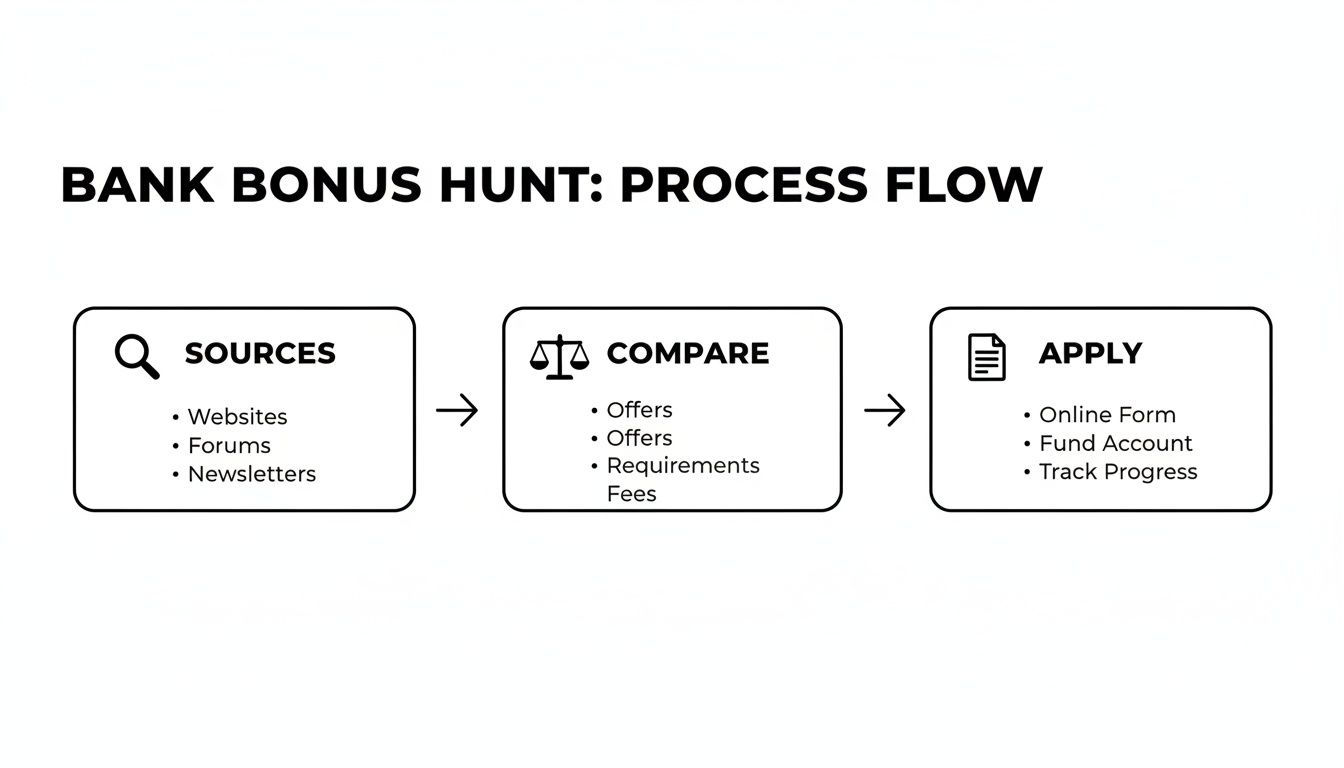
As you can see, the real work is in the details. You must compare the terms. Make sure you can hit every requirement before you apply.
The Direct Deposit Dilemma
The most common requirement is the qualifying direct deposit. This means a regular electronic deposit from an employer’s payroll or a government benefit. The required total can be anywhere from $500 to $5,000 or more. This must be done within that initial 60-90 day period.
But what if you’re a freelancer or have a side hustle? Don’t worry, you’re not out of the game. Many banks use automated systems. They can’t always tell the difference between a real payroll deposit and an ACH transfer.
My Go-To Tip: I’ve often found that pushing money from an external account like PayPal, Wise, or even a brokerage account works just as well. Before you try, search online forums like Doctor of Credit for recent “data points.”
It’s also worth noting that most of these offers are for U.S. residents. If you’re not a resident, you can still give it a shot. First, check out a guide to opening a US bank account for non-residents. This will help you understand the specific hurdles you’ll face.
Common Bank Bonus Requirements and How to Meet Them
Direct deposits aren’t the only hoop to jump through. Banks use a few other common requirements. The table below breaks down what they are and how you can easily meet them.
| Requirement Type | What It Means | Side Hustle Strategy to Meet It |
|---|---|---|
| Qualifying Direct Deposit | Electronic deposit from payroll or government benefits. | Initiate an ACH transfer from an external account (like PayPal, Wise, or another bank). Check online data points for what works. |
| Minimum Balance | Deposit “new money” and keep it in the account for a set time (e.g., 90 days). | Set a calendar alert for the date the holding period ends. Don’t touch the funds until then. |
| Debit Card Transactions | Make a specific number of debit card purchases (e.g., 5-15) within the qualification period. | Buy a few small gift cards on Amazon or pay for your daily coffee. These small, planned purchases add up quickly. |
Meeting these terms is all about organization. Once you know the rules, you can create a simple checklist. Set reminders to stay on track.
Keeping Track of Minimums and Transactions
Beyond the direct deposit, there are other things to watch. This helps avoid accidentally disqualifying yourself.
Minimum Balance Requirement: This is common with high-yield savings account bonuses. You must deposit “new money” from an outside institution. Then you leave it there for a period, like 90 days. If your balance drops below the required amount, the bonus is usually voided.
Debit Card Transactions: Another popular one is requiring a set number of debit card purchases. This is often between 5 and 15 transactions. These are almost always purchases, not ATM withdrawals.
While it might sound like a lot to juggle, it’s manageable with planning. The discipline for a great credit score is the same kind needed for bonus hunting. If you’re looking to improve your financial habits, our guide on building a 750 credit score is a great start.
By reading the terms and setting reminders, you can meet every condition and collect your bonus.
Avoiding Common Pitfalls and Hidden Fees
There’s nothing like seeing a fresh bank bonus hit your account. But that high can turn sour if you get blindsided by hidden fees. A $300 bonus doesn’t feel great when you’ve paid $150 back to the bank.
The secret to keeping every dollar you earn is knowing what to look for. Check for these traps before you open the account. Let’s break down the most common ones.
Watch Out for Monthly Maintenance Fees
Many accounts with the best bonuses come with a monthly maintenance fee. This is usually between $10 to $25. It might not sound like much. But a $15 monthly fee for six months adds up to $90. That’s a huge dent in your bonus.
Luckily, these fees are almost always avoidable.
The easiest way to get the fee waived is by maintaining a minimum balance. The bank’s terms will spell this out clearly. For example, they might waive a $12 fee if you keep a daily balance of $1,500.
Another common workaround is setting up a qualifying direct deposit. Sometimes even a small, regular transfer is enough to keep the account fee-free. Just make sure you read the fine print to know exactly what qualifies.
The single biggest mistake I see people make is this: they hit the bonus requirements, celebrate, and then let the account balance drop. That’s when those monthly fees kick in and quietly drain the bonus.
The Cost of Closing an Account Too Soon
Once that bonus cash is yours, the temptation is to grab the money and run. But closing the account too quickly can trigger an early account closure fee. These penalties typically run from $25 to $50. Some banks are harsher—they might even claw back the entire bonus.
To avoid this, you need to read the account agreement. Look for any mention of a minimum open period. Most banks expect you to stick around for at least 90 to 180 days.
Here’s a quick checklist I use to protect my bonuses from fees:
- Scour the Fee Schedule: Before you apply, find the bank’s official fee schedule. It’s usually a PDF on their site that lists every single potential charge.
- Set a Calendar Reminder: The moment the account is open, I put a reminder on my calendar. I note the day I can safely close it (e.g., 181 days from the open date).
- Automate Everything: If you’re using a minimum balance to waive a fee, set up an automatic transfer. This ensures your balance never dips below the threshold.
A little patience and organization are all it takes to make sure your bank bonus hunt is a profitable one.
Building Your Long-Term Bonus Strategy
Finding a great bank account bonus can feel like a one-off win. But with a bit of planning, you can turn it into a steady source of extra income. This is about shifting your mindset from a random windfall to a strategic side hustle. You can consistently pull in hundreds, or even thousands, of dollars every year.
The trick is to look beyond the flashy headline number. A $300 bonus sounds amazing, but you have to peel back the layers. What are the monthly fees you can’t get waived? What’s the opportunity cost of parking your cash there? That’s where the real evaluation begins.
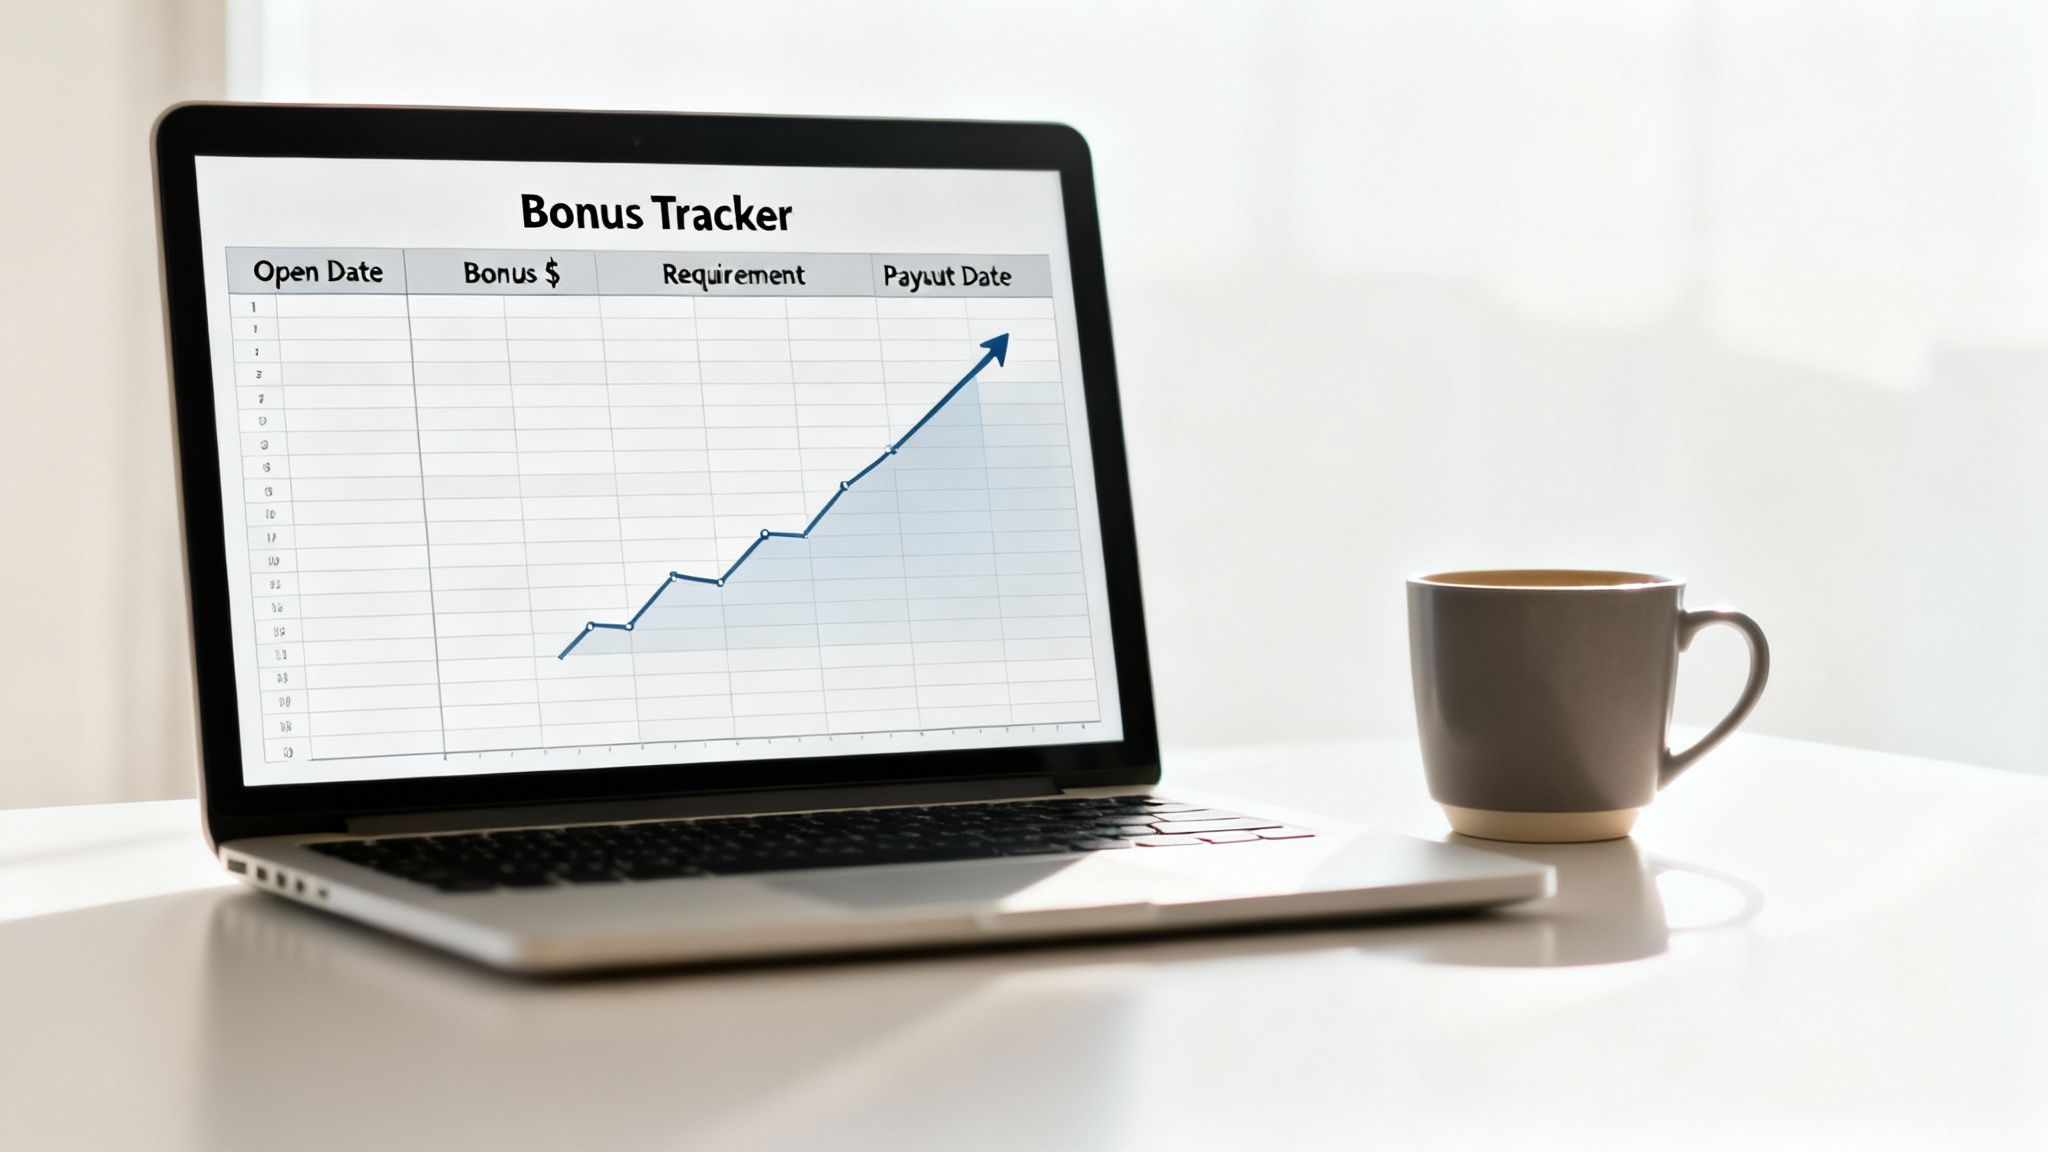
Figure Out Your Annualized Return
To really compare apples to apples, you need to calculate the annualized return. This simple formula turns the bonus into a percentage. It makes it clear which deals give you the most bang for your buck.
Let’s walk through a common scenario:
- Bonus Offered: $300
- Deposit Needed: $15,000
- Time Commitment: 90 days (which is 0.25 of a year)
Here’s the math: ($300 bonus / $15,000 deposit) * (1 / 0.25 years) = 8% annualized return. An 8% return is fantastic. It is especially good for a safe, short-term commitment. It easily beats most other low-risk investments you could make over that same period.
Set Up Your Churning System
In this world, “churning” means systematically opening and closing bank accounts to collect bonuses. To do this without losing your mind, you absolutely must get organized.
A simple spreadsheet is your best friend here. Seriously, don’t skip this. Set up columns to track everything:
- Bank Name
- Account Type (Checking/Savings)
- Bonus Amount
- Date You Applied
- Deadline for Requirements
- Date the Bonus Paid Out
- Earliest Date You Can Safely Close
This tracker is your command center. It will stop you from closing an account too soon and getting hit with a penalty. It ensures you nail every requirement on time. For those juggling multiple accounts, the techniques in our guide to velocity banking can be a lifesaver.
The real secret is consistency. If you get into a rhythm of opening a new account every few months, you build a pipeline of incoming cash. What starts as a small experiment can quickly snowball into a significant income stream.
Understanding the Scale of This Opportunity
This isn’t just some niche hobby for a handful of people. Between 2020 and 2024, an estimated 15 million Americans claimed over $1.5 billion in bank bonuses. It’s a massive market.
For those with side hustles, this can be especially powerful. You can route affiliate income or freelance payments as “direct deposits.” This can qualify you for several offers each year. A family of four could realistically net an extra $2,000 annually.
Banks aren’t stopping, either. These promotions have boosted new account openings by 12% year-over-year in major markets. They are a reliable way for banks to attract new customers. These consumer incentives will continue to be a key part of their playbook.
Common Questions About Bank Account Bonuses
Even with a solid plan, it’s natural to have a few questions before you jump in. When your money is on the line, being careful is just being smart. Let’s walk through some of the most common things people ask.
We’ll cover everything from what the IRS thinks about these bonuses to whether this will mess with your credit score. My goal is to give you all the details you need to make this a profitable and stress-free side hustle.
Are Bank Account Bonuses Taxable?
Yes, they absolutely are. The IRS views bank bonuses as interest income. It is not a gift or a product rebate. That means you’re on the hook for reporting it on your tax return.
If your bonus is $10 or more, the bank must send you a Form 1099-INT. I personally set aside a chunk of any bonus I earn to cover the taxes. It’s a simple habit that saves a lot of headaches later.
For instance, if you score a $300 bonus and your federal marginal tax rate is 22%, it’s a good idea to tuck away about $66 for Uncle Sam. Doing this upfront means no nasty surprises when you file.
Will Opening Bank Accounts Hurt My Credit Score?
For the most part, no. Opening a standard checking or savings account usually only triggers a “soft pull”. These soft inquiries are only visible to you. They have zero impact on your credit scores.
The big exception? Overdraft protection. This feature is essentially a line of credit. Applying for it will often result in a “hard pull” on your credit report. A hard pull can temporarily knock a few points off your score.
My advice is simple. If you’re opening the account just for the bonus, politely decline overdraft protection. It keeps things clean and protects your score.
How Many Bank Accounts Can I Open for Bonuses?
Legally, there’s no limit. But in practice, the banks have their own rules. Most institutions will restrict a bonus offer to one per person or household. You often have to wait 12 to 24 months before you’re eligible for another one.
Keep in mind that opening a bunch of accounts can get you flagged in ChexSystems. Think of it as a credit bureau for bank accounts. Too many recent applications can lead to denials. I’ve found that pacing yourself is key. Aiming for one new account every two or three months is a sustainable approach.
What’s the Easiest Way to Meet a Direct Deposit Requirement?
The most reliable method is always a classic paycheck or a government benefit payment. But this is not always practical for freelancers or gig workers.
The good news is that many banks have automated systems. They can’t always tell the difference between a real paycheck and a simple ACH transfer. Pushing money from an account at PayPal, Wise, or another checking account often works. Before you try this, do a quick search on financial forums for recent “data points.” You can see what’s working for other bonus hunters with that specific bank.
Back to FIRE Saving Strategy
Are you looking for better ways and tools to build your monthly revenue and brand? Be sure to check out our other resources located here to speed up the process.
Nathan
Dr. Nathan Pennington, DBA, earned his Doctor of Business Administration degree from the University of Missouri-St. Louis and brings over 15 years of online entrepreneurial experience in helping people learn how to blog, earn income online and build passive income streams outside of what the school system teaches.


